IT인증시험은 국제적으로 인정받는 자격증을 취득하는 과정이라 난이도가 아주 높습니다. National Payroll Institute인증 PF1시험은 IT인증자격증을 취득하는 시험과목입니다.어떻게 하면 난이도가 높아 도전할 자신이 없는 자격증을 한방에 취득할수 있을가요? 그 답은Pass4Test에서 찾을볼수 있습니다. Pass4Test에서는 모든 IT인증시험에 대비한 고품질 시험공부가이드를 제공해드립니다. Pass4Test에서 연구제작한 National Payroll Institute인증 PF1덤프로National Payroll Institute인증 PF1시험을 준비해보세요. 시험패스가 한결 편해집니다.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Record of Employment (ROE) | 20% | - ROE completion requirements
|
| Topic 2: Individual Pay Calculations | 40% | - Regular earnings
|
| Topic 3: Communication and Compliance | 10% | - Accuracy and documentation
|
| Topic 4: Termination and Special Payments | 30% | - Leaves and absences
|
근 몇년간IT산업이 전례없이 신속히 발전하여 IT업계에 종사하는 분들이 여느때보다 많습니다. 경쟁이 이와같이 치열한 환경속에서 누구도 대체할수 없는 자기만의 자리를 찾으려면 IT인증자격증취득은 무조건 해야 하는것이 아닌가 싶습니다. National Payroll Institute인증 PF1시험은 IT인증시험중 가장 인기있는 시험입니다. Pass4Test에서는 여러분이National Payroll Institute인증 PF1시험을 한방에 패스하도록 실제시험문제에 대비한National Payroll Institute인증 PF1덤프를 발췌하여 저렴한 가격에 제공해드립니다.시험패스 못할시 덤프비용은 환불처리 해드리기에 고객님께 아무런 페를 끼치지 않을것입니다.
질문 # 45
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)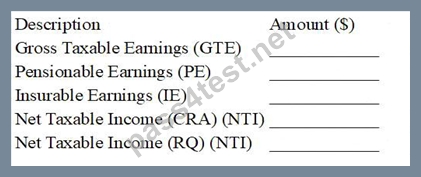
STATUTORY DEDUCTIONS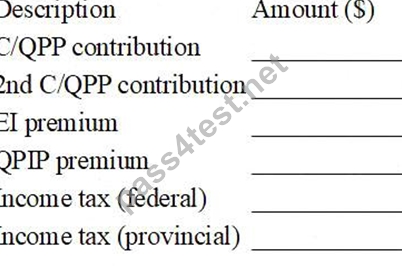
OTHER DEDUCTIONS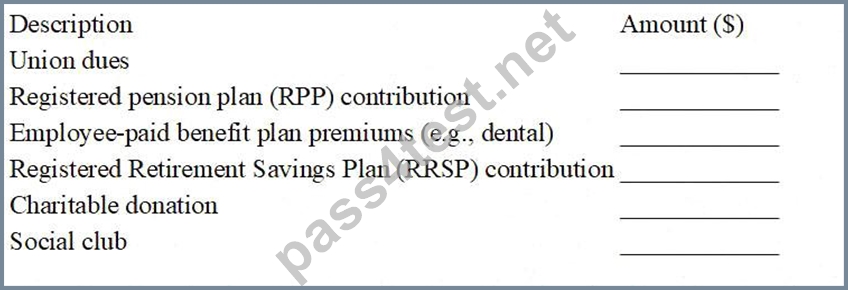
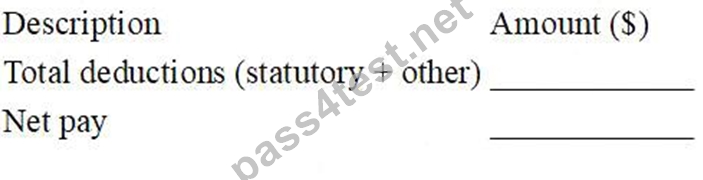
Given Data (Reference)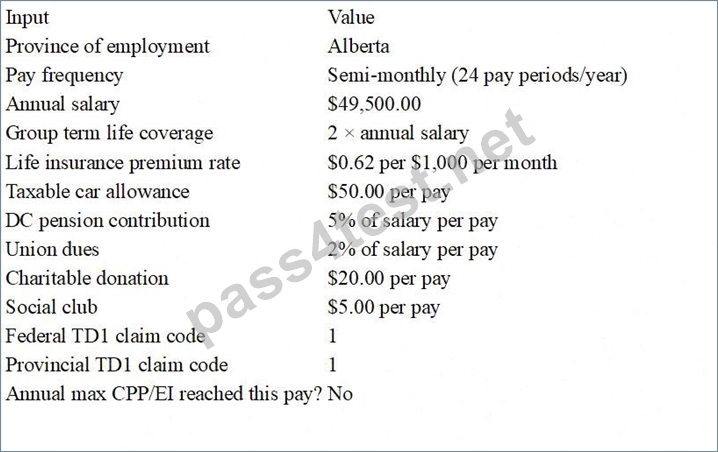
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
정답:
설명:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
질문 # 46
Ronda earns $12.50 per hour and worked 40 hours this week. Calculate her Canada Pension Plan (CPP) contribution for this weekly pay period.
정답:
설명:
$25.75
Explanation:
First calculate Ronda's pensionable earnings for the week. Her gross pay is:
$12.50 × 40 = $500.00.
CPP is calculated on pensionable earnings after subtracting the basic exemption (the Year's Basic Exemption, YBE), prorated to the pay period. The CRA confirms the YBE is $3,500 and the employee CPP contribution rate for 2026 is 5.95% for base CPP.
Weekly exemption = $3,500 ÷ 52 = $67.31 (rounded to cents).
Pensionable earnings subject to CPP this week = $500.00 # $67.31 = $432.69.
CPP contribution = $432.69 × 5.95% = $432.69 × 0.0595 = $25.745..., which rounds to $25.75.
This deduction continues each pay until the employee reaches the annual CPP maximum contribution for the year (at which point CPP stops for the remainder of the year).
질문 # 47
The authorization for hiring form should contain a checklist to ensure the organization obtains all required information. What is an example of an item that could be on that checklist?
정답:D
설명:
A strong hire-authorization/onboarding checklist ensures payroll and HR collect documents needed to pay the employee accurately and enroll them in required programs. Abenefit enrollment formis a practical, common checklist item because many employers offer benefit plans that require employee elections (for example, health/dental coverage levels, beneficiary information, dependent details, etc.). Indeed's Canadian onboarding guidance explicitly notes employers often collectbenefits enrollmentpaperwork as part of essential new employee forms and onboarding checklists.
By contrast, aT1213(Request to Reduce Tax Deductions at Source) is not routinely required for all hires; it is only used when an employee applies for CRA authorization to reduce tax withheld. A "clearance certificate" is not a standard Canada-wide payroll onboarding requirement for typical employment relationships.
Therefore, "All of the above" is not correct.
Selectingbenefit enrollment formbest matches the purpose of a hiring authorization checklist: ensuring all employment setup steps are completed (pay setup, statutory forms, and benefits enrollment where offered) so payroll deductions and coverage are handled correctly from the start.
질문 # 48
A paper Record of Employment must be issued:
정답:A
설명:
Service Canada's ROE guidance states that an employer must issue an ROE each time an employee experiences an interruption of earnings and when Service Canada requests one. This makes option A true.
For paper ROEs, the ROE guide is explicit about deadlines: you must issue a paper ROE within 5 calendar days of (1) the first day of an interruption of earnings, or (2) the day the employer becomes aware that an interruption of earnings has occurred. This confirms option B.
An interruption of earnings generally occurs under the 7-day rule-when an employee has had or is anticipated to have 7 consecutive calendar days with no work and no insurable earnings from the employer.
That's why option C is also true: once the employer becomes aware the 7-day threshold is met (or will be met), the ROE requirement is triggered, and the paper ROE must be issued within the time limit above.
질문 # 49
Paul Westin works for an Alberta organization and receives a regular salary of $1,800.00 semi-monthly. He will be receiving a payout of accrued vacation with no time taken of $1,400.00 on a separate cheque. He has federal and provincial TD1s on file with claim code 1. Calculate the income taxes to be withheld on his vacation pay.
정답:
설명:
341.50
Explanation:
CRA's method for bonus/irregular payments paid separately is to calculate income tax on the combined pay (regular pay + the irregular payment) using the regular tax tables, then subtract the tax that would apply to the regular pay alone. The difference is the income tax to withhold from the irregular payment.
Here, the semi-monthly taxable pay is:
Regular pay = $1,800.00
Regular + vacation payout = $3,200.00
Using the 2026 Alberta semi-monthly (24 pay periods) tax tables with claim code 1:
At $1,800, Federal tax = $130.45 and Alberta tax = $58.55 # Total = $189.00.
At $3,200, Federal tax = $356.50 and Alberta tax = $174.00 # Total = $530.50.
Income tax on the vacation payout = $530.50 # $189.00 = $341.50.
CPP (including the enhanced portion) is a separate statutory deduction that must also be calculated on the payout, but this question asked specifically for income tax withholding.
질문 # 50
......
PF1인증시험은National Payroll Institute사의 인중시험입니다.National Payroll Institute인증사의 시험을 패스한다면 it업계에서의 대우는 달라집니다. 때문에 점점 많은 분들이National Payroll Institute인증PF1시험을 응시합니다.하지만 실질적으로PF1시험을 패스하시는 분들은 너무 적습니다.전분적인 지식을 터득하면서 완벽한 준비하고 응시하기에는 너무 많은 시간이 필요합니다.하지만 우리Pass4Test는 이러한 여러분의 시간을 절약해드립니다.
PF1시험패스 가능한 공부자료: https://www.pass4test.net/PF1.html