BONUS!!! Download part of TestPassKing LLQP dumps for free: https://drive.google.com/open?id=1utNhrQa1O1HH2dpE1kAXY5iola3MJLJO
The IFSE Institute LLQP desktop exam simulation software works only on Windows but the web-based LLQP practice test is compatible with all operating systems and browsers. This is also an effective format for LLQP Test Preparation. The LLQP PDF dumps is an easily downloadable and printable file that carries the most probable IFSE Institute LLQP actual questions.
| Certification Vendor: | IFSE Institute |
|---|---|
| Exam Name: | Life License Qualification Program Examination |
| Exam Number: | LLQP |
| Exam Format: | Proctored Online or In-Centre, Computer-Based Exam, Multiple Choice Questions (MCQ) |
| Exam Price: | CAD 100–150 per module (varies by province/provider) |
| Certificate Validity Period: | Varies by provincial regulator; typically requires ongoing continuing education for license maintenance |
| Exam Duration: | 120–180 per module |
| Available Languages: | English, French |
| Passing Score: | 60%–70% (varies by jurisdiction and module) |
| Related Certifications: | Life Insurance License Segregated Funds and Annuities License Accident & Sickness Insurance License |
| Real Exam Qty: | Approximately 80–100 per module |
| Recommended Training: | IFSE LLQP Training Program |
| Exam Registration: | IFSE LLQP Program Registration Ontario FSRA Licensing Information |
| Sample Questions: | IFSE Institute LLQP Sample Questions |
| Exam Way: | Computer-based proctored exam delivered online or at authorized testing centres depending on province |
| Pre Condition: | No formal prerequisite, but completion of LLQP course modules is required before examination eligibility in most provinces |
| Official Syllabus URL: | https://www.ifse.ca |
>> Valid LLQP Test Question <<
It was never so easy to make your way to the world’s most rewarding professional qualification as it has become now! TestPassKing’ LLQP practice test questions answers are the best option to secure your success in just one go. You can easily answer all exam questions by doing our LLQP exam dumps repeatedly. For further sharpening your skills, practice mock tests using our LLQP Brain Dumps Testing Engine software and overcome your fear of failing exam. Our Life License Qualification Program (LLQP) dumps are the most trustworthy, reliable and the best helpful study content that will prove the best alternative to your time and money.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
NEW QUESTION # 124
Jenny purchased a whole life insurance policy 10 years ago. She was recently diagnosed with a terminal illness and the doctor told her she got an estimated life span of 12 months. She would like to spend the rest of her time with family doing vacation across the world. She brought Ellen, her daughter and also her beneficiary to the life insurance agent and wants to find out about the claims process.
What does Ellen need to know regarding the claims process in this situation?
Answer: B
Explanation:
Comprehensive and Detailed Explanation From Exact Extract:
The LLQP outlines thatto initiate a life insurance claim, the insurer requires acompleted claim form and proof of death (usually a death certificate). Coverage remains validregardless of where the death occurs.
Claims are typically processed quickly once these documents are submitted.
NEW QUESTION # 125
Agatha and Peter run a successful sole proprietorship. They are 68 and 70 respectively. Peter has a huge registered investment portfolio that will result in significant tax consequences upon his death. When both of them have passed away they would like their registered investment portfolio to go to their son, Alexander, who is 48 years old. The family would like to purchase life insurance to offset the tax liability.
Which of the following plans would best suit the family?
Answer: A
Explanation:
Comprehensive and Detailed Explanation From Exact Extract:
Joint last-to-die insurance pays out on the death of the second insured, which is ideal for estate planning needs such as covering taxes on registered assets that arise after both owners pass away. The LLQP study material confirms this structure as most suitable for deferring and covering tax liabilities post-second death.
Reference: Insurance Study Guides Chinese.pdf, Estate Planning with Joint Last-to-Die Insurance
NEW QUESTION # 126
On February 5, Ayla started working at Larson Group Inc. as an administrative assistant. Larson Group offers all employees a group health, dental and life insurance plan that commences after a 3-month waiting period.
On April 7, Ayla felt ill and drove herself to the hospital. The doctor diagnosed two clogged arteries and performed an emergency surgery. Ayla was unable to work for 2 months, then died of complications on June
9. Will the group insurance plan pay the death benefit?
Answer: A
Explanation:
Group life insurance coverage often requires the employee to be "actively at work" on the day the coverage takes effect. Although Ayla's coverage would have started on May 5, she was not actively at work on that date due to her medical condition. Most group insurance policies have this requirement, and without meeting it, coverage typically does not commence. Therefore,Option Caccurately reflects why the death benefit would not be paid.
NEW QUESTION # 127
Kaamil meets with Omar, his insurance agent, to purchase a whole life insurance policy. Kaamil wants to name his wife Ofra as the irrevocable beneficiary of the policy. Before proceeding, which of the following considerations should Omar CORRECTLY ask his client to reflect on?
Answer: D
Explanation:
When an irrevocable beneficiary is designated, the policyholder must obtain the beneficiary's consent for any changes that affect the beneficiary's rights, such as revoking their status or making policy alterations. By naming Ofra as an irrevocable beneficiary, Kaamil would be restricted from unilaterally changing this designation or withdrawing policy funds without her agreement. This requirement protects the irrevocable beneficiary's interests, ensuring they retain certain rights in the policy.
NEW QUESTION # 128
Jasper is the sole breadwinner in his family. His wife Stephanie has chosen to dedicate all of her time to raising their 3 young children. Luckily, Jasper earns a monthly after-tax income of $25,000 working as a family doctor in the local clinic. Jasper meets with his insurance agent Odda to purchase a life insurance policy that will ensure his family will be able to continue to enjoy their current lifestyle in the event of his death. If his average tax rate is 40% and the investment return is 4%, how much life insurance should Jasper purchase based on the income replacement approach?
Answer: C
Explanation:
The income replacement approach calculates the amount of life insurance needed to replace Jasper'safter-tax income for his dependents over a given period, accounting for an investment return. To maintain the family's current lifestyle, we need to determine the capital required to generate a monthly after-tax income of $25,000.
* Calculate the Annual Income Needed:Monthly income required: $25,000Annual income required:
$25,000 × 12 = $300,000
* Adjust for Tax:Since Jasper's income needs to be replaced at a pre-tax level with a tax rate of 40%, his gross income requirement is calculated as follows:
A close-up of a math Description automatically generated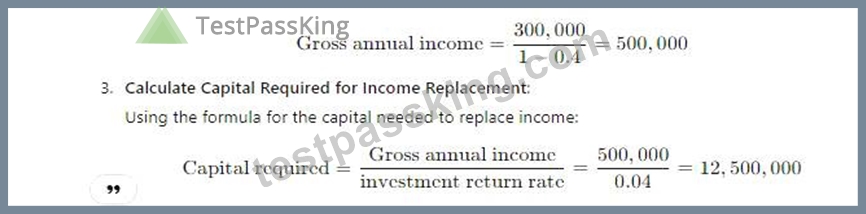
Thus, Jasper needs a life insurance policy worth$12,500,000to replace his income, allowing his family to maintain their lifestyle with a 4% investment return. This calculation aligns with LLQP principles, ensuring that the income replacement fully addresses both current lifestyle needs and tax implications.
NEW QUESTION # 129
......
Certification LLQP Test Questions: https://www.testpassking.com/LLQP-exam-testking-pass.html
BTW, DOWNLOAD part of TestPassKing LLQP dumps from Cloud Storage: https://drive.google.com/open?id=1utNhrQa1O1HH2dpE1kAXY5iola3MJLJO