P.S. Free 2026 IFSE Institute LLQP dumps are available on Google Drive shared by EduDump: https://drive.google.com/open?id=1meQMaYgB3t8kN_z7spQ1QgIWGHjZKnbj
Remember to fill in the correct mail address in order that it is easier for us to send our LLQP study guide to you, therefore, this personal message is particularly important. We are selling virtual products, and the order of our LLQP exam materials will be immediately automatically sent to each purchaser's mailbox according to our system. In the future, if the system updates, we will still automatically send the latest version of our LLQP learning questions to the buyer's mailbox.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
It has similar specifications to the IFSE Institute LLQP desktop-based practice exam software, but it requires an internet connection. Our IFSE Institute LLQP practice exam highlights mistakes at the end of each attempt, allowing you to overcome them before it's too late. This kind of approach is great for complete and flawless IFSE Institute LLQP Test Preparation.
NEW QUESTION # 188
Sandrine, CEO of her own company for over 15 years, regularly consults you about the defined benefit pension plan she set up four years ago. Her company is going through unexpected difficulties, and she would like to know under which circumstances an employer can terminate such a plan (she is fully aware that this could go against employees' expectations).
Which of the following answers are you most likely to give her?
Answer: B
Explanation:
According to the LLQP Group Savings and Pension Plans curriculum, a Defined Benefit Pension Plan (DBPP) represents a significant long-term obligation for an employer. In a DBPP, the employer guarantees a specific retirement benefit to employees, typically based on years of service and earnings. As a result, the employer bears the investment risk and funding responsibility. Because of this obligation, pension legislation places strict limits on when and how such a plan may be terminated.
The most clear-cut circumstance under which a defined benefit pension plan may be terminated is when the employer becomes insolvent or goes bankrupt. In this situation, the employer is no longer financially capable of maintaining the plan. Pension standards legislation recognizes that continuing the plan is no longer feasible, and the plan may be wound up. This is why Option C is correct. Even in bankruptcy, however, employee pension rights are protected to the extent possible, and pension assets must be distributed according to legislated priorities.
Options A and B are incorrect because business growth-whether faster company growth or a rapid increase in plan membership-does not justify terminating a DBPP. In fact, growth often strengthens a company's ability to support pension obligations rather than undermining it. Pension plans are designed to accommodate changes in workforce size and business expansion.
Option D is also incorrect. When a company is sold to another employer with an identical or comparable pension plan, pension legislation generally allows the plan to be continued or transferred, rather than terminated. The intent of pension regulation is to preserve employees' accrued benefits, not eliminate them due to corporate restructuring.
The LLQP curriculum emphasizes that DBPPs are highly regulated precisely because employees rely on them for retirement security. Termination is therefore permitted only in exceptional circumstances, with employer insolvency being the most definitive example.
Accordingly, the most accurate and LLQP-compliant answer is Option C.
NEW QUESTION # 189
Vincent, aged 55, plans to retire 10 years from now after a 40-year career with the federal government. He will then receive a federal pension and will benefit from a retiree health plan. His wife Catherine is 15 years younger than him. Vincent also has an RRSP that he intends on using in part to fund his travel plans in retirement, and in part to leave a lump sum to Catherine for her living expenses after he dies. Vincent has planned his budget carefully and feels confident that he has thought of everything. What may Vincent's insurance agent suggest he consider to safeguard his retirement?
Answer: D
Explanation:
Comprehensive and Detailed Explanation:
Vincent's pension and health plan cover income and basic health needs. LTC insurance protects his RRSP from depletion due to care costs, ensuring funds for travel and Catherine's inheritance (Chapter 4:Insurance to Protect Savings).
Option A: Unnecessary; retiree health likely covers medications.
Option B: Correct; LTC preserves savings.
Option C: Redundant; retiree plan covers hospital stays.
Option D: Irrelevant; he's retiring, not working.
Reference: LLQP Accident and Sickness Insurance Manual, Chapter 4:Insurance to Protect Savings.
NEW QUESTION # 190
Jasper is the sole breadwinner in his family. His wife Stephanie has chosen to dedicate all of her time to raising their 3 young children. Luckily, Jasper earns a monthly after-tax income of $25,000 working as a family doctor in the local clinic. Jasper meets with his insurance agent Odda to purchase a life insurance policy that will ensure his family will be able to continue toenjoy their current lifestyle in the event of his death. If his average tax rate is 40% and the investment return is 4%, how much life insurance should Jasper purchase based on the income replacement approach?
Answer: D
Explanation:
The income replacement approach calculates the amount of life insurance needed to replace Jasper'safter-tax income for his dependents over a given period, accounting for an investment return. To maintain the family's current lifestyle, we need to determine the capital required to generate a monthly after-tax income of $25,000.
Calculate the Annual Income Needed:Monthly income required: $25,000Annual income required: $25,000 ×
12 = $300,000
Adjust for Tax:Since Jasper's income needs to be replaced at a pre-tax level with a tax rate of 40%, his gross income requirement is calculated as follows:
A close-up of a math Description automatically generated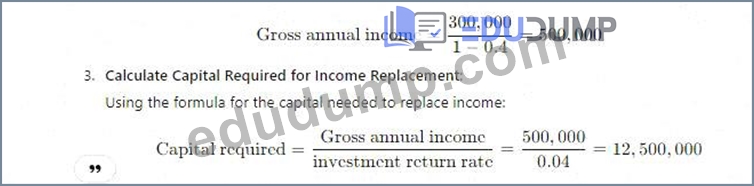
Thus, Jasper needs a life insurance policy worth$12,500,000to replace his income, allowing his family to maintain their lifestyle with a 4% investment return. This calculation aligns with LLQP principles, ensuring that the income replacement fully addresses both current lifestyle needs and tax implications.
NEW QUESTION # 191
Nathalie worked for 25 years as an administrative assistant at a manufacturing company. When she left the company 10 years ago, she transferred the money that she accumulated from the company's pension plan into a locked-in retirement account (LIRA). Now she is 60 years of age and would like to withdraw the money from the LIRA.
Under which of the following circumstances would Nathalie be allowed to withdraw her funds?
Answer: D
Explanation:
Locked-In Retirement Accounts (LIRAs) are subject to specific restrictions regarding when and how funds can be accessed. Under LLQP regulations, individuals can generally only withdraw funds from a LIRA before retirement under certain circumstances. These include:
* Disability and a reduced life expectancy, as defined by the plan's requirements, which allow for early withdrawal due to significant financial or health hardships.
In contrast:
* Moving to another country, such as Arizona, does not qualify as a reason for early withdrawal under Canadian pension regulations.
* Retirement alone, without converting the LIRA into a Life Income Fund (LIF) or similar product, does not directly permit withdrawals from the LIRA.
* Collecting QPP benefits does not impact the withdrawal conditions of a LIRA directly unless combined with an allowable reason such as disability with reduced life expectancy.
Thus, option B correctly reflects the LLQP criteria under which Nathalie may access her LIRA funds early due to disability and a shortened life expectancy.
NEW QUESTION # 192
Ontario residents, Juan and Maria, are a married couple approaching retirement. They have asked their representative, Carlow, to review the details of Maria's defined benefit plan (DBPP).
Which of the following statements about Maria's pension is CORRECT?
Answer: A
Explanation:
In Ontario, the pension legislation stipulates that a spouse is entitled to receive a minimum of 50% of the member's pension benefits as a survivor benefit if the member dies. This applies to defined benefit pension plans (DBPP), which provide a predetermined benefit upon retirement. Therefore, as the spouse of Maria, Juan would be entitled to receive at least half of Maria's pension upon her death, as specified by Ontario pension regulations. This survivor benefit is a guaranteed right and requires consent from both spouses for any reduction or waiver. Options C and D are incorrect as Ontario law mandates a minimum 50% survivor benefit without provision for reduction to 25%, and Juan's entitlement is tied to their marital status and statutory rights, which may not apply if they are separated or divorced at the time of Maria's death. Option A is incorrect because Ontario legislation does not provide for an increased benefit by waiving the survivor benefit.
NEW QUESTION # 193
......
EduDump releases a new high pass-rate LLQP valid exam preparation recently. If you are still puzzled by your test you can set your heart at rest to purchase our valid exam materials which will assist you to clear exam easily. We can guarantee purchasing IFSE Institute LLQP Valid Exam Preparation will be the best passing methods and it always help you pass exam at first attempt. Now it is really an opportunity. Stop waiting and hesitate again!
LLQP Valid Exam Dumps: https://www.edudump.com/exams/IFSE-Institute/LLQP/
DOWNLOAD the newest EduDump LLQP PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1meQMaYgB3t8kN_z7spQ1QgIWGHjZKnbj