BONUS!!! Download part of PDFBraindumps CSC2 dumps for free: https://drive.google.com/open?id=1RGlEdEyNMXhSIN4OED7Q31au2O5T9bjD
Our PDFBraindumps offers you the high-quality CSC2 exam dumps and answers, and make you be closer to success. If you are still worried, you can download CSC2 exam dumps' free demo and answers on probation on PDFBraindumps.COM. We promise, when you purchase CSC2 Exam Dumps and answers, we will also provide one year free renewal service for you.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Corporate Finance | 20% | - Capital Structure and Dividend Policy - Capital Budgeting - Mergers, Acquisitions, and Corporate Restructuring - Working Capital Management |
| Topic 2: Fixed Income Securities | 20% | - Risks of Fixed Income Investments - Government Bonds and Money Market Securities - Corporate Bonds - Bond Pricing and Yield Measures |
| Topic 3: Portfolio Management | 20% | - Portfolio Concepts and Risk/Return - Managed Products - Performance Measurement - Portfolio Planning and Construction |
| Topic 4: Derivative Securities | 20% | - Option Contracts - Swaps - Futures Contracts - Forward Contracts |
| Topic 5: Analysis of Equity Securities | 20% | - Valuation Methods - Growth and Defensive Stocks - Financial Statement Analysis - Industry Analysis |
As our Canadian Securities Course Exam2 study questions can bring more professional quality service for the user. Our CSC2 study materials can give the user confidence and strongly rely on feeling, lets the user in the reference appendix not alone on the road, because we are to accompany the examinee on CSC2 Exam, candidates need to not only learning content of teaching, but also share his arduous difficult helper, so believe us, we are so professional company. Now, you can free download the demo of our CSC2 test guide to understand in more details.
NEW QUESTION # 39
Which type of ETF is also referred to as smart beta ETF?
Answer: A
Explanation:
Rules-based ETFs, also known as smart beta ETFs, use predetermined rules or algorithms to select and weight securities in their portfolios. These ETFs aim to outperform traditional market-capitalization-weighted ETFs by targeting specific factors such as value, momentum, quality, or volatility.
* Strategic Factor Weighting: Securities are weighted based on fundamental or quantitative factors, not just market capitalization.
* Higher Returns Potential: These ETFs are designed to capture excess returns (alpha) relative to a benchmark.
* Lower Costs: Smart beta strategies often combine active and passive management elements at a lower cost than traditional active funds.
* A. Rules-based: Correct answer. Smart beta ETFs are built on rule-based frameworks designed to achieve specific investment objectives.
* B. Standard: Refers to traditional, market-cap-weighted ETFs, not smart beta.
* C. Synthetic: Refers to ETFs that use derivatives to replicate returns of an underlying index, unrelated to smart beta.
* D. Index-based: Includes standard ETFs tracking an index but does not apply specifically to smart beta.
References:
CSC Volume 2, Chapter 19: Smart Beta and Rules-Based ETFs, which describes their unique features, benefits, and strategies.
NEW QUESTION # 40
A portfolio manager at an investment firm is analyzing the behavior of stocks in various market conditions.
They believe markets are efficient and that all public and non-public and non-public available information is fully reflected in current process. How should the construct their investment portfolio?
Answer: A
Explanation:
When an investor or portfolio manager adheres to the belief in market efficiency-specifically the strong form of the Efficient Market Hypothesis (EMH)-it implies that all information (public and non-public) is fully reflected in security prices. This belief diminishes the value of active investment strategies, such as fundamental or technical analysis, as these approaches presume the possibility of identifying undervalued or overvalued securities.
As such, the logical approach in this scenario would be to adopt a passive investment strategy. This includes constructing a portfolio of exchange-traded funds (ETFs) or index funds that replicate the performance of a broad market index, such as the S&P/TSX Composite Index. A passive approach aligns with the principle of market efficiency, as it avoids attempts to outperform the market, which are considered futile under the EMH.
:
Volume 2, Chapter 13: Fundamental and Technical Analysis, Efficient Market Hypothesis, Canadian Securities Course.
NEW QUESTION # 41
An advisor wants to explain the benefits of labour sponsored funds (LSVCC) to some of his clients. With which client should the advisor have this discussion?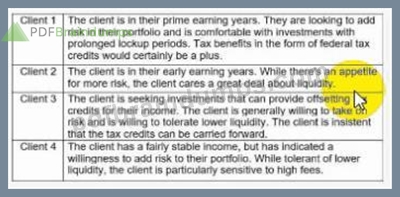
Answer: D
NEW QUESTION # 42
Franco purchased an ETF in his non-registered account, and his total adjusted cost base in year 1 was
$30,000. The ETF distributes income each year. And this reinvested distribution total was $1,750. The ETF also distributes a return of capital of $850. What would Franco's total capital gain be if the sold the ETF for
$39,000?
Answer: D
Explanation:
To calculate Franco's total capital gain, we adjust the adjusted cost base (ACB) for reinvested distributions and return of capital (ROC).
* Initial ACB: $30,000.
* Add Reinvested Distributions: Reinvested distributions increase the ACB. 30,000+1,750=31,75030,000
+ 1,750 = 31,750 30 , 000 + 1 , 750 = 31 , 750
* Subtract Return of Capital: ROC reduces the ACB. 31,750#850=30,90031,750 - 850 = 30,900 31 , 750
# 850 = 30 , 900
* Calculate the Capital Gain: Subtract the adjusted ACB from the sale price. 39,000#30,900=8,10039,000
- 30,900 = 8,100 39 , 000 # 30 , 900 = 8 , 100
* A. $1,250: Incorrect, likely a miscalculation of adjusted ACB.
* B. $8,100: Correct, based on accurate ACB adjustments and sale price.
* C. $6,400: Incorrect, ignores reinvested distributions.
* D. $9,000: Incorrect, ignores the impact of ROC adjustments on ACB.
References:
CSC Volume 2, Chapter 19: Adjusted Cost Base Calculations, which explains the impact of reinvested distributions and ROC on capital gains.
NEW QUESTION # 43
Which factor would deter an investor from investing in a company's convertible preferred shares?
Answer: A
Explanation:
Convertible preferred shares combine preferred share income features with the option to convert into common shares. Their attractiveness depends heavily on the outlook for the issuer's common stock because the conversion privilege becomes valuable only if the common shares perform well. If the common stock outlook has been downgraded, the conversion feature becomes less attractive and the investor may be deterred from buying the convertible preferred shares. A long conversion privilege is generally positive because it gives the investor more time for the common shares to appreciate. A high preferred dividend coverage ratio is also favourable because it suggests stronger dividend protection.
Therefore, the downgraded common stock outlook is the best deterrent.
NEW QUESTION # 44
......
With the rise of internet and the advent of knowledge age, mastering knowledge about computer is of great importance. This CSC2 exam is your excellent chance to master more useful knowledge of it. Up to now, No one has questioned the quality of our CSC2 training materials, for their passing rate has reached up to 98 to 100 percent. If you make up your mind of our CSC2 Exam Questions after browsing the free demos, we will staunchly support your review and give you a comfortable and efficient purchase experience this time.
CSC2 Standard Answers: https://www.pdfbraindumps.com/CSC2_valid-braindumps.html
P.S. Free & New CSC2 dumps are available on Google Drive shared by PDFBraindumps: https://drive.google.com/open?id=1RGlEdEyNMXhSIN4OED7Q31au2O5T9bjD