We have chosen a large number of professionals to make AFP-Exam-1 learning question more professional, while allowing our study materials to keep up with the times. Of course, we do it all for you to get the information you want, and you can make faster progress. You can also get help from AFP-Exam-1 Exam Training professionals at any time. We can be sure that with the professional help of our AFP-Exam-1 test guide you will surely get a very good experience. Good materials and methods can help you to do more with less. Choose AFP-Exam-1 test guide to get you closer to success!
| Section | Weight | Objectives |
|---|---|---|
| Risk Management and Insurance | 12% | - Life Insurance - Risk Transfer Strategies - Risk Assessment - Disability and Health Insurance |
| Investment Planning | 17% | - Investment Products - Investment Theory - Portfolio Construction - Asset Allocation |
| Estate Planning | 13% | - Powers of Attorney - Trust and Beneficiary Planning - Wills - Estate Transfer Strategies |
| Professional Conduct and Regulatory Compliance | 10% | - Compliance Responsibilities - Regulatory Requirements - Ethics and Professional Standards |
| Client Relationship and Practice Management | 6% | - Communication and Advisory Process - Client Discovery - Practice Management |
| Asset and Liability Management | 11% | - Cash Flow Management - Personal Balance Sheet Analysis - Budgeting - Debt Management |
| Retirement Planning | 17% | - Pension Plans - Retirement Income Strategies - Retirement Needs Analysis - Registered Retirement Savings Plans |
| Tax Planning | 14% | - Tax Deductions and Credits - Tax-Efficient Strategies - Income Tax Fundamentals - Registered Plans |
>> Latest AFP-Exam-1 Cram Materials <<
There are three different versions of our CSI AFP-Exam-1 preparation prep including PDF, App and PC version. Each version has the suitable place and device for customers to learn anytime, anywhere. In order to give you a basic understanding of our various versions on our Applied Financial Planning Certification Exam 1 (AFP) AFP-Exam-1 Exam Questions, each version offers a free trial.
NEW QUESTION # 59
Alexis has an index-linked GIC with an adjusted cost base of $20,500. The GIC was issued one year ago, has four years remaining to maturity and provides her with 60% participation in the gains of the S & P/TSX 60 Index, based on the level of the Index at maturity or at redemption prior to maturity. The GIC has a 2% fee if redeemed in the first two years. Alexis notices that the S & P/TSX 60 Index is up 25% and she would like to redeem her GIC. She asked her financial planner if she redeems her GIC, how much she would receive upon redemption. What will her financial planner tell her?
Answer: D
Explanation:
The redemption calculation follows the participation formula and then applies the early redemption fee.
Alexis's adjusted cost base is $20,500. The S & P/TSX 60 is up 25%, and the GIC gives her 60% participation, so the credited gain is 15% of principal. That brings the value to $23,575 before charges.
Because the GIC is redeemed during the first two years, the 2% fee applies. Two percent of $23,575 is
$471.50, leaving approximately $23,104 after the fee. Option B ignores the participation cap and uses the full index gain. Option D calculates the participation gain but ignores the redemption charge. Option A ignores the positive index-linked value. This question tests structured-product mechanics: index participation does not equal full market exposure, and liquidity before maturity may carry explicit cost. Study Guide focus: index- linked GICs, participation rates, early redemption fees, ACB, and investment liquidity. The adviser should also explain that index-linked guarantees protect principal differently from direct equity ownership.
NEW QUESTION # 60
What information is least important for Harry as a financial planner in his assessment for insurance coverage for his client with respect to estate planning purposes?
Answer: B
Explanation:
Estate insurance analysis focuses on amounts that create liquidity needs at death. Age affects underwriting, premium cost, and life expectancy assumptions. Income may indicate lifestyle replacement needs, support obligations, or survivor dependency. The fair market value of a non-principal residence is directly relevant because accrued capital gains may create a tax liability on deemed disposition at death. Work location, by contrast, has little bearing on estate liquidity unless the scenario adds an occupational risk or employer benefit issue, which it does not. The planner should gather asset values, ownership form, liabilities, beneficiary designations, tax exposure, family obligations, and existing insurance before recommending coverage. In this question, option B is least important because it does not help calculate probate exposure, final tax, debt repayment, or survivor capital requirements. Study Guide focus: estate liquidity, deemed disposition, life insurance needs analysis, taxable assets, and client data collection. The file should therefore emphasize estate value, tax exposure, liquidity, and beneficiary obligations rather than workplace geography.
NEW QUESTION # 61
James is visiting Gurjeet, his financial planner, to discuss his financial affairs after the recent passing of his long-time partner Peter. James is concerned that the cost of probate will be a heavy burden. Which holdings should Gurjeet advise James are included in calculating the cost of probate?
Answer: C
Explanation:
Probate is generally calculated on assets that form part of the deceased's estate. A tenancy in common interest is owned by the deceased as a separate property interest and does not pass automatically to the other owner by survivorship. It is therefore included in the estate unless another legal arrangement applies. Insurance contracts with a preferred or named beneficiary usually pay directly to the beneficiary. Assets held in a formal irrevocable trust are owned by the trust, not personally by the deceased. Registered plans with a valid adult child beneficiary designation generally bypass the estate, although tax consequences may still arise on the deceased's terminal return. Gurjeet should distinguish probate inclusion from income tax inclusion; an asset may bypass probate and still create tax. For the probate-cost question, the tenancy in common holding is the correct inclusion. Study Guide focus: probate property, beneficiary designations, trusts, joint ownership, and estate administration.
NEW QUESTION # 62
Janet's non-registered account holds the funds listed in the following table: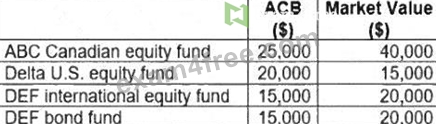
Assuming a marginal tax rate of 45%, what amount of tax payable will Janet incur if she redeems the account to fund the purchase of a new business?
Answer: D
Explanation:
Janet's taxable result comes from the net realized capital gain, not from the total market value redeemed. The ABC Canadian equity fund has a $15,000 gain, the Delta U.S. equity fund has a $5,000 loss, the DEF international equity fund has a $5,000 gain, and the DEF bond fund has a $5,000 gain. Net capital gains are therefore $20,000 after offsetting the Delta loss. Only one-half of the net capital gain is taxable under the standard capital gains inclusion treatment used in AFP-level calculations, producing a $10,000 taxable capital gain. At a 45% marginal tax rate, the tax payable is $4,500. Option A taxes the full net gain; option C and option D reflect incorrect inclusion or arithmetic assumptions. The purpose of the question is to test disposition analysis in a non-registered account and the sequence of gain/loss netting before applying the marginal rate. Study Guide focus: adjusted cost base, fair market value, capital gains inclusion, and non- registered tax planning.
NEW QUESTION # 63
How should Jenny, a financial planner, explain the benefits of a fee for service method of compensation to a prospective client?
Answer: D
Explanation:
A fee-for-service model reduces the incentive to recommend one product over another because compensation is not driven by product commission. The planner is paid for advice, planning work, or an agreed service arrangement rather than the compensation embedded in a product sale. This does not guarantee perfect objectivity, but it directly addresses product-compensation bias and makes remuneration more transparent.
Option A is not the benefit; charging more because products are complex can create its own conflict if not disclosed. Option B describes performance-based compensation, not fee-for-service financial planning.
Option C is imprecise because compensation is not objectively determined by the quality of the financial plan; it is determined by the fee arrangement. Jenny should explain the model in terms of transparency, alignment, and reduced product-driven incentives. Study Guide focus: planner compensation, fee-for-service advice, conflicts of interest, disclosure, and client relationship management. The compensation discussion should occur before engagement so the client understands what is being paid and why.
NEW QUESTION # 64
......
In addition to the content updates, our system will also be updated for the AFP-Exam-1 training materials. If you have any opinions, you can tell us that our common goal is to create a product that users are satisfied with. After you start learning, I hope you can set a fixed time to check emails. If the content of the AFP-Exam-1 Practice Guide or system is updated, we will send updated information to your e-mail address. Of course, you can also consult our e-mail on the status of the product updates. I hope we can work together to make you better use AFP-Exam-1 simulating exam to pass the AFP-Exam-1 exam.
Latest AFP-Exam-1 Test Online: https://www.exam4free.com/AFP-Exam-1-valid-dumps.html