我們VCESoft CSI的AFP-Exam-1考試 的問題包含了完整的無限制的轉儲,所以你很容易的通過考試,不管你是通過你的產品合格證或是其他當今流行的身份驗證,完美的展現VCESoft CSI的AFP-Exam-1考試培訓資料的長處,這不僅僅是依靠,也是指導,這其實是最好的,你可以使用VCESoft CSI的AFP-Exam-1考試 培訓資料裏的問題和答案通過考試,獲得CSI的AFP-Exam-1考試認證。
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Asset and Liability Management | 11% | - Budgeting - Personal Balance Sheet Analysis - Cash Flow Management - Debt Management |
| Topic 2: Risk Management and Insurance | 12% | - Risk Transfer Strategies - Disability and Health Insurance - Risk Assessment - Life Insurance |
| Topic 3: Professional Conduct and Regulatory Compliance | 10% | - Compliance Responsibilities - Ethics and Professional Standards - Regulatory Requirements |
| Topic 4: Retirement Planning | 17% | - Retirement Income Strategies - Retirement Needs Analysis - Pension Plans - Registered Retirement Savings Plans |
| Topic 5: Investment Planning | 17% | - Asset Allocation - Portfolio Construction - Investment Products - Investment Theory |
| Topic 6: Client Relationship and Practice Management | 6% | - Client Discovery - Communication and Advisory Process - Practice Management |
| Topic 7: Estate Planning | 13% | - Estate Transfer Strategies - Trust and Beneficiary Planning - Powers of Attorney - Wills |
| Topic 8: Tax Planning | 14% | - Tax-Efficient Strategies - Tax Deductions and Credits - Registered Plans - Income Tax Fundamentals |
CSI的AFP-Exam-1考試認證,VCESoft是當前最新CSI的AFP-Exam-1考試認證和考題準備問題提供認證的候選人中的佼佼者,我們資源不斷被修訂和更新,具有緊密的相關性和緊密性,今天你準備CSI的AFP-Exam-1認證,你將要選擇你要開始的訓練,而且要通過你下一次的考題,由於我們大部分考題是每月更新一次,你將得到最好的資源與市場的新鮮品質和可靠性的保證。
問題 #88
Sheeba is a financial planner and meeting with Ivana, a new client. She explains that part of her process is to recommend products and services, but prior to doing so, she will closely investigate the options to ensure they match up with Ivana's goals. Which professional responsibility has Sheeba demonstrated to Ivana?
答案:A
解題說明:
Sheeba is demonstrating diligence. Diligence requires a planner to make reasonable inquiries, investigate relevant facts, compare available options, and ensure recommendations are supported by competent analysis.
She tells Ivana that products and services will be closely investigated before they are recommended, which is exactly the conduct expected before implementation. Objectivity concerns unbiased judgment and avoiding undue influence; it may also be relevant, but the scenario specifically emphasizes investigation. Integrity relates to honesty and moral soundness, while professionalism describes broader conduct and respect for standards. AFP professional responsibility expects planners to avoid superficial product selection and to base recommendations on the client's goals, constraints, risk profile, and the characteristics of the available solutions. Sheeba's statement shows that she will exercise care before recommending products. Study Guide focus: professional responsibility, diligence, suitability review, product analysis, and client-first planning. In a compliance review, the file should show what research was performed and why the recommended solution was selected.
問題 #89
Lex's client, Phillip, has signed an agreement to purchase his uncle's business when his uncle retires in five years for $210,000. Phillip has $175,000 today, how should Lex recommend Philip invest his money?
答案:C
解題說明:
Phillip has a defined liability: $210,000 due in five years. His current capital of $175,000 must compound to the purchase price with minimal uncertainty. A five-year bond yielding 3.75% produces approximately
$210,400 at maturity if held as planned, which aligns the investment term with the obligation and slightly exceeds the required amount. A 3.00% savings account and a 3.50% GIC fall short of the target. An equity mutual fund may have averaged 6.00% historically, but historical average return is not a guarantee and is inappropriate for a fixed five-year contractual obligation where the required amount is known. The AFP rule is that known future liabilities should be matched with suitable maturity, capital certainty, and sufficient expected accumulation. Lex should avoid unnecessary market risk when a fixed-income option already satisfies the goal. Study Guide focus: goal-based investing, time horizon, fixed-income matching, future value, and suitability. The planner should document the maturity date and reinvestment risk because the purchase obligation is contractual, not discretionary.
問題 #90
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: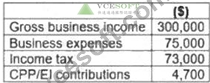
What is Terry's net business income?
答案:B
解題說明:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
問題 #91
Sapphire, age 35, a recent widow, is still in the grieving stage. She has just received a large insurance payout.
She has limited savings, a long-term time horizon, and a high tolerance for risk. What investment strategy should her financial planner recommend until Sapphire is better able to understand her new situation?
答案:B
解題說明:
Sapphire's technical risk tolerance is not the only planning factor. She is recently widowed, grieving, inexperienced in her new financial position, and has received a large insurance payout. A planner should avoid pushing her into a moderate or high-risk portfolio before she can make stable, informed decisions about goals, income needs, debts, taxes, and estate intentions. A high-interest savings account preserves capital, maintains liquidity, and buys time for the planning process. A ladder of GICs may eventually be suitable, but traditional and index-linked GICs still lock in terms or introduce product features she may not yet understand.
A high-risk portfolio would be especially inappropriate during the immediate transition period. The temporary recommendation is not a long-term asset-allocation decision; it is a prudent holding strategy until discovery and emotional readiness improve. Study Guide focus: major life events, client vulnerability, liquidity, temporary cash management, and suitability. This temporary parking approach is common after bereavement, divorce, inheritance, or business sale proceeds.
問題 #92
Keitaro, age 42, and Ruth, age 52, are married and have two children - Maximo, age 20, and Hannah, age 16, both from Keitaro's previous marriage. In the event Keitaro dies, he would like to minimize taxes, provide for Ruth for the remainder of her life, and then after her death leave the residual to his children. What estate planning strategy should his financial planner recommend to help Keitaro achieve his goal?
答案:D
解題說明:
A testamentary spousal trust is the best strategy for Keitaro's blended-family objective. It can provide Ruth with income for life, defer tax on assets transferred at death to a qualifying spouse or spousal trust, and preserve the remaining capital for Maximo and Hannah after Ruth's death. The trust is created through Keitaro's will, so it is testamentary, not inter vivos. The children should be capital beneficiaries, not income beneficiaries during Ruth's lifetime, because the goal is to provide for Ruth first and leave the residual to the children later. Naming the children as income and capital beneficiaries while Ruth is alive would undermine the spousal-trust rollover requirements and the planning objective. The planner should refer Keitaro to an estate lawyer to draft the trust terms precisely. Study Guide focus: testamentary spousal trusts, blended-family planning, spousal rollover, income beneficiary, and capital remainder. The will should also address trustee powers, encroachment rights, tax filings, and the treatment of registered assets.
問題 #93
......
很多IT人士都想通過CSI AFP-Exam-1 認證考試,從而在IT行業中獲取更好的提升機會,使他們的工資生活水準都有所提升。但是好多人為了通過CSI AFP-Exam-1 認證考試花了大量時間和精力來鞏固相關知識卻沒有通過考試。這樣是很不划算。如果你選擇VCESoft的產品,你可以為你節約很多時間和精力來鞏固知識,但是卻可以通過CSI AFP-Exam-1 認證考試。因為VCESoft的關於CSI AFP-Exam-1 認證考試的針對性的資料可以幫助你100%通過考試。如果你考試失敗,VCESoft會全額退款給你。
AFP-Exam-1認證考試解析: https://www.vcesoft.com/AFP-Exam-1-pdf.html