BTW, DOWNLOAD part of PracticeTorrent PF1 dumps from Cloud Storage: https://drive.google.com/open?id=1hBwJQyqBFT2OBe8Z5lNIGoBduGmTFiFP
It is quite clear that most candidates are at their first try, therefore, in order to let you have a general idea about our PF1 test engine, we have prepared the free demo in our website. The contents in our free demo are part of the real materials in our PF1 study engine. Just like the old saying goes "True blue will never strain" You are really welcomed to download the free demo in our website to have the firsthand experience, and then you will find out the unique charm of our PF1 Actual Exam by yourself.
| Section | Objectives |
|---|---|
| Topic 1: Provincial Remittances | - Provincial payroll requirements
|
| Topic 2: Non-Statutory Deductions | - Voluntary deductions
|
| Topic 3: Workers’ Compensation | - Workers compensation administration
|
| Topic 4: Year-End Processing | - Federal and provincial year-end reporting
|
| Topic 5: Termination of Employment | - Termination processing
|
| Topic 6: Federal Remittances | - Government remittance obligations
|
| Topic 7: Record of Employment | - ROE processing
|
| Topic 8: New Employee Information | - Employee setup and documentation
|
| Topic 9: Employment Income – Regular Earnings | - Regular payroll calculations
|
| Topic 10: Commission Payments | - Commission payroll processing
|
| Topic 11: Payroll Accounting | - Payroll accounting practices
|
| Topic 12: Non-Regular Payments | - Special payroll payments
|
| Topic 13: Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
>> Reliable National Payroll Institute PF1 Dumps Sheet <<
Our product is of high quality and boosts high passing rate and hit rate. Our passing rate is 98%-100% and our PF1 test prep can guarantee that you can pass the exam easily and successfully. Our PF1 exam materials are highly efficient and useful and can help you pass the exam in a short time and save your time and energy. It is worthy for you to buy our PF1 Quiz torrent and you can trust our product. You needn’t worry that our product can’t help you pass the exam and waste your money.
NEW QUESTION # 27
Which of the following is not correct?
Answer: D
Explanation:
Option A is not correct. Service Canada's ROE guidance for paper ROEs explains that if you need to complete Block 15C, you do that first, and then you still enter the total insurable earnings in Block 15B. It also reminds employers to include any insurable separation payments entered in Block 17 in both Block 15C (Pay Period 1) and Block 15B totals.
Option C is correct because retiring allowances (often treated as severance-type amounts) are not insurable, so even if they appear in Block 17C, they are not added to Blocks 15B/15C.
Option D is correct because vacation pay paid on separation is reported in Block 17A, and when it is insurable, it must be included in the insurable earnings totals in Block 15B (and Block 15C P.P.1 where applicable).
NEW QUESTION # 28
The Canada Revenue Agency form that is completed to allow a commissioned employee to claim non- reimbursed expenses at source is a:
Answer: B
Explanation:
The CRA form used to adjust payroll income tax withholdings at source for employees who earn commission income and have commission expenses is Form TD1X - Statement of Commission Income and Expenses for Payroll Tax Deductions. The CRA explains that an employee completes TD1X if they receive commission income (or salary plus commission) and want the employer to adjust tax deductions to take commission expenses into account.
This is different from:
TD1, which is the Personal Tax Credits Return used to claim basic/personal credits and determine standard withholding (not commission-expense adjustments).
T777, which is used to claim employment expenses on the employee's personal tax return (not to reduce payroll withholding at source).
TP-1015.R.13.1-V, which is a Quebec form used to request a reduction of Quebec income tax withholding in specific situations (not the CRA commission-expense at-source form).
Operationally, payroll should keep the TD1X on file and apply it to income tax withholding calculations until the employee updates or replaces it.
NEW QUESTION # 29
Dollar values attributed to something the employer has either provided to an employee or paid for on an employee's behalf are:
Answer: C
Explanation:
The CRA defines a benefit as something the employee receives when the employer pays for or gives something that is personal in nature (a good or service), either directly to the employee or through a third party. CRA's T4130 guide describes a benefit as a good or service you give (or arrange for) such as free use of employer property, and it is the value of that benefit that may need to be included in the employee's income if taxable.
This matches the wording in the question: "dollar values attributed to something the employer has either provided...or paid for...on an employee's behalf." By contrast, earnings are pay for work performed (salary, wages, commissions). Allowances are fixed amounts paid to help cover anticipated expenses without receipts (often taxable unless an exception applies). Expense reimbursements repay actual business expenses (typically supported by receipts) and are generally not treated as earnings.
So the correct classification is Benefits.
NEW QUESTION # 30
Michael is an employee in Alberta who is paid bi-weekly and earns $1,600.00 per pay period. He has a taxable meal allowance of $30.00 per pay period. His federal and provincial TD1s on file show a claim code
2. Michael already reached the annual maximum first and second Canada Pension Plan (CPP) contributions before this pay. Calculate his total federal and provincial income taxes.
Answer:
Explanation:
(total federal + Alberta tax): $173.48
Explanation:
Taxable gross for the period = $1,600.00 + $30.00 = $1,630.00 (a taxable allowance is included in income for tax withholding).
Using CRA T4032-AB (Biweekly, 26 pay periods) with claim code 2:
Federal tax at pay $1,630 falls in the $1,619-$1,635 range # CC2 = $107.35.
Alberta provincial tax at pay $1,630 falls in the $1,628-$1,644 range # CC2 = $46.55.
Subtotal tax from the tables = $107.35 + $46.55 = $153.90.
CRA notes these tax tables build in the tax credits for CPP/EI, so when CPP is not deducted (because annual max already reached), you must increase tax withholding accordingly.
CPP that would have been deducted this pay (using CRA rates/YBE):
Pensionable = $1,630 # ($3,500/26 = $134.62) = $1,495.38; CPP (4.95% + 1.00% = 5.95%) = $88.98.
Add back missing credits: Federal 14% × 88.98 = $12.46; Alberta 8% × 88.98 = $7.12 # total $19.58.
Final total tax = $153.90 + $19.58 = $173.48.
NEW QUESTION # 31
National Hardware, an Ontario organization, will be terminating the employment of Emilie St. Germain on October 28, 2019, the last day of the pay period. Emilie started with National Hardware on September 19,
2007. Complete the paper Record of Employment (ROE) for Emilie based on the information provided in the following chart.
Note: Vacationable earnings already include the pay in lieu of notice.
All dates must be entered in the format DDMMYYYY.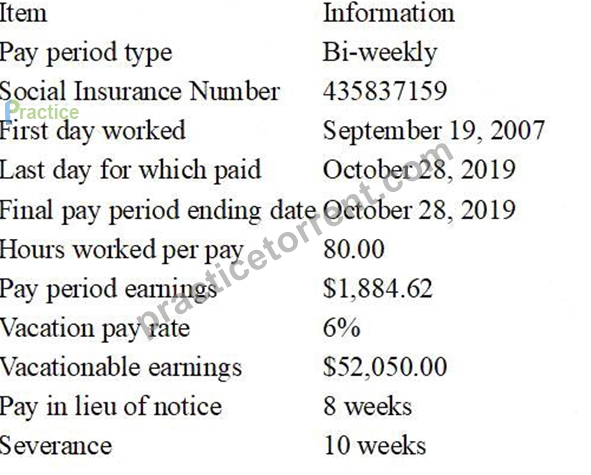
Paper ROE (Form Reference)
Complete the following paper ROE blocks for Emilie:
Block 6 - Pay period type
Block 8 - Social Insurance Number
Block 10 - First day worked
Block 11 - Last day for which paid
Block 12 - Final pay period ending date
Block 15A - Total insurable hours
Block 15B - Total insurable earnings
Block 17A - Vacation pay
Block 17C - Other monies (Pay in lieu of notice)
Block 17C - Other monies (Severance)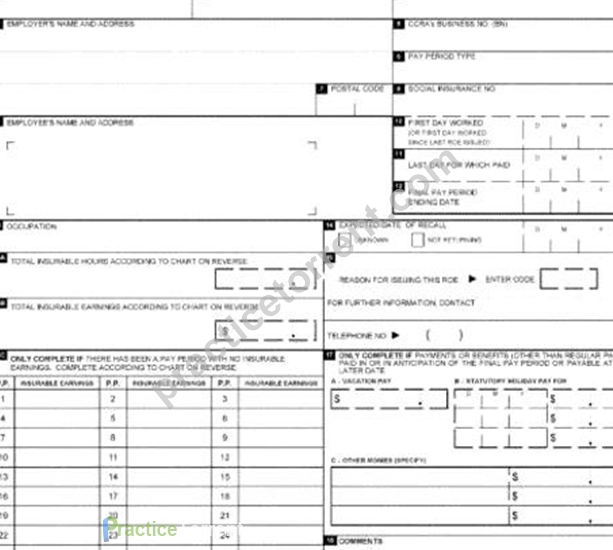
Step 1 - Complete Block 6
Enter the pay period type for Emilie.
Step 2 - Complete Block 8
Enter Emilie's Social Insurance Number.
Step 3 - Complete Block 10
Enter Emilie's first day worked in DDMMYYYY format.
Step 4 - Complete Block 11
Enter Emilie's last day for which paid in DDMMYYYY format.
Step 5 - Complete Block 12
Enter the final pay period ending date in DDMMYYYY format.
Step 6 - Complete Block 15A
Calculate and enter total insurable hours.
Given:
Hours worked per pay period = 80.00
Bi-weekly ROE pay period chart captures 27 pay periods
Step 7 - Complete Block 15B
Calculate and enter total insurable earnings.
Given:
Pay period earnings = $1,884.62
Bi-weekly ROE pay period chart captures 27 pay periods
Step 8 - Complete Block 17A
Calculate and enter vacation pay.
Given:
Vacation pay rate = 6%
Vacationable earnings = $52,050.00
(already includes pay in lieu of notice)
Step 9 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Pay in lieu of notice.
Given:
Pay in lieu of notice = 8 weeks
Use weekly earnings derived from the bi-weekly pay period earnings.
Step 10 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Severance.
Given:
Severance = 10 weeks
Use the same weekly earnings used in Step 9.
Answer:
Explanation:
See the Below Explanation for complete Solution.
Explanation:
Step 1 - Block 6
Bi-weekly
Step 2 - Block 8
435837159
Step 3 - Block 10
September 19, 2007 # 19092007
Step 4 - Block 11
October 28, 2019 # 28102019
Step 5 - Block 12
October 28, 2019 # 28102019
Step 6 - Block 15A (Total insurable hours)
80.00 × 27 = 2160
Block 15A = 2160
Step 7 - Block 15B (Total insurable earnings)
$1,884.62 × 27 = $50,884.74
Block 15B = 50,884.74
Step 8 - Block 17A (Vacation pay)
$52,050.00 × 6% = $3,123.00
Block 17A = 3,123.00
Step 9 - Block 17C (Pay in lieu of notice)
Weekly earnings = $1,884.62 ÷ 2 = $942.31
Pay in lieu = $942.31 × 8 = $7,538.48
Block 17C (Pay in lieu of notice) = 7,538.48
Step 10 - Block 17C (Severance)
Severance = $942.31 × 10 = $9,423.10
Block 17C (Severance) = 9,423.10
NEW QUESTION # 32
......
We strongly recommend using our Payroll Fundamentals 1Exam (PF1) exam dumps to prepare for the National Payroll Institute PF1 certification. It is the best way to ensure success. With our National Payroll InstitutePF1 practice questions, you can get the most out of your studying and maximize your chances of passing your National Payroll Institute PF1 Exam. PracticeTorrent National Payroll Institute PF1 practice test PracticeTorrent is the answer if you want to score higher in the PF1 exam and achieve your academic goals.
Latest PF1 Exam Book: https://www.practicetorrent.com/PF1-practice-exam-torrent.html
DOWNLOAD the newest PracticeTorrent PF1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1hBwJQyqBFT2OBe8Z5lNIGoBduGmTFiFP