P.S. Free 2026 CSI AFP-Exam-1 dumps are available on Google Drive shared by Real4Prep: https://drive.google.com/open?id=1VdqMrQPiE1D_prUbg8evM6MjVzPFjWB-
The AFP-Exam-1 test material, in order to enhance the scientific nature of the learning platform, specifically hired a large number of qualification exam experts, composed of product high IQ team, these experts by combining his many years teaching experience of AFP-Exam-1 quiz guide and research achievements in the field of the test, to exam the popularization was very complicated content of Applied Financial Planning Certification Exam 1 (AFP) exam dumps. Expert team can provide the high quality for the AFP-Exam-1 Quiz guide consulting for you to pass the AFP-Exam-1 exam.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Technical Competencies | 84% | - Tax Planning - Retirement Planning - Estate Planning - Investment Planning - Risk Management and Insurance - Asset and Liability Management |
| Topic 2: Enabling Competencies | 16% | - Client Relationship and Practice Management - Professional Conduct and Regulatory Compliance |
>> AFP-Exam-1 Pass4sure Pass Guide <<
All customer information to purchase our AFP-Exam-1 guide torrent is confidential to outsides. You needn’t worry about your privacy information leaked by our company. People who can contact with your name, e-mail, telephone number are all members of the internal corporate. The privacy information provided by you only can be used in online support services and providing professional staff remote assistance. Our experts check whether there is an update on the Applied Financial Planning Certification Exam 1 (AFP) exam questions every day, if an update system is sent to the customer automatically. If you have any question about our AFP-Exam-1 Test Guide, you can email or contact us online.
NEW QUESTION # 29
Harley is a novice investor who has just set up his first FHSA. He has a high-risk tolerance to market volatility and his primary investment objective is growth. He would like to invest $10,000 and will use the funds as part of the first-time home buyers plan within the next year. What investment should Harley purchase within this FHSA?
Answer: B
Explanation:
Harley's stated risk tolerance is not the controlling fact. The decisive constraint is time horizon: he intends to use the FHSA money within the next year for a first home purchase. When a required withdrawal is near, capital preservation and liquidity outrank long-term growth. A high-interest savings account is therefore the appropriate holding because it keeps the funds accessible and avoids exposing the down payment to equity market volatility. A locked-in one-year GIC may preserve capital, but it can create liquidity problems if the home purchase occurs before maturity. Equity-focused and income-focused mutual funds can fluctuate in value and may be unsuitable for funds earmarked for a near-term transaction. In AFP investment planning, risk capacity can be low even when risk tolerance is high; the client cannot afford a market loss shortly before the purchase. Study Guide focus: FHSA funding, investment time horizon, liquidity, risk capacity, and short- term goal funding.
NEW QUESTION # 30
Evan meets with his financial planner to review his concerns around inflation and its impact on his TFSA investment portfolio. His financial planner researches the current holdings and recommends that he sells one of the portfolio's equity funds. Which replacement option should the financial planner recommend to Evan?
Answer: C
Explanation:
The inflation concern directs the planner toward assets that may respond positively to rising prices. Real estate investment trusts hold income-producing property, and rents or property values may adjust over time as inflation affects replacement cost and lease rates. That does not make REITs risk-free, but they are more directly inflation-sensitive than nominal guaranteed products. GICs and treasury bills preserve nominal capital but may lose purchasing power after inflation and tax. Gold bullion may be used as a speculative inflation hedge, but it produces no income and can be volatile; it is not the best replacement for an equity fund within a diversified TFSA portfolio unless the mandate specifically permits that exposure. The planner should recommend an inflation-aware asset that remains investment-oriented and diversified. AFP investment planning treats inflation as purchasing-power risk, not simply price volatility. Study Guide focus: inflation risk, real assets, REITs, TFSA investment selection, and portfolio construction.
NEW QUESTION # 31
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: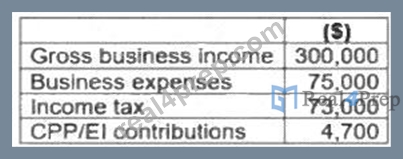
What is Terry's net business income?
Answer: D
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 32
Ivan relocates for a new job and wants to know whether his move may qualify for the work-related moving expense deduction. What minimum distance test is generally relevant?
Answer: D
Explanation:
The standard Canadian moving-expense test requires the new residence to be at least 40 kilometres closer to the new work or business location than the old residence was. Option D states the relevant threshold. Options A, B, and C understate the distance requirement. In a planning context, the distance test is only the starting point. The planner should also consider whether the move relates to eligible employment or business income, whether expenses are reasonable and properly documented, whether reimbursement was received from an employer, and whether expenses are deductible only against income from the new work location. The deduction can matter when clients change jobs, relocate for self-employment, or move for post-secondary attendance in specific circumstances. The key exam distinction is that the rule is not based on the total distance moved; it compares how much closer the new home is to the new workplace. References/topics:
moving expenses, employment relocation, tax deductions, distance test.
NEW QUESTION # 33
A client borrows $100,000 to invest in a non-registered portfolio expected to generate interest and dividend income. What tax principle is most relevant?
Answer: A
Explanation:
Interest deductibility depends on purpose and traceability. If borrowed money is used for the purpose of earning income from a business or property, interest may be deductible, provided the legal requirements are met and the borrowing can be traced to the income-producing investment. Option B is false because individuals may deduct interest in qualifying leveraged investment arrangements. Option C is wrong because leverage does not change the tax character of investment income; interest, dividends, and capital gains remain taxable according to normal rules. Option D is incorrect because borrowing to contribute to a TFSA generally does not create deductible interest, since TFSA income is not taxable. A planner should not treat deductibility as the only issue. Leverage increases downside risk, magnifies losses, creates cash flow obligations, and may be unsuitable for clients with low risk capacity. Documentation, account segregation, investment mandate, and repayment ability are essential. References/topics: interest deductibility, leveraged investing, taxable income, suitability.
NEW QUESTION # 34
......
Most IT workers prefer to choose our online test engine for their AFP-Exam-1 exam prep because online version is more flexible and convenient. With the help of our online version, you can not only practice our AFP-Exam-1 Exam PDF in any electronic equipment, but also make you feel the atmosphere of AFP-Exam-1 actual test. The exam simulation will mark your mistakes and help you play well in AFP-Exam-1 practice test.
Reliable AFP-Exam-1 Braindumps Free: https://www.real4prep.com/AFP-Exam-1-exam.html
DOWNLOAD the newest Real4Prep AFP-Exam-1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1VdqMrQPiE1D_prUbg8evM6MjVzPFjWB-