Außerdem sind jetzt einige Teile dieser ExamFragen PF1 Prüfungsfragen kostenlos erhältlich: https://drive.google.com/open?id=1h6uoGsa4AdLM4i6I9S0HnAhPlAMqBR4w
Wenn Sie ein Pendler sind, wenn Sie die National Payroll Institute PF1 Prüfung so schnell wie möglich bestehen möchten, dass ist ExamFragen Ihre beste Wahl. Unser ExamFragen bietet Ihnen die Testfragen und Antworten von National Payroll Institute PF1, die von den IT-Experten durch Experimente und Praxis erhalten werden und über IT-Zertifizierungserfahrungen über 10 Jahre verfügt. Mit ExamFragen können Sie nicht nur Zeit sparen, sondern auch die National Payroll Institute PF1 Zertifizierungsprüfung leicht und züglich bestehen.
| Section | Weight | Objectives |
|---|---|---|
| Communication and Compliance | 10% | - Accuracy and documentation
|
| Individual Pay Calculations | 40% | - Non-regular earnings
|
| Termination and Special Payments | 30% | - Leaves and absences
|
| Record of Employment (ROE) | 20% | - Submission and deadlines
|
Die Schulungsunterlagen zur National Payroll Institute PF1 Zertifizierungsprüfung von ExamFragen sind meistens in der Form von PDF und Software. Die IT-Fachleute und Experten nutzen Ihre Erfahrungen aus, um Ihnen die besten Produkte auf dem Markt bereitzustellen und Ihr Ziel zu erreichen.
49. Frage
Bonus and incentive pays are subject to which statutory deductions?
Antwort: D
Begründung:
Bonuses and incentives are treated as taxable remuneration, so they are generally subject to the same core statutory deductions as regular earnings: CPP/QPP, EI, and income tax (and in Quebec, QPIP also applies when the remuneration is subject to EI). The CRA specifically notes that you must deduct EI premiums from bonuses/retroactive pay (up to the annual maximum), and the CRA's guidance for bonuses/irregular amounts uses tools (PDOC/formulas) that calculate CPP contributions, EI premiums, and income tax on these payments.
In Quebec payroll, remuneration that is subject to EI premiums is generally also subject to QPIP premiums, so bonuses/incentives that are EI-insurable are typically QPIP-insurable as well.
In the Northwest Territories and Nunavut, there is also a statutory territorial payroll tax that employers must withhold/remit where applicable, and the NWT guidance explicitly lists bonuses as part of employment income subject to payroll tax.
50. Frage
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)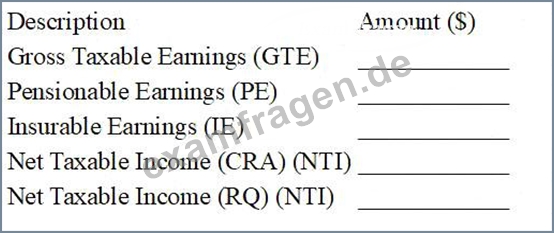
STATUTORY DEDUCTIONS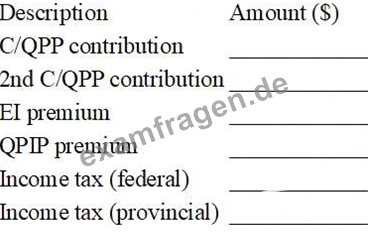
OTHER DEDUCTIONS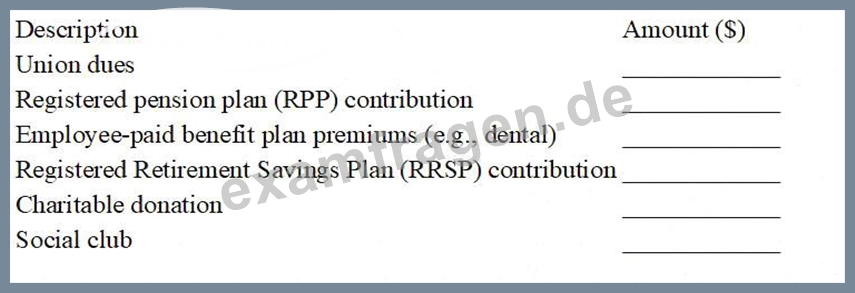
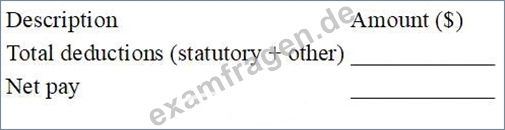
Given Data (Reference)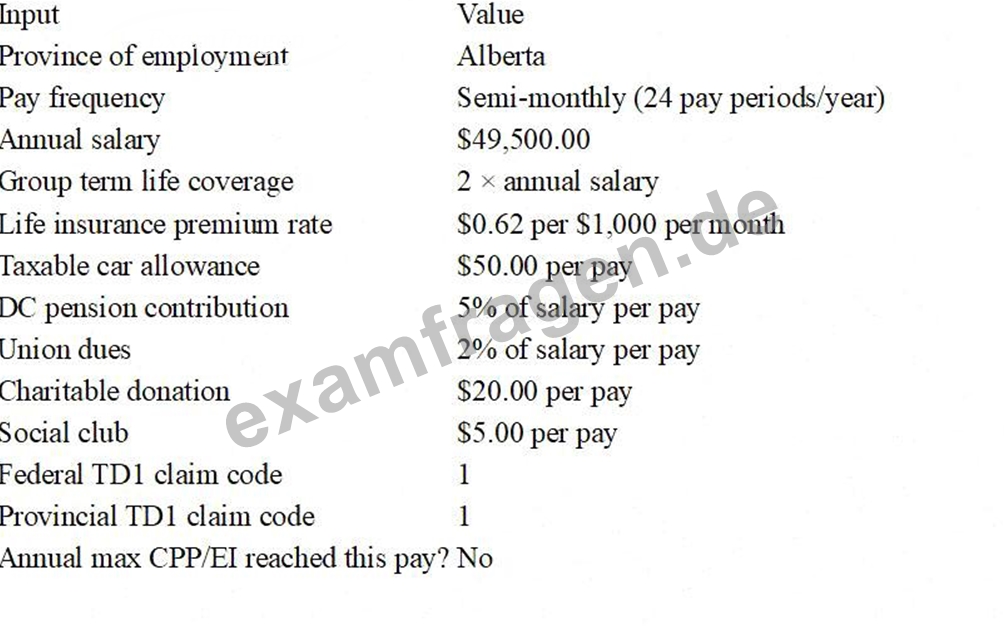
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Antwort:
Begründung:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
51. Frage
A death benefit is a:
Antwort: A
Begründung:
The CRA defines a death benefit as the gross amount of any payment made on or after the death of an employee to recognize the employee's service in an office or employment. It can be paid to a surviving spouse
/common-law partner, heir, or the estate.
This is different from amounts the employee already earned before death (for example, regular wages up to the date of death, or vacation pay that was accrued/earned). CRA guidance treats wages and employment income earned up to and including the date of death as amounts to be reported on a T4 slip, not as a death benefit.
It's also different from a life insurance payout from an insurer (which is not an employer-paid "death benefit" for payroll reporting purposes). The payroll impact is that a qualifying death benefit is generally reported as a special payment (often on a T4A), following CRA rules for deductions and reporting of death benefits.
52. Frage
A premium payment for overtime hours worked or a rate per piece of goods produced is an example of:
Antwort: C
Begründung:
Overtime premiums and piece-rate pay are forms of earnings because they are amounts paid for work performed. CRA's payroll guidance confirms overtime pay is remuneration from which you must deduct statutory deductions (CPP, EI, and income tax), reflecting that overtime is treated as employment earnings.
Similarly, piecework (piece-rate pay) is a method of paying wages based on units produced rather than time.
It is still compensation for labour and therefore part of gross earnings used to calculate payroll deductions and net pay. This is fundamentally different from:
Expense reimbursements, which repay employee-incurred business costs (not pay for work).
Allowances, which are predetermined amounts to help cover anticipated expenses without receipts.
Benefits, which are the value of goods/services provided by the employer or paid on the employee's behalf.
So a premium paid for overtime hours or a piece-rate per unit produced is classified as earnings (option A).
53. Frage
In Block 12 of the Record of Employment, the final pay period ending date for employees who are paid solely by commission or are paid salary plus irregularly paid commission will be:
Antwort: B
Begründung:
Service Canada treats commission salespeople (paid solely by commission or salary plus irregularly paid commission) as a special ROE situation where the weekly averaging formula is used. In that scenario, the ROE Guide states that for Block 12 (Final pay period ending date) you must use the Saturday of the week that contains the last day for which paid (Block 11).
This is different from the usual rule for most employees, where Block 12 is simply the end date of the final pay period that includes the Block 11 date (and it can't be earlier than Block 11).
The key reason is consistency in applying the weekly averaging approach: even if the employer's actual payroll cycle is not weekly, commission-only/irregular-commission employees are reported using a weekly framework for ROE purposes. Payroll should therefore align Block 12 to the correct "weekly" period end (Saturday) when that rule applies, to avoid ROE errors and Service Canada follow-up.
54. Frage
......
Nun bieten viele Ausbildungsinstitute Ihnen die Schulungsunterlagen zur National Payroll Institute PF1 Zertifizierungsprüfung. Meistens bekommen die Kandidaten per diese Websites keine ausführlichen Materialien. Denn ihre Materialien zur National Payroll Institute PF1 Zertifizierungsprüfung sind breit gefächert und nicht zielgerichtet. So können sie keine Aufmerksamkeit der Kandidaten gewinnen.
PF1 PDF: https://www.examfragen.de/PF1-pruefung-fragen.html
P.S. Kostenlose 2026 National Payroll Institute PF1 Prüfungsfragen sind auf Google Drive freigegeben von ExamFragen verfügbar: https://drive.google.com/open?id=1h6uoGsa4AdLM4i6I9S0HnAhPlAMqBR4w