BTW, DOWNLOAD part of TestPassed PF1 dumps from Cloud Storage: https://drive.google.com/open?id=1QNOtJLa-52D2OEA2Z5SRv6-EjJ28U_e5
Our PF1 study materials have enough confidence to provide the best PF1 exam torrent for your study to pass it. With many years work experience, we have fast reaction speed to market change and need. In this way, we have the latest PF1 guide torrent. You don't worry about that how to keep up with the market trend, just follow us. We can say that our PF1 Test Questions are the most suitable for examinee to pass the PF1 exam, you will never regret to buy it.
| Section | Weight | Objectives |
|---|---|---|
| Communication and Compliance | 10% | - Accuracy and documentation
|
| Termination and Special Payments | 30% | - Leaves and absences
|
| Record of Employment (ROE) | 20% | - Submission and deadlines
|
| Individual Pay Calculations | 40% | - Non-regular earnings
|
>> PF1 Authentic Exam Questions <<
For candidates who are going to buying PF1 exam materials, the pas rate for the exam is quite important, and it will decide whether you can pass your exam successfully or not. Pass rate for is 98.65% for PF1 exam materials, and if you choose us, we can help you pass the exam just one time. In addition PF1 Exam Materials are high quality and accuracy, and they can improve your efficiency. We are pass guarantee and money back guarantee for PF1 exam dumps, if you fail to pass the exam, we will give you full refund.
NEW QUESTION # 45
Which of the following types of payments made by a private organization would not be subject to all statutory deductions?
Answer: A
Explanation:
The payment type most clearly not subject to all statutory deductions is directors' fees. CRA guidance on directors' fees shows they are treated as a special payment with distinct deduction rules, and (depending on the situation) they may not have CPP, EI, and income tax all apply in the same way as normal employment earnings.
By contrast, retroactive adjustments and performance bonuses are treated as taxable remuneration where CRA' s tools (like PDOC) calculate CPP contributions, EI premiums, and income tax on those payments (up to annual maximums).
"Vacation pay when no time was taken" is also treated as a non-periodic payment and is included in CRA payroll deduction formulas as a type of amount on which statutory deductions are calculated (again, subject to annual maximums for CPP/EI).
So, among the options listed, directors' fees are the one that would not necessarily be subject to all statutory deductions in the standard way.
NEW QUESTION # 46
Which of the following types of earnings are not considered income from employment?
Answer: D
Explanation:
Regular salary, vacation pay, and commissions are generally treated as income from employment because they are amounts paid for services performed during employment. In contrast, what many people call
"severance pay" is often classified by the CRA as a retiring allowance-an amount paid when or after an employee retires or loses their job, in recognition of long service or for the loss of employment.
This distinction matters in payroll because a retiring allowance has its own rules for withholding and potential RRSP/RPP transfer eligibility, and it is not treated the same way as normal employment income earned while actively employed. CRA technical guidance also draws lines between amounts that are employment income versus retiring allowance depending on the nature/timing of the payment.
So, among the options listed, severance pay (when it is a retiring allowance) is the one that is not considered income from employment in the way salary/vacation pay/commissions are.
NEW QUESTION # 47
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)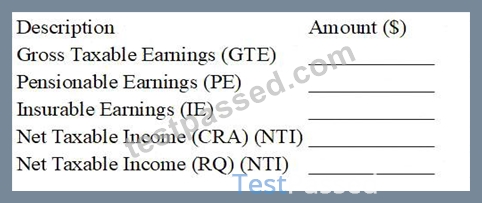
STATUTORY DEDUCTIONS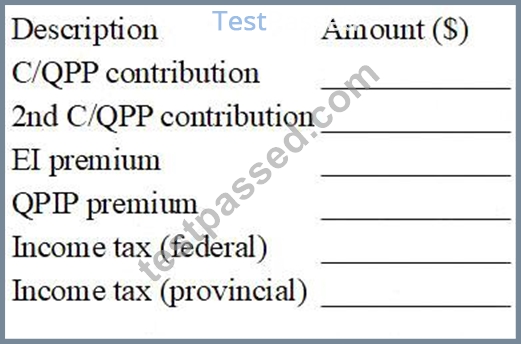
OTHER DEDUCTIONS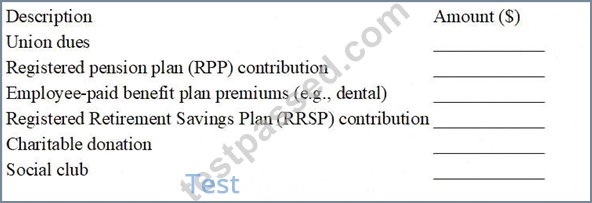
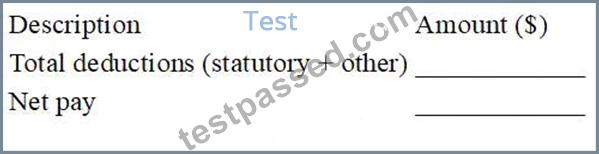
Given Data (Reference)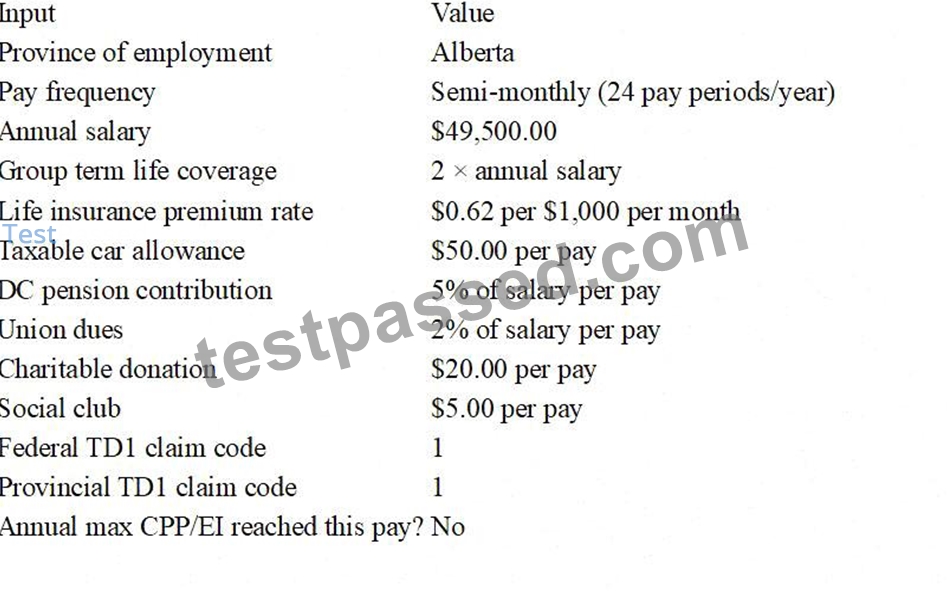
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 48
A Third Party Demand is issued by the Canada Revenue Agency for:
Answer: C
Explanation:
A "Third Party Demand" in payroll collections commonly refers to the CRA's Demand on a Third Party (DTP)-a legal garnishment tool used to collect a person's debt to the government by requiring a third party (such as an employer or financial institution) to redirect funds that would otherwise be paid to the debtor.
CRA guidance explains that garnishments may be issued as a Requirement to Pay (RTP), Enhanced Requirement to Pay (ERTP), or Demand on a Third Party (DTP), and that these documents apply when money normally payable to someone who owes a debt to the government must instead be paid to the CRA (or other listed federal bodies).
This aligns with option B: unpaid income tax or unpaid statutory deductions (such as payroll source deductions) can lead to CRA collection action using these legal instruments.
Child support is generally enforced under provincial/territorial family support programs, not via CRA DTP as described here. Overpaid EI benefits are typically handled through EI/Service Canada recovery processes, and
"third-party creditor debt" is not a CRA-administered debt.
NEW QUESTION # 49
What information is required to calculate thestandby charge, thereduced standby charge, and theoperating cost benefitfor a company-owned automobile?
Answer: D
Explanation:
CRA's automobile benefit calculations require multiple data points because there are usuallytwo components thestandby charge(vehicle availability) and theoperating expense benefit(personal driving where the employer pays operating costs). CRA's guidance on employer-provided automobiles explains that standby charge calculations use the automobile'scost (capital cost) including applicable taxesand the time the vehicle wasavailableto the employee, while the reduced standby charge and operating benefit depend on kilometres drivenand the split betweenbusiness and personal use.
To determine whether areduced standby chargeapplies, you need availability plusbusiness-use requirements(which are evidenced through total/business kilometres). To calculate the operating expense benefit, you needpersonal kilometres(often derived from total kilometres minus business kilometres) or detailed personal km directly.
Therefore, the complete and correct set of required inputs is:capital cost (with sales tax), availability, total kilometres, business kilometres, and personal kilometres-which is optionD.
NEW QUESTION # 50
......
Will you feel nervous for the exam? If you do, we can relieve your nerves if you choose us. PF1 Soft test engine can stimulate the real exam environment, so that you can know procedures of the real exam environment, and it will build up your confidence. In addition, PF1 exam materials are verified by the experienced experts, and therefore the quality can be guaranteed. We offer you free demo to have a try before buying, so that you can have a better understanding of what you are going to buy. If you buy PF1 Exam Materials from us, we also pass guarantee and money back guarantee if you fail to pass the exam.
PF1 Sure Pass: https://www.testpassed.com/PF1-still-valid-exam.html
BTW, DOWNLOAD part of TestPassed PF1 dumps from Cloud Storage: https://drive.google.com/open?id=1QNOtJLa-52D2OEA2Z5SRv6-EjJ28U_e5