Fast2test 就是一個可以滿足很多參加 CSI 的 AFP-Exam-1 認證考試的IT人士的需求的網站,但是要想通過 AFP-Exam-1 考試還需要大家認真理解。即使是CSI 的 AFP-Exam-1 擬真試題和真實考試中的差不多,建議大家考試的時候,還是要把題看清楚,不能完全按照 AFP-Exam-1 擬真試題中的命令去做。要靈活運用,積極思考,不能死搬硬套。通過這個考試是需要豐富的知識和經驗的,而積累豐富的知識和經驗是需要時間的。
| Section | Weight | Objectives |
|---|---|---|
| Estate Planning | 13% | - Trust and Beneficiary Planning - Powers of Attorney - Estate Transfer Strategies - Wills |
| Risk Management and Insurance | 12% | - Disability and Health Insurance - Life Insurance - Risk Assessment - Risk Transfer Strategies |
| Client Relationship and Practice Management | 6% | - Client Discovery - Communication and Advisory Process - Practice Management |
| Retirement Planning | 17% | - Retirement Needs Analysis - Pension Plans - Retirement Income Strategies - Registered Retirement Savings Plans |
| Investment Planning | 17% | - Investment Products - Investment Theory - Portfolio Construction - Asset Allocation |
| Professional Conduct and Regulatory Compliance | 10% | - Compliance Responsibilities - Ethics and Professional Standards - Regulatory Requirements |
| Tax Planning | 14% | - Tax Deductions and Credits - Tax-Efficient Strategies - Income Tax Fundamentals - Registered Plans |
| Asset and Liability Management | 11% | - Personal Balance Sheet Analysis - Budgeting - Debt Management - Cash Flow Management |
CSI 提供的認證具有一種震撼力,業界人士都知道,擁有 AFP-Exam-1 認證指南,將意味著在全球範圍內可獲得一個令人羨慕的工作和豐厚的優惠待遇。而 Fast2test的 AFP-Exam-1 權威考試題庫軟件是 CSI 認證廠商的授權產品,可以保證考生第一次參加 AFP-Exam-1 考試的考生即可順利通過,否則承諾全額退款。
問題 #91
Demario, age 29, has started his own professional practice. He is single, has a mortgage, and his future earning power is his largest asset. Which insurance should receive priority?
答案:B
解題說明:
For a young self-employed professional, the dominant exposure is interruption of earned income. Disability insurance protects human capital by replacing income if illness or injury prevents the client from working.
Because Demario is self-employed, he may not have employer long-term disability benefits, paid sick leave, or group coverage. Option B is irrelevant because joint last-to-die coverage is built for two lives and estate liquidity after the second death. Option C is narrow and does not protect ongoing income. Option D may be useful in some estate plans, but estate equalization is not the priority for a single client whose key asset is earning ability. The planner should review own-occupation wording, elimination period, benefit period, inflation indexing, residual disability benefits, integration with emergency savings, and business overhead coverage if practice expenses must continue. The correct planning lens is income protection before estate accumulation. References/topics: disability insurance, human capital, self-employed clients, income replacement.
問題 #92
Justis, age 62, and his wife Jen, age 58, are meeting with their financial planner, Luke. They are both planning to retire by age 65. Their goals are to minimize debt and reduce taxes. The couple's financial situation is outlined below.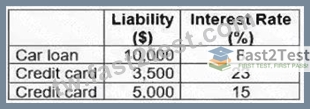
Justis' annual income is $25,000. He has a $15,000 RRSP, $30,000 single non-registered account and a
$25,000 TFSA. Jen's annual income is $60,000, and she has a $150,000 RRSP, $50,000 single non-registered account and a $20,000 TFSA.
Jen's marginal tax rate is 35%, and Justis' is 25%. Assuming all investments are making interest income of
10%, what would be the most appropriate strategy for Luke to recommend for the couple?
答案:D
解題說明:
Luke should recommend using Jen's non-registered funds because that option clears the liabilities without triggering registered-plan withdrawal income. The debts total $18,500 and include expensive consumer borrowing: credit cards at 23% and 15%, plus a car loan at 8%. The couple's taxable investments earn 10% interest before tax, so Jen's after-tax return is approximately 6.5% at a 35% marginal rate. Paying the credit cards is equivalent to earning a risk-free after-tax return equal to the interest avoided, which is materially better than leaving the money invested. Using either spouse's RRSP would create taxable income and permanently reduce retirement capital. Using Justis's non-registered funds is less effective because his lower tax rate makes his after-tax investment return higher than Jen's, so Jen's taxable account is the better source.
Study Guide focus: debt repayment priority, after-tax returns, registered versus non-registered withdrawals, and household cash-flow planning. The recommendation also preserves retirement accounts for the couple's age-65 objective while eliminating the highest-cost liabilities first.
問題 #93
A high-income parent gives $80,000 to a 12-year-old child to invest in a non-registered bond fund. The parent expects the child to report the annual interest income. What rule should the planner identify?
答案:B
解題說明:
Canadian attribution rules are designed to prevent simple income splitting through transfers to related persons, including minor children. When a parent gifts property to a minor child, income such as interest and dividends from the transferred property may attribute back to the parent. The account name alone does not determine the tax result. Option A therefore misses the anti-avoidance rule. Option C is not practical unless the child has earned income and RRSP room, and it does not address attribution. Option D is too narrow; attribution can apply in several family-transfer situations. A planner should consider alternatives such as RESPs, Canada Child Benefit amounts actually belonging to the child, prescribed-rate loan structures with proper interest payment, or investing for capital gains where appropriate and legally supported. The advice must separate legal ownership, tax reporting, and beneficial source of funds. References/topics: income attribution, minor children, family tax planning, non-registered investments.
問題 #94
Mary, an accredited financial planner, recently met with clients Michael and Radha. They are high- net-worth clients who are in their mid-40s. Michael is a heavy equipment operator at a local oil field, and Radha is a homemaker. They are ready to retire in 10 years and very excited to start planning for the next chapter in their lives. Mary explained her planning process, her accreditation, and her remuneration. When Mary presented the client agreement letter, both clients were surprised. They said they did not know why they would sign a letter to get advice on their own finances. How should Mary answer their question?
答案:C
解題說明:
Mary should explain that the client agreement letter is the engagement document for the advisory relationship.
It confirms what services will be provided, the scope of planning, the roles and responsibilities of the clients and planner, how the planner is compensated, and any limitations or business arrangements that matter to the relationship. It is not the investment strategy itself; that comes after discovery, analysis, and recommendations. It is also not merely an informal or irrelevant bank form. A well-written engagement letter protects the clients because it tells them what they can expect, what information they must provide, and how decisions will be documented. For high-net-worth clients, clarity is even more important because multiple planning areas, specialists, and implementation steps may be involved. Mary should position the letter as a professional standard, not as a barrier to advice. Study Guide focus: engagement letters, financial planning process, client expectations, disclosure, and practice management.
問題 #95
A client says she can emotionally tolerate a 30% portfolio decline, but she needs the money in 18 months for a home down payment and has no other savings. What should the planner conclude?
答案:D
解題說明:
The planning distinction is between risk tolerance and risk capacity. Risk tolerance is the client's psychological comfort with volatility. Risk capacity is the financial ability to withstand loss without jeopardizing a goal. Here, the funds have a short, specific time horizon and no substitute source. A 30% decline shortly before the home purchase could make the goal impossible. Option A confuses willingness with suitability. Option B is incomplete because experience matters, but goal timing and liquidity dominate this case. Option D is irrelevant to the core issue; taxes do not override capital preservation when funds are needed in 18 months. A course-guide analysis would recommend a liquid, low-volatility vehicle such as a high- interest savings account, short-term GIC ladder if timing allows, or money market-type solution, depending on guarantees and access. The planner must document why the client's emotional tolerance does not justify exposing goal-critical capital to equity volatility. References/topics: risk capacity, time horizon, liquidity, goal-based investing.
問題 #96
......
Fast2test長年以來一直向大家提供關于IT認證考試相關的學習資料。CSI的AFP-Exam-1題庫由世界各地的資深IT工程師組成的專業團隊制作完成,包含最新的考試試題,并附有全部正確的答案,幫助考生通過他們認為很難的AFP-Exam-1考試。這樣可以節約考生的時間和金錢,大多數的考生都選擇這樣的方式來獲得AFP-Exam-1認證,并節省了很多的時間和努力。您需要是在反復練習這份真題的基礎上,多思考,多總結,通過AFP-Exam-1考試就沒有問題了。
AFP-Exam-1考試證照: https://tw.fast2test.com/AFP-Exam-1-premium-file.html