The passing rate of our AFP-Exam-1 training quiz is 99% and the hit rate is also high. Our professional expert team seizes the focus of the exam and chooses the most important questions and answers which has simplified the important AFP-Exam-1 information and follow the latest trend to make the client learn easily and efficiently. We update the AFP-Exam-1 Study Materials frequently to let the client practice more and follow the change of development in the practice and theory.
| Section | Weight | Objectives |
|---|---|---|
| Enabling Competencies | 16% | - Professional Conduct and Regulatory Compliance - Client Relationship and Practice Management |
| Technical Competencies | 84% | - Investment Planning - Risk Management and Insurance - Estate Planning - Tax Planning - Asset and Liability Management - Retirement Planning |
>> Latest AFP-Exam-1 Version <<
CSI is one of the international top companies in the world providing wide products line which is applicable for most families and companies, and even closely related to people's daily life. Passing exam with AFP-Exam-1 valid exam lab questions will be a key to success; will be new boost and will be important for candidates' career path. CSI offers all kinds of certifications, AFP-Exam-1 valid exam lab questions will be a good choice.
NEW QUESTION # 94
A high-income parent gives $80,000 to a 12-year-old child to invest in a non-registered bond fund. The parent expects the child to report the annual interest income. What rule should the planner identify?
Answer: A
Explanation:
Canadian attribution rules are designed to prevent simple income splitting through transfers to related persons, including minor children. When a parent gifts property to a minor child, income such as interest and dividends from the transferred property may attribute back to the parent. The account name alone does not determine the tax result. Option A therefore misses the anti-avoidance rule. Option C is not practical unless the child has earned income and RRSP room, and it does not address attribution. Option D is too narrow; attribution can apply in several family-transfer situations. A planner should consider alternatives such as RESPs, Canada Child Benefit amounts actually belonging to the child, prescribed-rate loan structures with proper interest payment, or investing for capital gains where appropriate and legally supported. The advice must separate legal ownership, tax reporting, and beneficial source of funds. References/topics: income attribution, minor children, family tax planning, non-registered investments.
NEW QUESTION # 95
Dianna is visiting with Karen, her Financial Planner, and is excited to report that she has just bought her dream home. She has also let Karen know she Is meeting with an insurance representative to purchase a whole life insurance to cover her 20-year mortgage. Why might Karen suggest Dianna consider term life insurance instead?
Answer: D
Explanation:
Karen's recommendation should match the insurance product to the liability. Dianna's need is temporary: a 20- year mortgage balance that would create financial hardship if she died before the debt was retired. Term life insurance is designed for temporary capital needs and normally provides the largest amount of death benefit for the lowest initial premium because it contains no cash-value savings component. Whole life can be appropriate for permanent estate liquidity, final taxes, charitable objectives, or lifetime dependency needs, but those facts are not present. Option A may be true as a general underwriting concern, but it does not explain why term is better for this mortgage need. Option B is false because term insurance does not build cash value.
Option C describes permanent needs, not a 20-year mortgage. The AFP planning conclusion is that term coverage should be considered where the risk period and capital need are limited. Study Guide focus: needs- based insurance analysis, term versus permanent insurance, mortgage protection, and product suitability.
NEW QUESTION # 96
Justis, age 62, and his wife Jen, age 58, are meeting with their financial planner, Luke. They are both planning to retire by age 65. Their goals are to minimize debt and reduce taxes. The couple's financial situation is outlined below.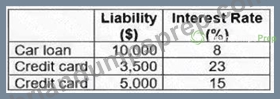
Justis' annual income is $25,000. He has a $15,000 RRSP, $30,000 single non-registered account and a
$25,000 TFSA. Jen's annual income is $60,000, and she has a $150,000 RRSP, $50,000 single non-registered account and a $20,000 TFSA.
Jen's marginal tax rate is 35%, and Justis' is 25%. Assuming all investments are making interest income of
10%, what would be the most appropriate strategy for Luke to recommend for the couple?
Answer: D
Explanation:
Luke should recommend using Jen's non-registered funds because that option clears the liabilities without triggering registered-plan withdrawal income. The debts total $18,500 and include expensive consumer borrowing: credit cards at 23% and 15%, plus a car loan at 8%. The couple's taxable investments earn 10% interest before tax, so Jen's after-tax return is approximately 6.5% at a 35% marginal rate. Paying the credit cards is equivalent to earning a risk-free after-tax return equal to the interest avoided, which is materially better than leaving the money invested. Using either spouse's RRSP would create taxable income and permanently reduce retirement capital. Using Justis's non-registered funds is less effective because his lower tax rate makes his after-tax investment return higher than Jen's, so Jen's taxable account is the better source.
Study Guide focus: debt repayment priority, after-tax returns, registered versus non-registered withdrawals, and household cash-flow planning. The recommendation also preserves retirement accounts for the couple's age-65 objective while eliminating the highest-cost liabilities first.
NEW QUESTION # 97
Tom has two children from a previous marriage. He has been paying $1,000 per month for spousal support and $1,500 per month for child support to his ex-wife. Recently, his ex-wife was awarded increased child support payments from Tom to cover unanticipated university expenses for one of the children. What should Tom's financial planner advise him about how this increased monthly payment may impact his finances?
Answer: D
Explanation:
The increased child support payment reduces Tom's net cash flow by the full amount. Under the standard tax treatment, child support is not deductible to the payer and is not taxable to the recipient. That differs from qualifying periodic spousal support, which may be deductible to the payer and taxable to the recipient when the legal requirements are met. Because the increased amount relates to child support for university expenses, Tom receives no tax deduction and no offsetting tax credit merely because he pays more. The tuition tax credit belongs to the eligible student unless transferred under applicable rules; it is not automatically applied to Tom because he pays support. The planner should update Tom's cash-flow plan, debt ratios, retirement savings ability, and emergency reserve using the full increased payment. Study Guide focus: child support, spousal support, tax deductibility, cash-flow planning, and separation agreements. This distinction is essential when modelling separation settlements because gross payments and after-tax cost can differ sharply.
NEW QUESTION # 98
Leena and Harry are married and hold RRSPs with a value exceeding $500,000. They are concerned about their final tax liability and want to cover the taxes after they have both died. What would their financial planner recommend them to implement in order for the couple to achieve the objective?
Answer: C
Explanation:
A joint last-to-die permanent life insurance policy is designed for a tax liability that arises after both spouses have died. Leena and Harry are concerned about the final tax exposure on large RRSP balances. If one spouse dies first and the surviving spouse is the beneficiary or successor annuitant, RRSP/RRIF amounts may generally roll to the survivor on a tax-deferred basis. The larger tax problem usually appears on the second death, when no spouse remains for rollover and the registered assets are included in income. Last-to-die coverage pays at that point and can provide estate liquidity for taxes without forcing asset sales. A testamentary trust does not itself fund the tax bill. Updating beneficiaries to each other helps deferral but not the final liability. An inter vivos trust cannot simply receive RRSP assets without tax consequences. Study Guide focus: RRSP/RRIF death taxation, spousal rollover, permanent insurance, estate liquidity, and last-to- die planning.
NEW QUESTION # 99
......
Our AFP-Exam-1 exam questions generally raised the standard of practice materials in the market with the spreading of higher standard of knowledge in this area. So your personal effort is brilliant but insufficient to pass the Applied Financial Planning Certification Exam 1 (AFP) exam and our AFP-Exam-1 test guide can facilitate the process smoothly & successfully. Our Applied Financial Planning Certification Exam 1 (AFP) practice materials are successful by ensuring that what we delivered is valuable and in line with the syllabus of this exam. And our AFP-Exam-1 Test Guide benefit exam candidates by improving their ability of coping the exam in two ways, first one is their basic knowledge of it.
AFP-Exam-1 Test Result: https://www.briandumpsprep.com/AFP-Exam-1-prep-exam-braindumps.html