BTW, DOWNLOAD part of ITexamReview Accounting-for-Decision-Makers dumps from Cloud Storage: https://drive.google.com/open?id=1Y7I7NuDFez9_x0bKyW71tKSi0rm_Ugom
Only with high quality and valid information of our Accounting-for-Decision-Makers exam braindumps, our candidates can successfully pass their exams. At the same time, own to our professional experts constantly improvement on the design of the Accounting-for-Decision-Makers study materials, we have developed three versions of layouts: PDF, Software and APP online. Though the content of them are the same, the different layouts provide lots of conveniences out of your imagination. Just have a try and you will love our Accounting-for-Decision-Makers Practice Engine.
| Section | Objectives |
|---|---|
| Topic 1: Managerial Accounting for Decision Making | - Cost Behavior
|
| Topic 2: Business Decision Support | - Relevant Costing
|
| Topic 3: Financial Accounting Fundamentals | - Accounting Principles
|
>> Accounting-for-Decision-Makers Reliable Test Sims <<
Our WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) practice exam can be modified in terms of length of time and number of questions to help you prepare for the WGU real test. We're certain that our Accounting-for-Decision-Makers Questions are quite similar to those on Accounting-for-Decision-Makers real exam since we regularly update and refine the product based on the latest exam content.
NEW QUESTION # 11
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.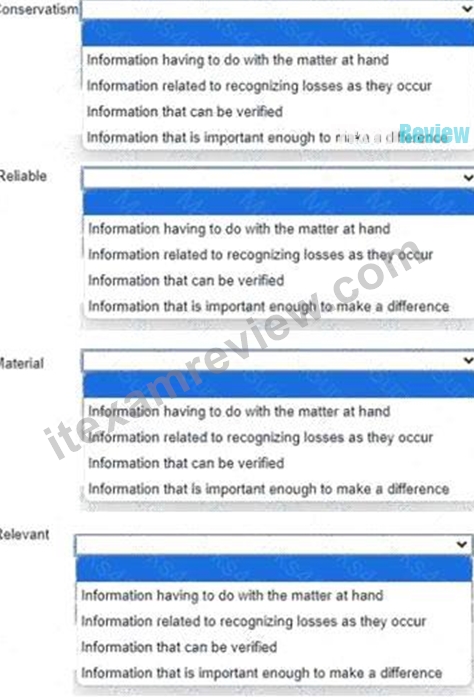
Answer:
Explanation: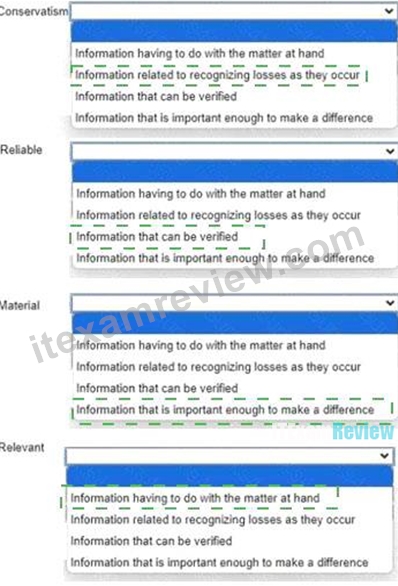
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
NEW QUESTION # 12
Which overhead cost is associated with batch-level activities?
Answer: A
Explanation:
The correct answer is B. Machine setups . In activity-based costing , batch-level activities are performed each time a batch of goods is processed, regardless of how many units are in that batch. A classic example is the machine setup required before production of a batch can begin. ABC materials commonly identify setup costs as batch-level because the activity occurs per batch rather than per individual unit.
Option A, property taxes , and Option C, factory insurance , are usually considered facility-level or organization-sustaining overhead because they support the factory as a whole rather than a specific batch.
Option D, product engineering wages , is more closely related to product-level activities , since engineering work often supports a particular product line rather than each batch run. Batch-level costs increase with the number of production batches, not necessarily with the number of units produced. Since machine setups are incurred each time a batch is started, they are the standard example of a batch-level overhead cost. Therefore, Option B is the correct answer.
NEW QUESTION # 13
What does it mean if a company has a debt ratio of 101.5%?
Answer: C
Explanation:
The correct answer is B. The company has 1.5% more total liabilities than total assets . The debt ratio is calculated as:
Debt ratio = Total liabilities / Total assets
If the debt ratio is 101.5% , or 1.015 , that means total liabilities are 101.5% of total assets . In other words, liabilities are slightly greater than assets. Specifically, the company has 1.5% more liabilities than assets .
This is an important financial warning sign because it suggests the company may have negative equity .
Since the accounting equation is:
Assets = Liabilities + Owners' equity
if liabilities exceed assets, then owners' equity must be negative. That can indicate financial distress, accumulated losses, or a highly leveraged position.
Option A is incorrect because the debt ratio does not compare liabilities to sales. Option C is incorrect because it does not compare liabilities to net income. Option D is incorrect because the debt ratio uses total liabilities and total assets , not current liabilities and current assets. Therefore, the only correct interpretation of a 101.5% debt ratio is that total liabilities exceed total assets by 1.5% , making Option B correct.
NEW QUESTION # 14
Which two details can management determine through a cost-volume-profit analysis?
Choose 2 answers.
Answer: B,C
Explanation:
The correct answers are A and B . Cost-volume-profit (CVP) analysis is a forward-looking planning tool used to study how changes in costs , sales volume , and selling price affect contribution margin, break-even point, and target profit. OpenStax describes CVP analysis as one of the most useful tools in managerial accounting for analyzing how changing business situations affect profit.
Option A is correct because CVP helps management estimate how a future change in variable costs or fixed costs would influence profit. Option B is also correct because CVP can determine how many units must be sold to achieve a desired target income or profit level. In contrast, Options C and D focus on past transactions and past tax costs, which are not the primary purpose of CVP analysis. CVP is mainly a planning and decision-making method rather than a historical reporting tool. It helps managers ask "what happens if" questions about future operations, such as what sales volume is needed to earn a target profit or how a change in cost structure would affect margins. Therefore, the correct choices are A and B .
NEW QUESTION # 15
Where should a company report cash payments to acquire or construct long-term fixed assets on a statement of cash flows?
Answer: C
Explanation:
The correct answer is C. Cash flows from investing activities . Cash paid to acquire, build, or improve long- term fixed assets such as land, buildings, machinery, and equipment is classified as an investing cash outflow on the statement of cash flows. OpenStax explains that the investing section of the statement of cash flows relates to changes in long-term assets , which includes capital expenditures for property, plant, and equipment. FASB cash flow guidance also requires classifying cash receipts and payments as operating, investing, or financing based on the nature of the activity.
Option B is incorrect because operating activities relate to the core day-to-day revenue-producing operations of the company. Option D is incorrect because financing activities involve obtaining or repaying capital, such as borrowing, issuing stock, or paying dividends. Option A is not a standard reporting category under the statement of cash flows. Since buying or constructing long-term fixed assets represents investment in productive resources for future use, the correct classification is Cash flows from investing activities .
NEW QUESTION # 16
......
If you are curious or doubtful about the proficiency of our Accounting-for-Decision-Makers preparation quiz, we can explain the painstakingly word we did behind the light. By abstracting most useful content into the Accounting-for-Decision-Makers exam materials, they have helped former customers gain success easily and smoothly. The most important part is that all contents were being sifted with diligent attention. No errors or mistakes will be found within our Accounting-for-Decision-Makers Study Guide.
Accounting-for-Decision-Makers Latest Test Materials: https://www.itexamreview.com/Accounting-for-Decision-Makers-exam-dumps.html
2026 Latest ITexamReview Accounting-for-Decision-Makers PDF Dumps and Accounting-for-Decision-Makers Exam Engine Free Share: https://drive.google.com/open?id=1Y7I7NuDFez9_x0bKyW71tKSi0rm_Ugom