P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by BraindumpsPrep: https://drive.google.com/open?id=1x38ixLd30KKn7A12F0KXQ4y131pLmy8R
The National Payroll Institute PF1 is a very prestigious certificate that is considered a guarantee of a well-paid job in a reputed tech firm. Most candidates attempting the Payroll Fundamentals 1Exam test are nervous. Very few applicants can earn the Payroll Fundamentals 1Exam PF1 certificate on their first attempts because of the challenging level of topics included in the National Payroll Institute PF1 test. BraindumpsPrep PF1 actual dumps help applicants in clearing the test very easily.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Individual Pay Calculations | 40% | - Non-regular earnings
|
| Topic 2: Communication and Compliance | 10% | - Stakeholder communication
|
| Topic 3: Termination and Special Payments | 30% | - Termination payments
|
| Topic 4: Record of Employment (ROE) | 20% | - Submission and deadlines
|
BraindumpsPrep IT expert team take advantage of their experience and knowledge to continue to enhance the quality of exam training materials to meet the needs of the candidates and guarantee the candidates to pass the National Payroll Institute Certification PF1 Exam which is they first time to participate in. Through purchasing BraindumpsPrep products, you can always get faster updates and more accurate information about the examination. And BraindumpsPrep provide a wide coverage of the content of the exam and convenience for many of the candidates participating in the IT certification exams except the accuracy rate of 100%. It can give you 100% confidence and make you feel at ease to take the exam.
NEW QUESTION # 62
Duncan Drapak was employed in Ontario. Upon termination of his employment, he will be paid $7,760.00 legislated wages in lieu of notice together with his final weekly pay of $875.00. Calculate Duncan's Canada Pension Plan (CPP) contribution if the yearly maximum contribution will not be exceeded.
Answer:
Explanation:
$509.78
Explanation:
Legislated wages in lieu of notice are treated as pensionable employment earnings for CPP purposes, so they are included with the employee's final regular pay when calculating CPP deductions (assuming no CPP exemption applies).
Step 1: Determine total pensionable earnings for the week:
$7,760.00 + $875.00 = $8,635.00.
Step 2: Subtract the CPP basic exemption (Year's Basic Exemption is $3,500 annually). For a weekly payroll, the basic exemption is prorated:
$3,500 ÷ 52 = $67.31.
CPP contributory earnings for the week:
$8,635.00 # $67.31 = $8,567.69.
Step 3: Apply the 2026 CPP employee contribution rate of 5.95% (base CPP). The question states the annual maximum will not be exceeded, so no capping is required in this calculation.
CPP contribution:
$8,567.69 × 5.95% = $509.7777..., rounded to $509.78.
NEW QUESTION # 63
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
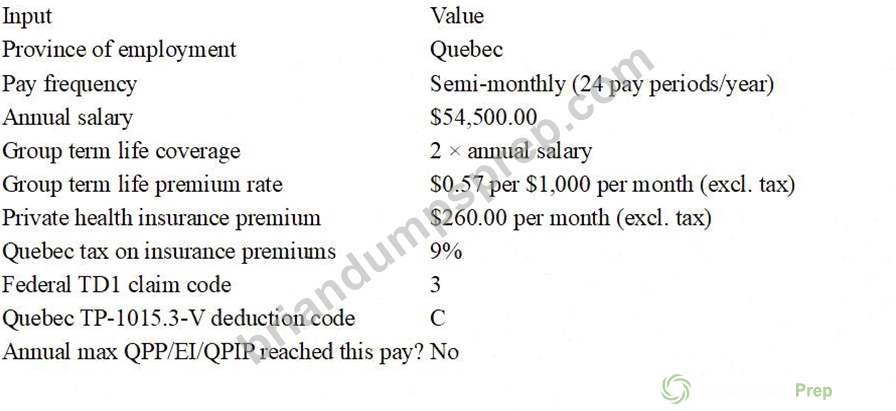
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
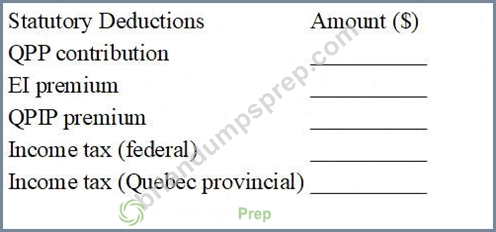
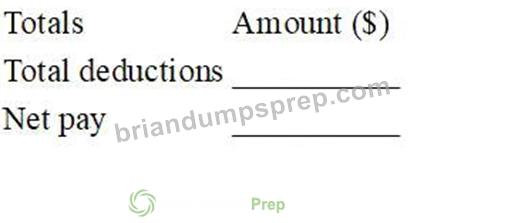
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases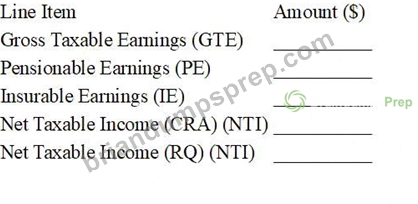
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 64
Which statutory deductions is salary continuance subject to?
Answer: D
NEW QUESTION # 65
Jasmine works for a Saskatchewan employer and earns $500.00 weekly. Calculate her Employment Insurance (EI) premium.
Answer:
Explanation:
$8.15 (employee EI premium for the week)
Explanation:
For employees whose province of employment is outside Quebec (including Saskatchewan), EI premiums are calculated by multiplying the employee's insurable earnings by the employee EI premium rate for the year, up to the annual maximum insurable earnings. For 2026, the employee EI premium rate outside Quebec is $1.63 per $100 of insurable earnings (which is 1.63%).
Jasmine earns $500.00 weekly and (based on the question) we assume all earnings are insurable and she has not reached the annual maximum. Her EI premium is:
$500.00 × 1.63% = $500.00 × 0.0163 = $8.15.
This amount is deducted from the employee's pay and later remitted to the CRA as part of the employer's regular payroll remittance. The maximum insurable earnings for 2026 is $68,900, but at $500 per week she would only hit the maximum later in the year (if at all), so the weekly premium calculation above applies.
NEW QUESTION # 66
Expense reimbursements are:
Answer: D
Explanation:
An expense reimbursement is paid to repay an employee for actual business expenses the employee incurred while performing their job (for example, meals while travelling on business, supplies purchased for work, etc.). CRA's taxable benefits guidance distinguishes reimbursements from allowances: an allowance is usually a predetermined amount paid without the employee having to support the expense with receipts, while a reimbursement is tied to actual costs.
That distinction matters because reimbursements are generally not compensation for work performed (so they are not "earnings"), and they are not "benefits" in the sense of a good or service provided by the employer (though CRA notes that benefits can include reimbursements of personal expenses-so payroll must still ensure the reimbursement is for business use and properly supported).
Option A correctly describes reimbursements. Option B is typically an allowance (for example, a vehicle allowance for using personal property). Option C describes earnings (wages/salary). Option D describes benefits (value of something provided or paid for on the employee's behalf).
NEW QUESTION # 67
......
How our PF1 study questions can help you successfully pass your coming PF1 exam? The answer lies in the outstanding PF1 exam materials prepared by our best industry professionals and tested by our faithful clients. Our exam materials own the most authentic and useful information in questions and answers. For our PF1 practice material have been designed based on the format of real exam questions and answers that you would surely find better than the other exam vendors’.
New PF1 Test Registration: https://www.briandumpsprep.com/PF1-prep-exam-braindumps.html
P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by BraindumpsPrep: https://drive.google.com/open?id=1x38ixLd30KKn7A12F0KXQ4y131pLmy8R