2026 Latest Pass4guide Accounting-for-Decision-Makers PDF Dumps and Accounting-for-Decision-Makers Exam Engine Free Share: https://drive.google.com/open?id=1F64wYQV3Z7bNxDzCHJhmKHGrsKAiJauj
Visit Pass4guide and find out the best features of updated Accounting-for-Decision-Makers exam dumps that is available in three user-friendly formats. We guarantee that you will be able to ace the WGU Accounting for Decision Makers C213 VAC2 Accounting-for-Decision-Makers examination on the first attempt by studying with our actual WGU Accounting-for-Decision-Makers exam questions.
| Section | Objectives |
|---|---|
| Topic 1: Financial Statement Analysis | - Horizontal and vertical analysis - Ratio analysis (liquidity, profitability, solvency, efficiency ratios) - Interpreting financial data for decision-making purposes |
| Topic 2: Managerial Accounting Concepts | - Job order and process costing - Contribution margin and break-even analysis - Cost classification and behavior (fixed, variable, mixed costs) - Cost-Volume-Profit (CVP) analysis |
| Topic 3: Budgeting and Planning | - Variance analysis - Financial budgets (cash budget, budgeted income statement, budgeted balance sheet) - Master budget components - Operating budgets (sales, production, direct materials, direct labor, overhead) |
| Topic 4: Financial Accounting Fundamentals | - Understanding the accounting cycle - Recording transactions and adjusting entries - Accrual vs. cash basis accounting - Preparing financial statements (Income Statement, Balance Sheet, Statement of Cash Flows) |
| Topic 5: Decision Making and Performance Evaluation | - Capital budgeting techniques (NPV, IRR, Payback Period) - Balanced Scorecard concepts - Responsibility accounting and performance metrics - Relevant costs for decision making - Make-or-buy and special order decisions |
>> Exam Accounting-for-Decision-Makers Sample <<
We have three different versions of WGU Accounting for Decision Makers C213 VAC2 prep torrent for you to choose, including PDF version, PC version and APP online version. Different versions have their own advantages and user population, and we would like to introduce features of these versions for you. There is no doubt that PDF of Accounting-for-Decision-Makers exam torrent is the most prevalent version among youngsters, mainly due to its convenience for a demo, through which you can have a general understanding and simulation about our Accounting-for-Decision-Makers Test Braindumps to decide whether you are willing to purchase or not, and also convenience for paper printing for you to do some note-taking. As for PC version of our WGU Accounting for Decision Makers C213 VAC2 prep torrent, it is popular with computer users, and the software is more powerful. Finally when it comes to APP online version of Accounting-for-Decision-Makers test braindumps, as long as you open this study test engine, you are able to study whenever you like and wherever you are.
NEW QUESTION # 44
Under the Sarbanes-Oxley Act, which requirement must an accounting firm that audits public companies meet?
Answer: A
Explanation:
The correct answer is B . Section 201 of the Sarbanes-Oxley Act and related SEC rules prohibit registered public accounting firms from providing certain nonaudit services to their audit clients because those services could impair auditor independence. The SEC's rulemaking specifically identifies prohibited services, including internal audit outsourcing , among other restricted nonaudit services.
Option A is incorrect because SOX requires lead audit partner rotation , not mandatory rotation of the entire audit firm after five years. Option C is incorrect because SOX does not impose a blanket ban on advertising by audit firms. Option D is also incorrect because while the audit committee, not management alone, plays a central role in hiring and overseeing the external auditor, the statement as written is not the key audit-firm requirement highlighted by SOX in this context. The most specific and widely tested SOX requirement here is the prohibition on certain nonaudit services to audit clients. This rule protects objectivity by preventing the auditor from effectively reviewing its own consulting or internal audit work. Therefore, Option B is correct.
NEW QUESTION # 45
What does the overall economic performance of a company for a given time period represent?
Answer: B
Explanation:
The correct answer is A. The net income of the company . In financial accounting, the overall economic performance of a company for a specific period is generally summarized by net income or net loss . Net income reflects the result of revenues, expenses, gains, and losses recognized during the period under accrual accounting. It is the bottom-line measure on the income statement and is widely used to evaluate profitability and performance. OpenStax describes the income statement as the report that presents revenues and expenses for a period and arrives at net income.
Option B focuses only on cash receipts and cash payments, which is a cash flow perspective rather than the full accrual-based measure of economic performance. Option C refers more narrowly to gross profit , because it compares sales with cost of goods sold only and excludes operating expenses, interest, and taxes.
Option D, market value, reflects investor valuation rather than accounting performance for a reporting period.
Since the question asks about the company's overall economic performance for a given time period, the most accurate accounting answer is net income . Therefore, Option A is correct.
NEW QUESTION # 46
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.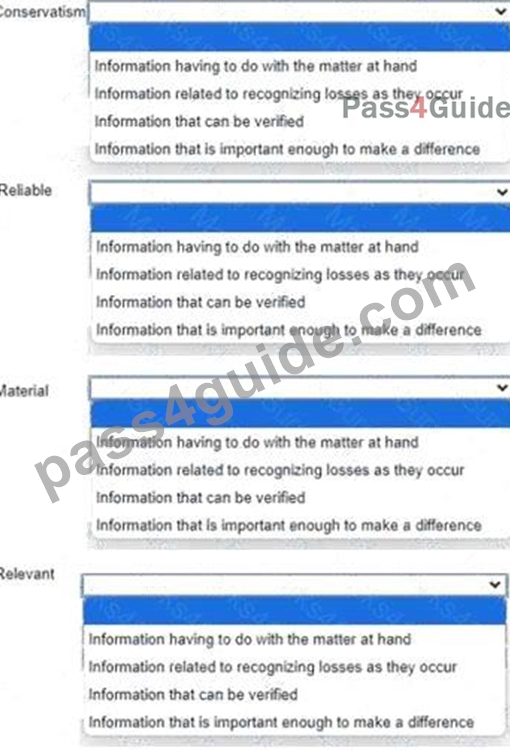
Answer:
Explanation: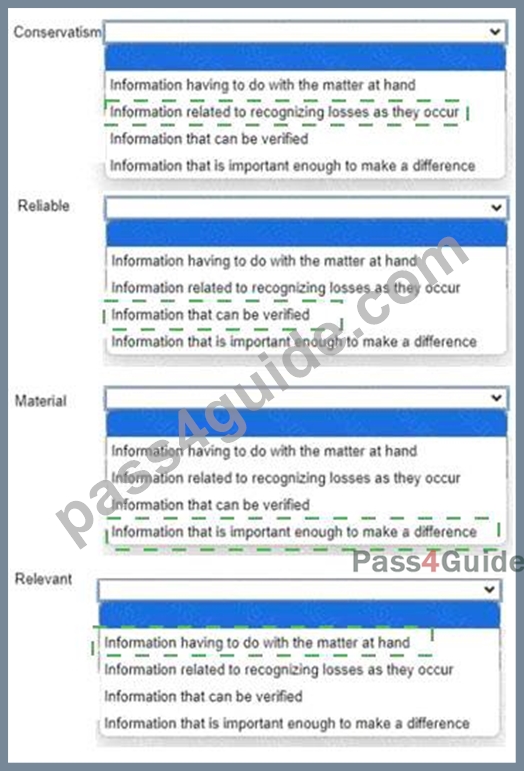
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
NEW QUESTION # 47
In January of Year 1, a company began doing business as a corporation in order to sell technology-related accessories and services. During its first month of operations, the following events occurred:
January 1
The corporation received $900,000 in cash in exchange for stock issued to stockholders.
January 3
The corporation borrowed $250,000 from a bank. The loan is a four-year loan with an interest rate of 12%, payable each year on January 1 beginning in Year 2.
January 5
The corporation purchased equipment to be used in the business for $200,000 cash.
January 8
The corporation purchased inventory costing $200,000 by paying $120,000 in cash. The remainder was put on credit accounts with suppliers.
January 15
The corporation hired five employees. Each employee will be paid $1,000 at the end of each month.
January 30
The corporation paid $6,000 cash for a one-year insurance policy. The policy period will begin on February 1, Year 1.
What will be the impact of the January 1 event on the company's balance sheet on that date, along with an increase to cash of $900,000?
Answer: C
Explanation:
The correct answer is A. Stockholders' equity will increase by $900,000 . On January 1, the corporation received cash in exchange for issuing stock. That means the company's assets increase because cash increases, and stockholders' equity also increases because ownership shares were issued. OpenStax explains that when a company issues stock for cash or other assets, the asset account increases and the related equity accounts are credited.
Option B is incorrect because no borrowing occurred on January 1, so loan payable does not increase from that event. Option C is incorrect because "investments" is not the proper classification for the corporation's own issuance of stock in this context. Option D is incorrect because retained earnings increase from profitable operations over time, not from owner contributions or stock issuances. This transaction is a classic example of the accounting equation staying balanced: Assets increase by $900,000 and Stockholders' Equity increases by $900,000 . Therefore, the correct balance sheet effect, along with the rise in cash, is an equal increase in stockholders' equity .
NEW QUESTION # 48
Which technique describes the practice of incurring debt but fully paying the debt over time?
Answer: A
Explanation:
The best answer is B. Liability deferral . Among the choices provided, this is the only option that relates to a liability-based arrangement in which an obligation is incurred and then settled over time. In accounting, debt that is taken on and repaid through scheduled installments is generally treated as a liability until it is extinguished through repayment. Repaying principal over time is commonly described in finance as amortization of debt principal , meaning the borrower fully pays the debt in installments over a period of time.
The other options do not fit this meaning. Income smoothing refers to managing the pattern of reported earnings to reduce fluctuations between periods, not simply borrowing and repaying debt. "Profit control" and
"accounting management" are not standard terms for the repayment of debt over time in basic accounting frameworks. Because the question asks for the option that best matches the idea of incurring debt and then paying it off over time, Liability deferral is the most appropriate answer from the choices given, even though
"debt amortization" would be the more standard term in practice.
NEW QUESTION # 49
......
Pass4guide designed this prep material to help you pass the exam on the first try. It may sound complicated, but once you go through regular study and intensive practice, passing the final exam would be a piece of cake. The cost of WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) certification itself is expensive, ranging from $100 to $1000, so you can't risk wasting that amount. Pass4guide ensures that this does not happen by providing you with reliable and updated preparation material.
Accounting-for-Decision-Makers Practice Exam Questions: https://www.pass4guide.com/Accounting-for-Decision-Makers-exam-guide-torrent.html
P.S. Free 2026 WGU Accounting-for-Decision-Makers dumps are available on Google Drive shared by Pass4guide: https://drive.google.com/open?id=1F64wYQV3Z7bNxDzCHJhmKHGrsKAiJauj