If you buy the Exam4Labs's products, we will not only spare no effort to help you pass the certification exam, but also provide a free update and upgrade service. If the official change the outline of the certification exam, we will notify customers immediately. If we have any updated version of test software, it will be immediately pushed to customers. Exam4Labs can promise to help you succeed to pass your first CSI Certification AFP-Exam-1 Exam.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Technical Competencies | 84% | - Retirement Planning - Asset and Liability Management - Investment Planning - Tax Planning - Estate Planning - Risk Management and Insurance |
| Topic 2: Enabling Competencies | 16% | - Client Relationship and Practice Management - Professional Conduct and Regulatory Compliance |
>> New AFP-Exam-1 Exam Review <<
Exam4Labs AFP-Exam-1 exam preparation begins and ends with your accomplishing this credential goal. Although you will take each AFP-Exam-1 online test one at a time - each one builds upon the previous. Remember that each AFP-Exam-1 Exam Preparation is built from a common certification foundation.AFP-Exam-1 prepareation will provide the most excellent and simple method to pass your AFP-Exam-1 Certification Exams on the first attempt.
NEW QUESTION # 100
Ali wishes to retire in five years. His financial planner calculates that he needs to save an additional $40,000 to meet his retirement income objectives. What would Ali's financial planner advise him to do in order to meet his retirement income objectives?
Answer: C
Explanation:
With only five years until retirement, Ali's planner should recommend reducing current expenses and redirecting the freed cash flow to retirement savings. The short time horizon makes aggressive corrective strategies dangerous. Borrowing through a mortgage to invest introduces leverage risk and could worsen retirement security if markets underperform. Increasing equity exposure solely to chase a higher return may be inconsistent with the time horizon and risk capacity. Whole life insurance is not an efficient solution for a near-term retirement savings shortfall; it combines insurance and investment features but does not directly solve a five-year funding gap. Expense reduction is controllable, immediate, and aligned with the identified
$40,000 savings need. The planner should quantify how much monthly savings is required and monitor progress annually. Study Guide focus: retirement shortfall strategies, savings rate, time horizon, risk capacity, leverage risk, and expense management. The recommendation is conservative because the closer the retirement date, the less time Ali has to recover from investment error.
NEW QUESTION # 101
A client says she can emotionally tolerate a 30% portfolio decline, but she needs the money in 18 months for a home down payment and has no other savings. What should the planner conclude?
Answer: A
Explanation:
The planning distinction is between risk tolerance and risk capacity. Risk tolerance is the client's psychological comfort with volatility. Risk capacity is the financial ability to withstand loss without jeopardizing a goal. Here, the funds have a short, specific time horizon and no substitute source. A 30% decline shortly before the home purchase could make the goal impossible. Option A confuses willingness with suitability. Option B is incomplete because experience matters, but goal timing and liquidity dominate this case. Option D is irrelevant to the core issue; taxes do not override capital preservation when funds are needed in 18 months. A course-guide analysis would recommend a liquid, low-volatility vehicle such as a high- interest savings account, short-term GIC ladder if timing allows, or money market-type solution, depending on guarantees and access. The planner must document why the client's emotional tolerance does not justify exposing goal-critical capital to equity volatility. References/topics: risk capacity, time horizon, liquidity, goal-based investing.
NEW QUESTION # 102
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: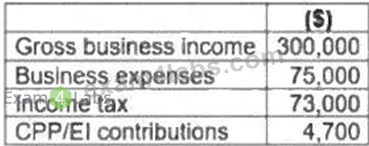
What is Terry's net business income?
Answer: D
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 103
At the first meeting, a financial planner explains her services, compensation, responsibilities, limitations, confidentiality practices, and what information the client must provide. Which document should normally capture these matters?
Answer: B
Explanation:
The client agreement letter establishes the engagement framework. It is not a product disclosure document and it is not the financial plan itself. Its purpose is to define the business relationship before substantive advice is delivered. A complete engagement letter normally identifies the parties, scope of services, expected deliverables, compensation, conflicts or limitations, confidentiality, client responsibilities, and how implementation or review will occur. Option B is specific to mutual fund disclosure and is provided when a particular fund purchase is being considered or executed. Option C is issued after a transaction and cannot substitute for engagement documentation. Option D may become part of the planning file, but it does not describe the advisory relationship. The strongest practice-management answer is to document expectations early so the client understands what advice is being provided, what is outside scope, how the planner is paid, and what information must be supplied for reliable analysis. References/topics: engagement process, client agreement, scope of service, practice management.
NEW QUESTION # 104
Dianna is visiting with Karen, her Financial Planner, and is excited to report that she has just bought her dream home. She has also let Karen know she Is meeting with an insurance representative to purchase a whole life insurance to cover her 20-year mortgage. Why might Karen suggest Dianna consider term life insurance instead?
Answer: C
Explanation:
Karen's recommendation should match the insurance product to the liability. Dianna's need is temporary: a 20- year mortgage balance that would create financial hardship if she died before the debt was retired. Term life insurance is designed for temporary capital needs and normally provides the largest amount of death benefit for the lowest initial premium because it contains no cash-value savings component. Whole life can be appropriate for permanent estate liquidity, final taxes, charitable objectives, or lifetime dependency needs, but those facts are not present. Option A may be true as a general underwriting concern, but it does not explain why term is better for this mortgage need. Option B is false because term insurance does not build cash value.
Option C describes permanent needs, not a 20-year mortgage. The AFP planning conclusion is that term coverage should be considered where the risk period and capital need are limited. Study Guide focus: needs- based insurance analysis, term versus permanent insurance, mortgage protection, and product suitability.
NEW QUESTION # 105
......
There are three different versions of our AFP-Exam-1 study materials including PDF, App and PC version. Each version has the suitable place and device for customers to learn anytime, anywhere. In order to give you a basic understanding of our various versions, each version offers a free trial. The PDF version of AFP-Exam-1 study materials supports download and printing, so its trial version also supports. You can learn about the usage and characteristics of our AFP-Exam-1 Study Materials in various trial versions, so as to choose one of your favorite in formal purchase. In fact, all three versions contain the same questions and answers.
Certification AFP-Exam-1 Exam: https://www.exam4labs.com/AFP-Exam-1-practice-torrent.html