此外,這些Fast2test PF1考試題庫的部分內容現在是免費的:https://drive.google.com/open?id=18qszc54UmoJXDboJA-M7fivfWdRgy36z
在近幾年,IT世界的競爭越來越激烈,IT認證已經成為該行業的必需品,如果你想在你的職業生涯有一個很好的提升,通過Fast2test National Payroll Institute的PF1考試培訓資料這種方式來獲得微軟認證的證書是非常可行的,現在許多IT專業人士更願意增加National Payroll Institute的PF1考試認證對他們的憑證,我們的培訓資料涵蓋了通過National Payroll Institute的PF1考試認證的100%。
| Section | Weight | Objectives |
|---|---|---|
| Record of Employment (ROE) | 20% | - ROE completion requirements
|
| Termination and Special Payments | 30% | - Leaves and absences
|
| Communication and Compliance | 10% | - Stakeholder communication
|
| Individual Pay Calculations | 40% | - Regular earnings
|
>> National Payroll Institute PF1最新考證 <<
在Fast2test的幫助下,你不需要花費大量的金錢參加相關的補習班或者花費很多時間和精力來復習相關知識就可以輕鬆通過考試。National Payroll Institute PF1考試軟體是Fast2test研究過去的真實的考題開發出來的。Fast2test提供的National Payroll Institute PF1考試練習題和答案和真實的考試練習題和答案有很大的相似性。
問題 #38
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
STATUTORY DEDUCTIONS
OTHER DEDUCTIONS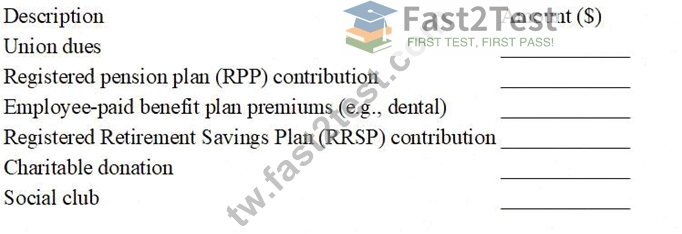

Given Data (Reference)
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
答案:
解題說明:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
問題 #39
When is the government-prescribed rate of interest set?
答案:B
解題說明:
The CRA's prescribed interest rates are established for specific periods labelled by calendar quarter (for example, "first calendar quarter 2026"), and CRA publishes the rate schedule by quarter.
This prescribed rate is used in multiple tax contexts, including calculating taxable benefits on certain interest- free or low-interest employee/shareholder loans, and it also relates to interest charged/paid by the CRA on overdue amounts and overpayments (with different rates for different situations).
Because CRA's publication is organized and effective by quarter (e.g., Jan 1-Mar 31; Apr 1-Jun 30; Jul 1- Sep 30; Oct 1-Dec 31), the correct answer is each calendar quarter (option D), not monthly, semi-annual, or annual.
問題 #40
A 900-series Social Insurance Number is issued to:
答案:B
解題說明:
A SIN that begins with "9" (often called a 900-series SIN) is issued to temporary workers-people who are neither Canadian citizens nor permanent residents-and who are authorized to work in Canada. Service Canada's employer guidance explicitly states that SINs beginning with "9" are issued to temporary workers who are neither Canadian citizens nor permanent residents, and these SINs are valid only until the expiry date shown on the immigration document that authorizes the person to work in Canada.
Service Canada also advises employers to confirm that employees with a SIN starting with "9" remain authorized to work and that their immigration document has not expired.
So, options A-C are incorrect because a 900-series SIN is not for permanent residents ("landed immigrants"), not for Canadians whose SIN "expires," and not based on working outside Canada. It specifically signals temporary status tied to work authorization in Canada.
問題 #41
What information is required to calculate thestandby charge, thereduced standby charge, and theoperating cost benefitfor a company-owned automobile?
答案:B
解題說明:
CRA's automobile benefit calculations require multiple data points because there are usuallytwo components thestandby charge(vehicle availability) and theoperating expense benefit(personal driving where the employer pays operating costs). CRA's guidance on employer-provided automobiles explains that standby charge calculations use the automobile'scost (capital cost) including applicable taxesand the time the vehicle wasavailableto the employee, while the reduced standby charge and operating benefit depend on kilometres drivenand the split betweenbusiness and personal use.
To determine whether areduced standby chargeapplies, you need availability plusbusiness-use requirements(which are evidenced through total/business kilometres). To calculate the operating expense benefit, you needpersonal kilometres(often derived from total kilometres minus business kilometres) or detailed personal km directly.
Therefore, the complete and correct set of required inputs is:capital cost (with sales tax), availability, total kilometres, business kilometres, and personal kilometres-which is optionD.
問題 #42
Select the correct order of priority for withholding payroll deductions from an employee's earnings.
答案:A
解題說明:
Payroll deductions are typically applied in a priority order to ensure the employer meets mandatory legal obligations first and avoids creating liability. Standard Canadian payroll training materials commonly present five categories withheld in this order: (1) statutory deductions, (2) legal deductions, (3) union deductions, (4) company-compulsory deductions, and (5) voluntary deductions.
Statutory deductions (CPP/QPP, EI, income tax, and where applicable NWT/Nunavut payroll tax) have top priority because employers are legally required to deduct and remit them.
Legal deductions (such as CRA requirements to pay/garnishments) are next because they are enforced by law and can create employer liability if not followed.
Union deductions follow where required by a collective agreement.
Company-compulsory deductions (for example, required benefit premiums) come after those.
Voluntary deductions (charity, savings plans, etc.) are last and only taken if funds remain.
Therefore, option D is the correct order.
問題 #43
......
我們都是平平凡凡的普通人,有時候所學的所掌握的東西沒有那麼容易徹底的吸收,所以經常忘記,當我們需要時就拼命的補習,當你看到Fast2test National Payroll Institute的PF1考試培訓資料是,你才明白這是你必須要購買的,它可以讓你毫不費力的通過考試,也可以讓你不那麼努力的補習,相信Fast2test,相信它讓你看到你的未來美好的樣子,再苦再難,只要Fast2test還在,總會找到希望的光明。
PF1考題寶典: https://tw.fast2test.com/PF1-premium-file.html
P.S. Fast2test在Google Drive上分享了免費的2026 National Payroll Institute PF1考試題庫:https://drive.google.com/open?id=18qszc54UmoJXDboJA-M7fivfWdRgy36z