BTW, DOWNLOAD part of ITdumpsfree ClaimCenter-Business-Analysts dumps from Cloud Storage: https://drive.google.com/open?id=1IB7ItHzIDRbilAWCu7A5lyZ69Zppeeph
We offer you free update for 365 days after you purchase ClaimCenter-Business-Analysts study materials from us, so that you don’t need to spend extra money for the update version. And the update version for ClaimCenter-Business-Analysts study materials will be sent to your email address automatically. You just need to check your mail when you need the update version. Besides ClaimCenter-Business-Analysts Study Materials are edited by professional experts, they are quite familiar with the dynamics of the exam center. Therefore if you choose ClaimCenter-Business-Analysts study materials of us, we will help you pass the exam and get the certificate successfully.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
>> ClaimCenter-Business-Analysts Actual Questions <<
Our clients come from all around the world and our company sends the products to them quickly. The clients only need to choose the version of the product, fill in the correct mails and pay for our ClaimCenter Business Analyst - Mammoth Proctored Exam guide dump. Then they will receive our mails in 5-10 minutes. Once the clients click on the links they can use our ClaimCenter-Business-Analysts Study Materials immediately. If the clients can’t receive the mails they can contact our online customer service and they will help them solve the problem. Finally the clients will receive the mails successfully. The purchase procedures are simple and the delivery of our ClaimCenter-Business-Analysts study tool is fast.
NEW QUESTION # 30
A performing arts organization operates nationwide and is responsible for setting up stages for musical acts and concerts. The organization requires specific insurance coverage for its gear and equipment, including audio systems, lighting, cameras, and control boards. Succeed Insurance wants to optimize claim intake, processing, and reporting for this organization.
Which modifications should be made to ClaimCenter's base product line of business (LOB)?
Answer: C
Explanation:
According to the Guidewire ClaimCenter Business Analyst documentation, ClaimCenter's line of business (LOB) framework is intentionally designed to support extensibility through configuration rather than structural changes to core policy or loss classification elements. When an insurer needs to support specialized insured property-such as professional audio, lighting, and staging equipment-the recommended approach is to enhance the coverage configuration.
ClaimCenter models policy coverage using a hierarchy ofCoverageTypeandCoverage Subtypetypelists.
CoverageType codes represent high-level coverage categories defined by the policy, while Coverage Subtype codes allow insurers to further refine and classify coverage details. These coverage elements are then associated withExposureTypecodes, which drive claim processing behavior such as exposure creation, reserving, payment handling, and reporting.
By adding appropriate CoverageType and Coverage Subtype codes for equipment and gear coverage and mapping them to ExposureType codes, ClaimCenter can automatically create accurate exposures during claim intake. This approach ensures adjusters can efficiently process claims while maintaining consistent workflows and financial controls. It also supports meaningful analytics and reporting without altering the base product structure.
The Guidewire documentation advises against introducing newLossTypeorPolicyTypecodes unless the insurer is defining an entirely new policy or loss classification. LossType codes describe how a loss occurred (for example, theft or accidental damage), not the nature of the insured property. PolicyType changes are similarly broad and unnecessary for extending coverage within an existing LOB.
Therefore, optionBaligns with Guidewire best practices by extending ClaimCenter's coverage and exposure configuration to meet the organization's needs while preserving the integrity of the standard LOB model.
NEW QUESTION # 31
Succeed Insurance has plans to expand operations in Greeley, Colorado. Due to a history of hailstorm related damage in the area, the company plans to offer reimbursement for hail damage as an option.
Which two actions should the Business Analyst (BA) take to determine the requirements for the project?
(Choose two.)
Answer: B,C
Explanation:
In the Guidewire delivery methodology, the "Determine Requirements" phase (often part of Inception or Elaboration) focuses on understanding the business need and mapping it to the software capabilities.
* Lead an Elaboration Workshop (A):TheElaboration Workshopis the primary forum where BAs engage with stakeholders (like the Greeley operations team) to discuss the specific needs for the new
"hail damage" product. This is where the raw requirements are gathered, discussed, and refined.
* Recommend Base Product Features (B):A critical responsibility of the Guidewire BA is to maximize product value by reducing unnecessary customization. When determining requirements for
"reimbursement" and "hail damage," the BA should immediately demonstrate and recommend how ClaimCenter's out-of-the-box Coverage, Exposure, and Incident features can handle this scenario. This aligns the customer's expectations with the standard software capabilities, expediting the implementation.
* Why not C or D?Authoring user stories (C) and defining typelists (D) areoutputsortasksthat occurafter the requirements have been determined and the solution approach (Standard vs. Custom) has been agreed upon.
NEW QUESTION # 32
Succeed Insurance requires that a new 'Driver under 18?' field be added to the vehicle incident screen for personal auto claims to indicate whether or not the driver of the vehicle was a minor when the loss occurred.
The field will be set by calculating the driver's age using the date of loss and the driver's date of birth.
There are two validation requirements:
* The field must be set if the 'Date of Birth' field for the driver is not null.
* No payments can be made for collision exposures if the 'Date of Birth' field for the driver of the vehicle is null.
A Business Analyst (BA) documents the validation requirements in the validation tab of the User Story Card
'Adjudicate - Update Maintain Vehicle Incident for Personal Auto Claims' as shown in the exhibit.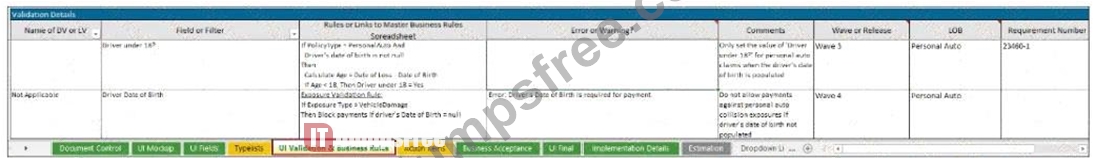
What information in the two validation examples is either missing or incorrectly documented? (Choose two.)
Answer: B,C
Explanation:
The User Story Card exhibit contains several documentation errors when compared to standard Guidewire requirements gathering best practices and the specific scenario provided.
* Missing Requirement Number and Logic Gap (Option C):
* Traceability:In the second row of the exhibit (the payment validation rule), the "Requirement Number" column is completely blank. Traceability back to the original requirements document is mandatory for all entries.
* Logic Precision:The requirement explicitly states that the rule applies to"personal auto claims"
. However, the logic documented in the "Rules" column (If Exposure Type = VehicleDamage Then Block...) doesnotcheck the Policy Type. It relies solely on the Exposure Type, which could exist on Commercial Auto policies as well. To accurately reflect the business requirement, the condition If PolicyType = Personal Auto must be added (similar to how it was done in the first row).
* Missing DV/LV Context for Validation (Option D):
* UI Anchoring:The second requirement is a validation rule that triggers an error ("Driver's Date of Birth is required..."). For the system to highlight the specific field on the screen (the "Driver Date of Birth" widget) when the error occurs, the rule must be associated with the specificDetail View (DV)orList View (LV)where that field resides (e.g., VehicleIncidentDV). The exhibit lists
"Not Applicable" in the "Name of DV or LV" column. This is incorrect because providing the DV name ensures the error message is displayed contextually next to the field rather than as a generic page-level error, improving the user experience.
Why other options are incorrect:
* Option A:The LOB column is used for filtering, reporting, and release management. Even if the rule logic checks the policy type, the LOB column is required metadata and should not be removed.
* Option B:While the first requirement (the calculation) lacks a DV name (which it should have), it is a Business Rule(assignment), not a validation. Therefore, it doesnotgenerate an error or warning message for the user, so the second part of Option B is incorrect.
* Option E:The "Rules" column is exactly where the calculation logic (Date of Loss - Date of Birth) belongs. The developer needs this information to implement the automation.
NEW QUESTION # 33
Succeed Insurance allows field Adjusters to write checks directly to the insured to cover damage costs for minor claims such as:
* Personal auto claims involving cracked windshields
* Homeowners claims involving minor glass breakage
The Adjuster uses the Manual Check Wizard to record the check number and amount against a reserve line.
Succeed requires Supervisor approval for all manual checks to ensure that the paper checks are verified against the payment information in ClaimCenter.
Which two limits or rules must be configured in ClaimCenter to ensure that these manual payments are sent to the correct person for approval? (Choose two.)
Answer: B,C
Explanation:
To enforce an approval workflow for a specific type of financial transaction (like "Manual Checks") regardless of the dollar amount, a Business Analyst must leverage both Authority Limits and Transaction Approval Rules.
* Authority Limits (D):These are the primary controls for financial exposure. While typically used for amounts (e.g., "Limit of $5,000"), they are the foundational mechanism that triggers the system's
"Pending Approval" state. For this scenario, an authority limit could be set to $0 for the specific payment method of "Manual Check" to force all such payments into the approval workflow.
* Transaction Approval Rules (C):These rules allow for more granular, logic-based approval triggers beyond simple amounts. Since the requirement specifies "all manual checks" (implying a condition based on themethodof payment, not just the amount), aTransaction Approval Ruleis the best practice configuration. The rule would be written to state:"If Payment Method is Manual, then Approval is Required."
* Why not A (Approval Routing)?While Approval Routing rules determinewhoreceives the request (the
"correct person"), the default behavior in ClaimCenter is to route approvals to the user's Supervisor.
Since the requirement is simply "Succeed requires Supervisor approval," the standard routing logic likely suffices without needing new custom configuration. The critical configuration needed is the trigger(C and D) to stop the payment in the first place.
NEW QUESTION # 34
To optimize business process workflow, an insurer has spent a great deal of effort on estimating the amount of effort required to complete various types of work... They are also aware that certain situations may require specialized expertise and want to incorporate this in their decision making.
All claims and exposures are entered using only the ClaimCenter new claim wizard. Once entered, the work should be automatically distributed fairly to those properly suited, as determined by the company's knowledge of each worker's skill set.
Which two assignment mechanisms, alone or together, will achieve their goal? (Choose two.)
Answer: A,C
Explanation:
To meet the dual requirements of "specialized expertise" and "fair distribution based on effort," the Business Analyst should utilize User Attributes and Weighted Workload assignment rules.
* User Attributes (Option B):This feature handles the "specialized expertise" requirement.
Administrators can tag users with specific attributes (e.g., "Bilingual," "Heavy Equipment Expert,"
"Litigation Specialist"). Assignment rules can then be configured to filter the pool of potential assignees toonlythose who possess the matching attribute for the specific claim type.
* Weighted Workload (Option D):This feature handles the "fair distribution" and "amount of effort" requirement. Unlike Round-robin (which treats all claims as equal), Weighted Workload assigns a
"weight" (effort points) to the claim and tracks the "load factor" (current capacity) of the user. The system assigns the new work to the user with the lowest relative workload, ensuring that adjusters handling difficult, high-effort claims are not overwhelmed with the same volume as those handling simple claims.
Why other options are incorrect:
* Round-robin (A):Distributes work purely cyclically (1-2-3-1-2-3) without regard for the user's current workload or the complexity of the claim.
* FNOL Queues (C):This is a "pull" mechanism where work sits in a bucket until someone grabs it, rather than the "automatic distribution" (push) requested.
* Supervisor Assignment (E):This is manual, not automatic.
NEW QUESTION # 35
......
To help you get to know the exam questions and knowledge of the ClaimCenter-Business-Analysts practice exam successfully and smoothly, our experts just pick up the necessary and essential content in to our ClaimCenter-Business-Analysts test guide with unequivocal content rather than trivia knowledge that exam do not test at all. To make you understand the content more efficient, our experts add charts, diagrams and examples in to ClaimCenter-Business-Analysts Exam Questions to speed up you pace of gaining success. Up to now, more than 98 percent of buyers of our ClaimCenter-Business-Analysts latest dumps have passed it successfully. Up to now they can be classified into three versions: the PDF, the software and the app version. So we give emphasis on your goals, and higher quality of our ClaimCenter-Business-Analysts test guide.
New ClaimCenter-Business-Analysts Test Pattern: https://www.itdumpsfree.com/ClaimCenter-Business-Analysts-exam-passed.html
BTW, DOWNLOAD part of ITdumpsfree ClaimCenter-Business-Analysts dumps from Cloud Storage: https://drive.google.com/open?id=1IB7ItHzIDRbilAWCu7A5lyZ69Zppeeph