Nowadays everyone is interested in the field of CSI because it is growing rapidly day by day. The Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) credential is designed to validate the expertise of candidates. But most of the students are confused about the right preparation material for AFP-Exam-1 Exam Dumps and they couldn't find real AFP-Exam-1 exam questions so that they can pass CSI AFP-Exam-1 certification exam in a short time with good grades.
| Section | Weight | Objectives |
|---|---|---|
| Enabling Competencies | 16% | - Professional Conduct and Regulatory Compliance - Client Relationship and Practice Management |
| Technical Competencies | 84% | - Risk Management and Insurance - Estate Planning - Asset and Liability Management - Investment Planning - Tax Planning - Retirement Planning |
Usually, the questions of the real exam are almost the same with our AFP-Exam-1 exam questions. So you just need to memorize our correct questions and answers of the AFP-Exam-1 study materials. You absolutely can pass the exam. Also, we will offer good service to add you choose the most suitable AFP-Exam-1 Practice Braindumps since we have three different versions of every exam product. And you can free download the demos of the AFP-Exam-1 learning quiz.
NEW QUESTION # 39
Leena and Harry are married and hold RRSPs with a value exceeding $500,000. They are concerned about their final tax liability and want to cover the taxes after they have both died. What would their financial planner recommend them to implement in order for the couple to achieve the objective?
Answer: C
Explanation:
A joint last-to-die permanent life insurance policy is designed for a tax liability that arises after both spouses have died. Leena and Harry are concerned about the final tax exposure on large RRSP balances. If one spouse dies first and the surviving spouse is the beneficiary or successor annuitant, RRSP/RRIF amounts may generally roll to the survivor on a tax-deferred basis. The larger tax problem usually appears on the second death, when no spouse remains for rollover and the registered assets are included in income. Last-to-die coverage pays at that point and can provide estate liquidity for taxes without forcing asset sales. A testamentary trust does not itself fund the tax bill. Updating beneficiaries to each other helps deferral but not the final liability. An inter vivos trust cannot simply receive RRSP assets without tax consequences. Study Guide focus: RRSP/RRIF death taxation, spousal rollover, permanent insurance, estate liquidity, and last-to- die planning.
NEW QUESTION # 40
Justis, age 62, and his wife Jen, age 58, are meeting with their financial planner, Luke. They are both planning to retire by age 65. Their goals are to minimize debt and reduce taxes. The couple's financial situation is outlined below.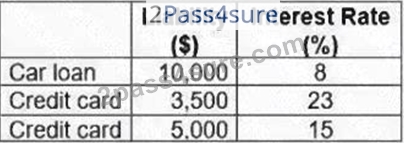
Justis' annual income is $25,000. He has a $15,000 RRSP, $30,000 single non-registered account and a
$25,000 TFSA. Jen's annual income is $60,000, and she has a $150,000 RRSP, $50,000 single non-registered account and a $20,000 TFSA.
Jen's marginal tax rate is 35%, and Justis' is 25%. Assuming all investments are making interest income of
10%, what would be the most appropriate strategy for Luke to recommend for the couple?
Answer: D
Explanation:
Luke should recommend using Jen's non-registered funds because that option clears the liabilities without triggering registered-plan withdrawal income. The debts total $18,500 and include expensive consumer borrowing: credit cards at 23% and 15%, plus a car loan at 8%. The couple's taxable investments earn 10% interest before tax, so Jen's after-tax return is approximately 6.5% at a 35% marginal rate. Paying the credit cards is equivalent to earning a risk-free after-tax return equal to the interest avoided, which is materially better than leaving the money invested. Using either spouse's RRSP would create taxable income and permanently reduce retirement capital. Using Justis's non-registered funds is less effective because his lower tax rate makes his after-tax investment return higher than Jen's, so Jen's taxable account is the better source.
Study Guide focus: debt repayment priority, after-tax returns, registered versus non-registered withdrawals, and household cash-flow planning. The recommendation also preserves retirement accounts for the couple's age-65 objective while eliminating the highest-cost liabilities first.
NEW QUESTION # 41
A client, age 60, is in a low tax bracket today and expects a larger taxable pension after age 65. She has TFSA and RRSP room. Which contribution priority is generally more appropriate?
Answer: D
Explanation:
The contribution decision turns on current versus future tax rates and the effect on retirement income. RRSP contributions are most powerful when the deduction is taken at a higher tax rate than the withdrawal rate. If the client is in a low bracket now and expects higher taxable income later, the RRSP deduction may be less valuable than the future tax cost. A TFSA provides no deduction, but qualified withdrawals are tax-free and do not increase taxable income or income-tested benefit exposure. Option A is incorrect because RRSP withdrawals are taxable. Option B ignores tax-sheltered growth and flexibility. Option D is impossible in ordinary RRSP planning because RRSPs must be matured by the end of the year the annuitant turns 71. The planner should still test exact brackets, pension timing, OAS exposure, available cash flow, and estate objectives. As a general rule in this fact pattern, TFSA priority is more defensible. References/topics: TFSA vs RRSP, marginal tax rate planning, retirement cash flow, income-tested benefits.
NEW QUESTION # 42
Jenny and Herman are looking for tax strategies that will help them better manage their marginal annual tax rates. Jenny is currently the primary income earner in the household. She has a large non-registered portfolio that holds only plain vanilla S & P 500 index funds. Jenny and Herman have a 14-year-old daughter, and they would also like to know what income-splitting opportunities exist. They've presented several ideas to their tax planner, Isaac, for review. Which of the following will likely result in tax attribution to Jenny?
Answer: A
Explanation:
Jenny's gift to her minor daughter is the transaction most likely to trigger attribution back to Jenny. When a high-income parent transfers income-producing property to a minor child, income such as interest and dividends generally attributes back to the parent. The rule prevents simple income splitting by gift. A spousal RRSP converted to a RRIF can avoid attribution on required minimum RRIF withdrawals, subject to detailed timing rules. A sale of securities to Herman at fair market value can avoid attribution if proper consideration is paid and the transaction is documented. A prescribed-rate loan to Herman can also avoid attribution if interest is charged at the prescribed rate and paid by the required deadline. The key AFP issue is distinguishing prohibited income splitting from properly structured transfers or loans. The minor-child gift in option A is the clearly attributive arrangement. Study Guide focus: attribution rules, minor children, spousal transfers, prescribed-rate loans, and family tax planning.
NEW QUESTION # 43
Rob, age 42, is married with three children in elementary school. He works as an operations supervisor at a small manufacturing company, earning $70,000 annually. Rob asks his financial planner, Wendy, to liquidate his GIC investments worth $55,000 in order to use the sale proceeds to purchase a gold stock referred to him by his friend who expects the stock to appreciate significantly. Rob has not purchased stock before. What should be Wendy's reaction to Rob's query?
Answer: A
Explanation:
Wendy cannot treat Rob's request as routine order taking. He wants to liquidate $55,000 of GICs and buy a single gold stock based on a friend's expectation of appreciation, while he has a spouse, three young children, and no prior stock-purchasing experience. That is a major change in risk, concentration, liquidity, and suitability. The correct professional response is to review his risk tolerance, risk capacity, time horizon, objectives, investment knowledge, and financial circumstances before implementing or recommending the trade. Refusing the order outright may be unnecessary before analysis, while placing it without inquiry would ignore suitability obligations. Delaying and telling him to think about it is incomplete unless the planner completes the required review and documents the conversation. AFP conduct standards require the planner to slow the process when a proposed transaction conflicts with the known client profile. Study Guide focus:
KYC, suitability, concentration risk, unsolicited instructions, and professional duty of care.
NEW QUESTION # 44
......
There is no doubt that we all dream of working for top companies around the globe. Some people make it through but some keep on thinking about how to break that glass. If you are among those who belong to the latter category, you should start the preparations for the Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) certification exam to improve your knowledge, expertise and crack even the toughest interview easily.
AFP-Exam-1 Study Reference: https://www.2pass4sure.com/Canadian-Securities-Course/AFP-Exam-1-actual-exam-braindumps.html