Our company hired the top experts in each qualification examination field to write the AFP-Exam-1 prepare materials, so as to ensure that our products have a very high quality, so that users can rest assured that the use of our research materials. On the other hand, under the guidance of high quality AFP-Exam-1 research materials, the rate of adoption of the AFP-Exam-1 exam guide is up to 98% to 100%. Of course, it is necessary to qualify for a qualifying AFP-Exam-1 exam, but more importantly, you will have more opportunities to get promoted in the workplace.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Retirement Planning | 17% | - Registered Retirement Savings Plans - Retirement Needs Analysis - Pension Plans - Retirement Income Strategies |
| Topic 2: Asset and Liability Management | 11% | - Budgeting - Debt Management - Cash Flow Management - Personal Balance Sheet Analysis |
| Topic 3: Investment Planning | 17% | - Asset Allocation - Investment Products - Portfolio Construction - Investment Theory |
| Topic 4: Tax Planning | 14% | - Income Tax Fundamentals - Tax Deductions and Credits - Tax-Efficient Strategies - Registered Plans |
| Topic 5: Professional Conduct and Regulatory Compliance | 10% | - Compliance Responsibilities - Ethics and Professional Standards - Regulatory Requirements |
| Topic 6: Risk Management and Insurance | 12% | - Risk Assessment - Disability and Health Insurance - Risk Transfer Strategies - Life Insurance |
| Topic 7: Estate Planning | 13% | - Powers of Attorney - Estate Transfer Strategies - Wills - Trust and Beneficiary Planning |
| Topic 8: Client Relationship and Practice Management | 6% | - Communication and Advisory Process - Client Discovery - Practice Management |
>> AFP-Exam-1 New Test Materials <<
Once you ensure your grasp on the AFP-Exam-1 questions and answers, evaluate your learning solving the AFP-Exam-1 practice tests provided by our testing engine. This innovative facility provides you a number of practice questions and answers and highlights the weak points in your learning. You can improve the weak areas before taking the actual test and thus brighten your chances of passing the AFP-Exam-1 Exam with an excellent score. Moreover, doing these practice tests will impart you knowledge of the actual AFP-Exam-1 exam format and develop your command over it.
NEW QUESTION # 44
Lex's client, Phillip, has signed an agreement to purchase his uncle's business when his uncle retires in five years for $210,000. Phillip has $175,000 today, how should Lex recommend Philip invest his money?
Answer: D
Explanation:
Phillip has a defined liability: $210,000 due in five years. His current capital of $175,000 must compound to the purchase price with minimal uncertainty. A five-year bond yielding 3.75% produces approximately
$210,400 at maturity if held as planned, which aligns the investment term with the obligation and slightly exceeds the required amount. A 3.00% savings account and a 3.50% GIC fall short of the target. An equity mutual fund may have averaged 6.00% historically, but historical average return is not a guarantee and is inappropriate for a fixed five-year contractual obligation where the required amount is known. The AFP rule is that known future liabilities should be matched with suitable maturity, capital certainty, and sufficient expected accumulation. Lex should avoid unnecessary market risk when a fixed-income option already satisfies the goal. Study Guide focus: goal-based investing, time horizon, fixed-income matching, future value, and suitability. The planner should document the maturity date and reinvestment risk because the purchase obligation is contractual, not discretionary.
NEW QUESTION # 45
Janet's non-registered account holds the funds listed in the following table: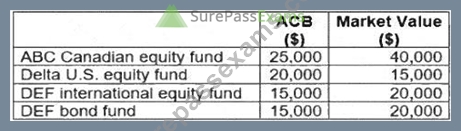
Assuming a marginal tax rate of 45%, what amount of tax payable will Janet incur if she redeems the account to fund the purchase of a new business?
Answer: D
Explanation:
Janet's taxable result comes from the net realized capital gain, not from the total market value redeemed. The ABC Canadian equity fund has a $15,000 gain, the Delta U.S. equity fund has a $5,000 loss, the DEF international equity fund has a $5,000 gain, and the DEF bond fund has a $5,000 gain. Net capital gains are therefore $20,000 after offsetting the Delta loss. Only one-half of the net capital gain is taxable under the standard capital gains inclusion treatment used in AFP-level calculations, producing a $10,000 taxable capital gain. At a 45% marginal tax rate, the tax payable is $4,500. Option A taxes the full net gain; option C and option D reflect incorrect inclusion or arithmetic assumptions. The purpose of the question is to test disposition analysis in a non-registered account and the sequence of gain/loss netting before applying the marginal rate. Study Guide focus: adjusted cost base, fair market value, capital gains inclusion, and non- registered tax planning.
NEW QUESTION # 46
Which statement best distinguishes a defined benefit pension plan from a defined contribution pension plan?
Answer: B
Explanation:
A defined benefit pension plan promises a retirement benefit determined by a formula, commonly based on earnings, service, and an accrual rate. The member can estimate retirement income with greater certainty, subject to plan terms and funding rules. A defined contribution plan specifies contributions to an account; the eventual retirement income depends on contributions, investment returns, fees, annuity rates or withdrawal decisions, and longevity. Option A reverses the distinction. Option C is inaccurate because defined benefit plans are employer-sponsored arrangements with plan governance and funding obligations. Option D is wrong because defined contribution members bear significant investment and longevity risk unless they later purchase an annuity or otherwise transfer risk. For planning purposes, the distinction affects retirement projections, RRSP room through pension adjustments, asset allocation, risk capacity, and income sustainability. A planner must not treat all pensions alike; the type of pension determines both certainty of income and the risks remaining with the client. References/topics: defined benefit plans, defined contribution plans, pension risk, retirement projections.
NEW QUESTION # 47
Clara invested $150,000 with Roper Counsel, a member of CIRO. Her portfolio consists entirely of Canadian mutual funds. Roper Counsel recently became insolvent and declared bankruptcy. Where can Clara seek help to recover her financial losses due to this event?
Answer: A
Explanation:
Clara should seek protection through the Canadian Investor Protection Fund because the firm is a CIRO member and the issue is insolvency of an investment dealer or investment firm with client property potentially missing. CIPF protection is not investment-loss insurance; it does not reimburse normal market declines in mutual funds. It addresses eligible client assets when a member firm becomes insolvent and cannot return property. OSFI supervises federally regulated financial institutions but is not the client compensation fund for this fact pattern. Assuris protects policyholders of member life insurance companies. The former MFDA Investor Protection Corporation has been replaced in the current self-regulatory structure; CIRO-related client asset protection points to CIPF. The planner should explain the difference between product risk, issuer risk, and dealer insolvency. Study Guide focus: regulatory bodies, CIRO, CIPF, client asset protection, and investment dealer insolvency. The client should be directed to the fund's eligibility process and advised that ordinary mutual fund market losses remain outside coverage.
NEW QUESTION # 48
Robert is meeting with his wealth advisor to review options to put a plan in place to save for his children's education. He has a daughter, age seven, and a disabled son, age four Robert would like to maximize his savings towards this goal, ensure the strategy is tax efficient and utilize available grants. Which option is most appropriate for Robert's plan?
Answer: C
Explanation:
A family RESP is the most appropriate education savings structure for Robert's two children. It permits multiple related beneficiaries and provides flexibility if one child does not use all of the education funding.
Contributions can attract available education savings grants, and growth is tax-deferred until paid as educational assistance payments. A group RESP is less flexible and may impose restrictions that are not ideal for a family with different education paths. Individual RESPs can work, but they reduce the ability to shift unused resources between siblings compared with a family plan. An education-purpose trust lacks the RESP grant structure and tax treatment. The disabled son's broader planning may also require RDSP analysis, but that option is not offered and does not replace RESP education funding. The planner should confirm grant limits, contribution limits, beneficiary eligibility, and withdrawal rules. Study Guide focus: RESPs, family plans, education grants, tax-deferred education savings, and beneficiary flexibility.
NEW QUESTION # 49
......
You can choose the number of Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) questions and time frame of the AFP-Exam-1 Desktop practice exam software as per your learning needs. Performance reports of CSI AFP-Exam-1 Practice Test will be useful for tracking your progress and identifying areas for further study.
Exam AFP-Exam-1 Learning: https://www.surepassexams.com/AFP-Exam-1-exam-bootcamp.html