WGU Financial-Management Dumps von Pass4Test sind ganz gleich wie die richtigen Zertifizierungsprüfungen. Die beinhalten alle Prüfungsfragen und Testantworten in aktueller Prüfung. Und die Software-Version simuliert die gleiche Atmosphäre der aktuellen Prüfungen. Bei der Nutzung der Pass4Test Dumps, können Sie ganz sorglos die WGU Financial-Management Prüfung ablegen und sehr gute Note bekommen.
| Section | Objectives |
|---|---|
| Topic 1: Time Value of Money | - Annuities and perpetuities - Present and future value calculations |
| Topic 2: Financial Statement Analysis | - Financial ratios - Cash flow analysis - Balance sheet and income statement interpretation |
| Topic 3: Cost of Capital and Valuation | - Bond and stock valuation basics - Weighted average cost of capital (WACC) |
| Topic 4: Capital Budgeting | - Net present value (NPV) - Internal rate of return (IRR) - Payback period analysis |
| Topic 5: Risk and Return | - Portfolio risk and diversification - Expected return |
>> Financial-Management Online Tests <<
Pass4Test ist eine Website, die den Traum vielen IT-Fachleuten erfüllen kann. Wenn Sie einen IT-Traum haben, dann wählen Sie doch Pass4Test. Die Fragenkataloge zur WGU Financial-Management Zertifizierungsprüfung von Pass4Test sind von vielen IT-Fachleuten begehrt, die Ihnen helfen, die Financial-Management Zertifizierung zu bestehen und im Berufsleben befördert zu werden.
65. Frage
What is the significance of Section 302 of the Sarbanes-Oxley Act (SOX)?
Antwort: A
Begründung:
Section 302 of the Sarbanes-Oxley Act requires a company's chief executive officer (CEO) and chief financial officer (CFO) to personally certify the accuracy and completeness of financial statements and disclosures. This certification affirms that management is responsible for establishing and maintaining effective internal controls and has evaluated their effectiveness. The provision was introduced to enhance accountability and restore investor confidence following major accounting scandals. By placing legal responsibility directly on senior executives, Section 302 strengthens corporate governance and reduces the likelihood of fraudulent reporting. Financial management and governance literature consistently highlight this section as a cornerstone of SOX compliance. Option A accurately reflects its purpose.
66. Frage
What is the purpose of the Sarbanes-Oxley Act requirement for the board of directors to effectively represent shareholders?
Antwort: C
Begründung:
The Sarbanes-Oxley Act reinforces the board of directors' fiduciary duty to act in the best interests of shareholders. This includes providing independent oversight of management, ensuring financial reporting integrity, and protecting shareholder rights. SOX emphasizes board independence, particularly through audit committees composed of independent directors. Financial management theory recognizes the board as a key mechanism for reducing agency conflicts between management and shareholders. Option D correctly reflects this governance-focused objective.
67. Frage
What is a limitation of historical mean returns when estimating the cost of common equity?
Antwort: B
Begründung:
A limitation of using historical mean returns to estimate the cost of common equity is that past performance may not accurately reflect future investor expectations or future market conditions. Historical averages are backward-looking measures. They summarize what returns were earned over a past period, but they do not directly account for changing economic conditions, shifts in interest rates, changes in business risk, new competition, or revised growth expectations. Because the cost of equity is a forward-looking required return, relying only on historical mean returns can produce misleading estimates if the future differs materially from the past. Choice C is correct because it identifies the main weakness: historical returns may ignore current market conditions and future prospects. Choice A is incorrect because historical returns are usually straightforward to calculate. Choice B describes a dividend-based model, not a historical-return approach.
Choice D is also incorrect because the limitation is not that the method only applies to large firms. Financial managers often compare historical-return estimates with other methods, such as CAPM or dividend-growth approaches, to form a more balanced estimate of the cost of equity. Therefore, C is the correct answer.
========
68. Frage
Why might a firm's net income not equal its cash flows from operations for a period?
Antwort: C
Begründung:
Net income and cash flow from operations are not the same because net income is prepared using accrual accounting, while cash flow from operations focuses on actual cash movement. Under accrual accounting, revenue may be recorded when earned rather than when cash is received, and expenses may be recorded when incurred rather than when cash is paid. In addition, net income includes noncash expenses such as depreciation and amortization, which reduce accounting profit without reducing current-period cash. Changes in working capital accounts, such as accounts receivable, inventory, and accounts payable, also create differences between net income and operating cash flow. For example, a company may report strong sales and net income, but if many customers have not yet paid, cash flow from operations may still be low. Financial statement analysis places strong emphasis on understanding these differences because cash flow is essential for liquidity, debt repayment, and ongoing operations. Choice A is correct because it directly captures the main reasons net income and cash flow from operations differ. The other choices incorrectly describe the purpose or nature of net income and cash flow reporting.
========
69. Frage
Use Whole Pine Inc.'s financial statements for 20X3 below to answer the following question.
What is Whole Pine Inc.'squick ratiofor 20X3?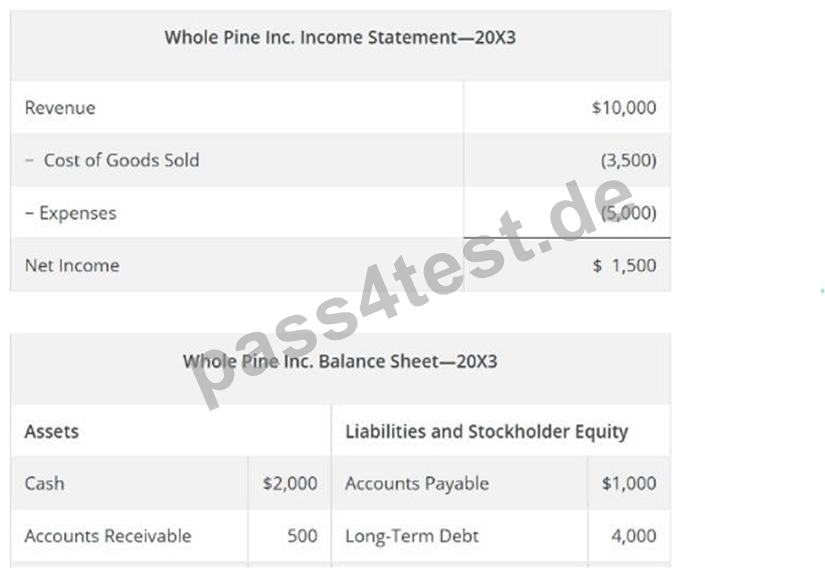
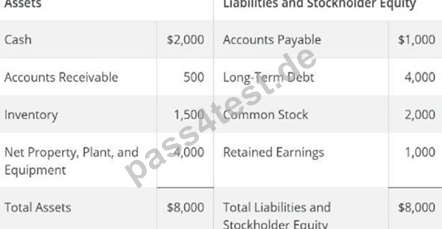
Antwort: C
Begründung:
The quick ratio, also known as the acid-test ratio, measures a firm's ability to meet short-term obligations using its most liquid assets. It is calculated as:
(Cash + Accounts Receivable + Marketable Securities) ÷ Current Liabilities.
For Whole Pine Inc., quick assets include cash of $2,000 and accounts receivable of $500, totaling
$2,500. Inventory is excluded because it is less liquid and may not be easily converted into cash.
Current liabilities consist of accounts payable of $1,000. Dividing $2,500 by $1,000 yields a quick ratio of 2.50. This indicates that the firm has $2.50 in highly liquid assets for every $1.00 of short-term obligations, suggesting strong short-term liquidity. Option C correctly reflects this calculation and interpretation.
70. Frage
......
Pass4Test hat schon einen guten Ruf im vielen Zertifizierungsbranchen erhalten, weil wir die Testfagen, die Lernhilfe und Dumps zur Financial-Management Zertifizierungsprüfung haben. Zur Zeit als der professionellster Anbieter im Internet bieten wir perfekten Kundenservice und einen einjährigen kostenlosen Update-Service. Wenn der Fragenkataloge zur WGU Financial-Management Zertifizierungsprüfung geändert werden, bieten wir den Kunden Schutz. Die Fragen zur Financial-Management Zertifizierungsprüfung werden von den IT-Experten sorgfältig bearbeitet. Mit den Prüfungsmaterialien zur Financial-Management Zertifizierungsprüfung von Pass4Test wird Ihre Zukunft sicher glänzend sein.
Financial-Management Testking: https://www.pass4test.de/Financial-Management.html