BTW, DOWNLOAD part of Lead2Passed PF1 dumps from Cloud Storage: https://drive.google.com/open?id=1mIyHfcmhh60Wk7ao08DiObqlSoArCWI8
The quality of our PF1 exam questions is very high and we can guarantee to you that you will have no difficulty to pass the exam. The content of the questions and answers of PF1 study braindumps is refined and focuses on the most important information. To let the clients be familiar with the atmosphere and pace of the real exam we provide the function of stimulating the exam. Our expert team updates the PF1 training guide frequently to let the clients practice more. Every detail of our PF1 learning prep is perfect.
| Section | Objectives |
|---|---|
| Termination of Employment | - Termination processing
|
| Workers’ Compensation | - Workers compensation administration
|
| Federal Remittances | - Government remittance obligations
|
| Commission Payments | - Commission payroll processing
|
| Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
| Payroll Accounting | - Payroll accounting practices
|
| Employment Income – Regular Earnings | - Regular payroll calculations
|
| Non-Statutory Deductions | - Voluntary deductions
|
| New Employee Information | - Employee setup and documentation
|
| Year-End Processing | - Federal and provincial year-end reporting
|
| Record of Employment | - ROE processing
|
| Non-Regular Payments | - Special payroll payments
|
| Provincial Remittances | - Provincial payroll requirements
|
>> Valid Test National Payroll Institute PF1 Experience <<
PF1 practice test can be your optimum selection and useful tool to deal with the urgent challenge. With over a decade's striving, our PF1 training materials have become the most widely-lauded and much-anticipated products in industry. We have three versions of PF1 Exam Questions by modernizing innovation mechanisms and fostering a strong pool of professionals. Therefore, rest assured of full technical support from our professional elites in planning and designing PF1 practice test.
NEW QUESTION # 28
When is the government-prescribed rate of interest set?
Answer: C
Explanation:
The CRA's prescribed interest rates are established for specific periods labelled by calendar quarter (for example, "first calendar quarter 2026"), and CRA publishes the rate schedule by quarter.
This prescribed rate is used in multiple tax contexts, including calculating taxable benefits on certain interest- free or low-interest employee/shareholder loans, and it also relates to interest charged/paid by the CRA on overdue amounts and overpayments (with different rates for different situations).
Because CRA's publication is organized and effective by quarter (e.g., Jan 1-Mar 31; Apr 1-Jun 30; Jul 1- Sep 30; Oct 1-Dec 31), the correct answer is each calendar quarter (option D), not monthly, semi-annual, or annual.
NEW QUESTION # 29
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
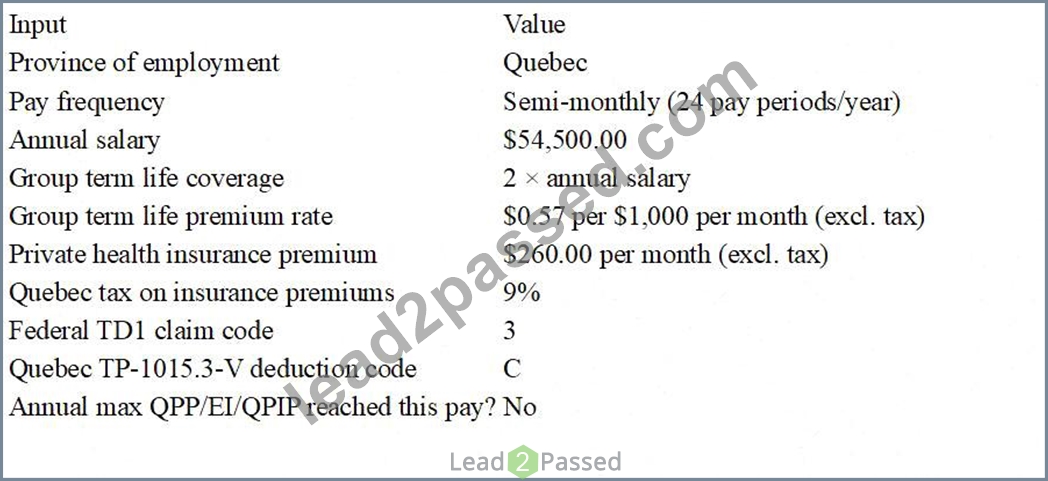
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
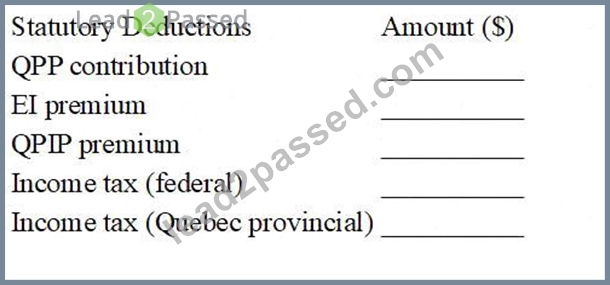
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases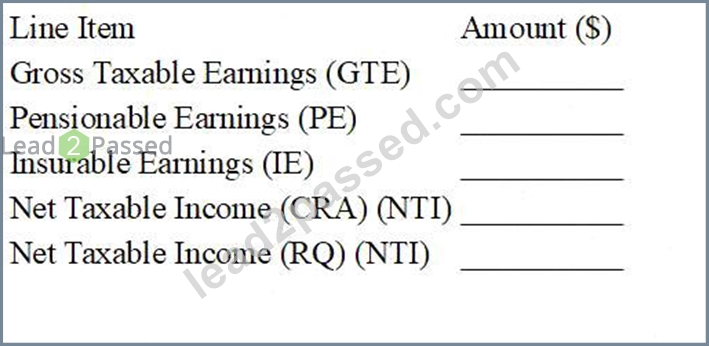
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
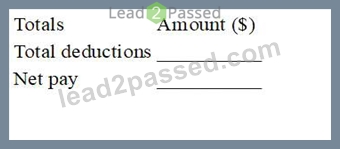
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 30
Tanya submitted a letter of resignation to her employer on April 2 of the current year advising that she would be resigning her position effective April 27 for the pay period ending April 28. What date will appear in Block
11 of Tanya's Record of Employment?
Answer: C
Explanation:
Block 11 on the ROE is "Last day for which paid." Service Canada instructs employers to enter the last day for which the employee received insurable earnings. This date usually coincides with the last day of work, unless the employee continues to receive insurable earnings after the last day worked (for example, paid leave like vacation/sick leave or salary continuance).
In Tanya's case, she gave notice on April 2, but her resignation is effective April 27. There's no information indicating paid leave after April 27 or salary continuance. So Block 11 should be April 27 (the last day she worked/received insurable earnings).
The question also mentions the pay period ending April 28-that date belongs in Block 12 (Final pay period ending date), which is the end date of the final pay period that includes the Block 11 date, and is often different from Block 11.
NEW QUESTION # 31
A Third Party Demand is issued by the Canada Revenue Agency for:
Answer: D
Explanation:
A "Third Party Demand" in payroll collections commonly refers to the CRA's Demand on a Third Party (DTP)-a legal garnishment tool used to collect a person's debt to the government by requiring a third party (such as an employer or financial institution) to redirect funds that would otherwise be paid to the debtor.
CRA guidance explains that garnishments may be issued as a Requirement to Pay (RTP), Enhanced Requirement to Pay (ERTP), or Demand on a Third Party (DTP), and that these documents apply when money normally payable to someone who owes a debt to the government must instead be paid to the CRA (or other listed federal bodies).
This aligns with option B: unpaid income tax or unpaid statutory deductions (such as payroll source deductions) can lead to CRA collection action using these legal instruments.
Child support is generally enforced under provincial/territorial family support programs, not via CRA DTP as described here. Overpaid EI benefits are typically handled through EI/Service Canada recovery processes, and
"third-party creditor debt" is not a CRA-administered debt.
NEW QUESTION # 32
Michael is an employee in Alberta who is paid bi-weekly and earns $1,600.00 per pay period. He has a taxable meal allowance of $30.00 per pay period. His federal and provincial TD1s on file show a claim code
2. Michael already reached the annual maximum first and second Canada Pension Plan (CPP) contributions before this pay. Calculate his total federal and provincial income taxes.
Answer:
Explanation:
(total federal + Alberta tax): $173.48
Explanation:
Taxable gross for the period = $1,600.00 + $30.00 = $1,630.00 (a taxable allowance is included in income for tax withholding).
Using CRA T4032-AB (Biweekly, 26 pay periods) with claim code 2:
Federal tax at pay $1,630 falls in the $1,619-$1,635 range # CC2 = $107.35.
Alberta provincial tax at pay $1,630 falls in the $1,628-$1,644 range # CC2 = $46.55.
Subtotal tax from the tables = $107.35 + $46.55 = $153.90.
CRA notes these tax tables build in the tax credits for CPP/EI, so when CPP is not deducted (because annual max already reached), you must increase tax withholding accordingly.
CPP that would have been deducted this pay (using CRA rates/YBE):
Pensionable = $1,630 # ($3,500/26 = $134.62) = $1,495.38; CPP (4.95% + 1.00% = 5.95%) = $88.98.
Add back missing credits: Federal 14% × 88.98 = $12.46; Alberta 8% × 88.98 = $7.12 # total $19.58.
Final total tax = $153.90 + $19.58 = $173.48.
NEW QUESTION # 33
......
The 21 century is the information century. Information and cyber technology represents advanced productivity, and its rapid development and wide application have given a strong impetus to economic and social development and the progress of human civilization (PF1 exam materials). They are also transforming people's lives and the mode of operation of human society in a profound way. So you really should not be limited to traditional paper-based PF1 Test Torrent in the 21 country especially when you are preparing for an exam, our company can provide the best electronic PF1 exam torrent for you in this website.
Latest PF1 Test Prep: https://www.lead2passed.com/National-Payroll-Institute/PF1-practice-exam-dumps.html
P.S. Free & New PF1 dumps are available on Google Drive shared by Lead2Passed: https://drive.google.com/open?id=1mIyHfcmhh60Wk7ao08DiObqlSoArCWI8