BTW, DOWNLOAD part of PDF4Test Financial-Management dumps from Cloud Storage: https://drive.google.com/open?id=1rjOwLmYravK9PNzubEQRBXZjCm-0GICD
In today's competitive technology sector, the WGU Financial-Management certification is a vital credential. Many applicants, however, struggle to obtain up-to-date and genuine WGU Financial-Management exam questions in order to successfully prepare for the exam. If you find yourself in this circumstance, don't worry since PDF4Test has you covered with their real WGU Financial-Management Exam Questions. Let's look at the characteristics of these WGU Financial Management VBC1 test Questions and how they can help you pass the WGU Financial-Management certification exam on the first try.
| Section | Objectives |
|---|---|
| Capital Budgeting | - Payback period analysis - Net present value (NPV) - Internal rate of return (IRR) |
| Time Value of Money | - Present and future value calculations - Annuities and perpetuities |
| Financial Statement Analysis | - Balance sheet and income statement interpretation - Cash flow analysis - Financial ratios |
| Risk and Return | - Expected return - Portfolio risk and diversification |
| Cost of Capital and Valuation | - Bond and stock valuation basics - Weighted average cost of capital (WACC) |
>> WGU Financial-Management Instant Access <<
You will have a sense of achievements when you finish learning our Financial-Management study materials. During your practice of the Financial-Management preparation guide, you will gradually change your passive outlook and become hopeful for life. We strongly advise you to have a brave attempt. You will never enjoy life if you always stay in your comfort zone. And our Financial-Management Exam Questions will help you realize your dream and make it come true.
NEW QUESTION # 48
What does a beta of less than 1 signify in the capital asset pricing model (CAPM)?
Answer: B
Explanation:
A beta less than 1 indicates that an investment has lower systematic risk than the overall market. Such securities tend to experience smaller fluctuations in response to market movements. Defensive stocks- such as utilities or consumer staples-often exhibit betas below one because their revenues are relatively stable across economic cycles. In CAPM, lower beta implies lower required return, reflecting reduced exposure to market-wide risk. Importantly, a beta below one does not mean the investment is risk-free; it still carries firm-specific (unsystematic) risk. Option B correctly describes the implication of a beta less than one within capital market theory.
NEW QUESTION # 49
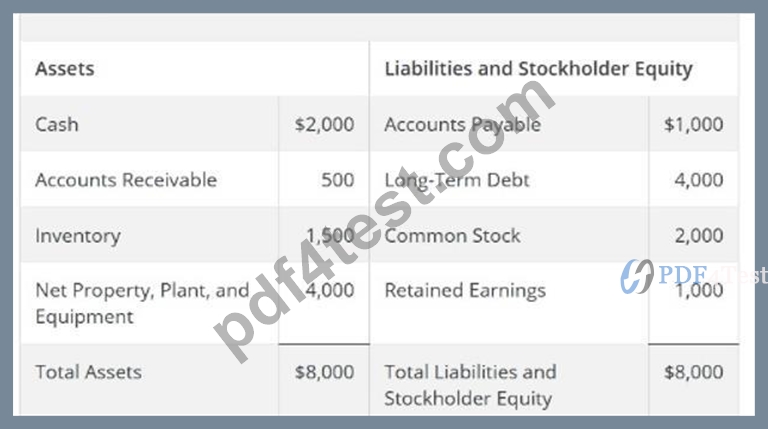
Use Whole Pine Inc.'s financial statements for 20X3 below to answer the following question.
What is Whole Pine Inc.'stotal asset turnoverfor 20X3?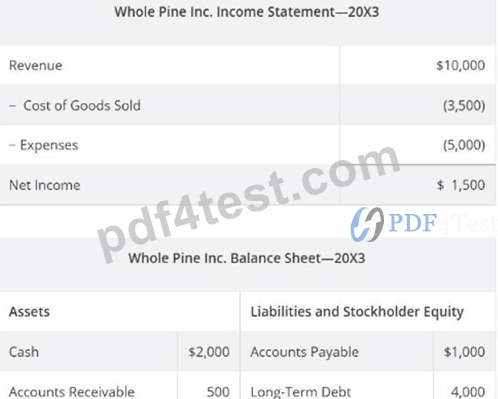
Answer: A
Explanation:
Total asset turnover measures how efficiently a firm uses its assets to generate revenue. It is calculated as Sales ÷ Total Assets. For Whole Pine Inc., sales for 20X3 are $10,000 and total assets are $8,000.
Dividing $10,000 by $8,000 yields a total asset turnover of 1.25. This means the company generates
$1.25 in sales for every $1.00 invested in assets. From a financial management perspective, this ratio is a key indicator of operating efficiency and is commonly compared across firms within the same industry or across time. A higher turnover suggests more efficient use of assets, while a lower turnover may indicate underutilized capacity or inefficient asset deployment. Asset turnover is also a component of the DuPont analysis, linking operational efficiency to return on equity. Option B correctly reflects both the calculation and interpretation consistent with standard financial analysis practice.
NEW QUESTION # 50
Why might tax expense on the income statement not reflect the actual taxes paid by a firm?
Answer: C
Explanation:
Tax expense reported on the income statement is calculated using accrual accounting, which recognizes revenues and expenses when they are earned or incurred, not necessarily when cash is paid. In contrast, actual taxes paid are based on tax laws and cash payments made to tax authorities. Differences arise due to temporary and permanent timing differences between financial reporting rules and tax regulations. Examples include depreciation methods, revenue recognition timing, loss carryforwards, and deferred tax assets or liabilities. These differences cause tax expense to diverge from cash taxes paid in a given period. Financial managers and analysts must understand this distinction to accurately assess cash flows, particularly when forecasting free cash flow or valuing firms. Option A correctly explains this discrepancy, whereas the other options either deny the existence of differences or incorrectly characterize tax expense accounting.
NEW QUESTION # 51
A stock has a dividend per share of $5 and is expected to grow at a constant rate of 3% indefinitely. The required rate of return is 9%.
What is the value of the stock?
Answer: A
Explanation:
This question applies the Gordon growth (constant growth dividend discount) model, which values a stock as the present value of an infinite stream of dividends growing at a constant rate. The model assumes that dividends grow steadily and that the required rate of return exceeds the growth rate, ensuring a finite value. The formula is:
Stock Value = D# ÷ (r # g),
where D# is the dividend expected next year, r is the required rate of return, and g is the growth rate. If the current dividend is $5, the next dividend equals $5 × (1 + 0.03) = $5.15. Substituting into the formula gives:
$5.15 ÷ (0.09 # 0.03) = $5.15 ÷ 0.06 = $85.83.
This valuation approach is commonly used for mature firms with stable dividend policies and predictable growth. Financial managers and analysts rely on this model to estimate intrinsic stock value and assess whether a stock is overvalued or undervalued relative to its market price.
NEW QUESTION # 52
Kretsmart anticipates its sales will grow by10% each year for the next two years. Information from the company's current income statement is given below, andCost of Goods Sold (COGS) is assumed to be a spontaneous account.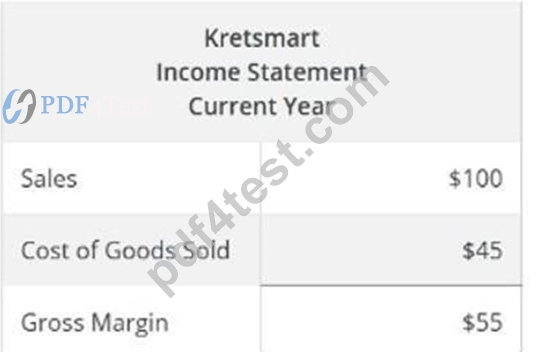
What would the company'sprojected gross margin for Year 2?
Answer: A
Explanation:
When sales grow and cost of goods sold (COGS) is assumed to be a spontaneous account, COGS increases proportionally with sales. In the current year, Kretsmart's gross margin ratio is calculated as Gross Margin ÷ Sales = $55 ÷ $100 =55%, while COGS represents45%of sales.
Sales are projected to grow by 10% per year for two years. Therefore, projected sales for Year 2 are:
$100 × 1.10 × 1.10 =$121.00.
Since COGS remains 45% of sales, projected COGS for Year 2 equals:
$121.00 × 0.45 =$54.45.
Gross margin is then calculated as:
$121.00 # $54.45 =$66.55.
Financial management forecasting techniques commonly use percentage-of-sales assumptions for spontaneous accounts such as COGS, inventory, and receivables. This method allows managers to project future income statements consistently with expected growth. Option B ($66.55) correctly reflects the projected gross margin for Year 2 under these assumptions.
NEW QUESTION # 53
......
The curtain of life stage may be opened at any time, the key is that you are willing to show, or choose to avoid. Most of People who can seize the opportunityin front of them are successful. So you have to seize this opportunity of PDF4Test. Only with it can you show your skills. PDF4Test WGU Financial-Management Exam Training materials is the most effective way to pass the certification exam. With this certification, you will achieve your dreams, and become successful.
Financial-Management Study Reference: https://www.pdf4test.com/Financial-Management-dump-torrent.html
BONUS!!! Download part of PDF4Test Financial-Management dumps for free: https://drive.google.com/open?id=1rjOwLmYravK9PNzubEQRBXZjCm-0GICD