BONUS!!! Download part of ExamsReviews PF1 dumps for free: https://drive.google.com/open?id=1o1T7P1c1qE3x-QWcGHIkLtbZmcyt2jmK
Our PF1 practice questions are not famous for nothing. As long as you choose our PF1 study guide, you will find that the exam questions and answers are always the most accurate and up-to-date. It is all due to the hard work of our professionals who always keep a close eye on the updationg. The PF1 learning braindumps are regularly updated in line with the changes introduced in the exam contents. You will always find our PF1 exam simulating highly relevant to your needs.
| Section | Objectives |
|---|---|
| Topic 1: Termination of Employment | - Termination processing
|
| Topic 2: Year-End Processing | - Federal and provincial year-end reporting
|
| Topic 3: New Employee Information | - Employee setup and documentation
|
| Topic 4: Non-Statutory Deductions | - Voluntary deductions
|
| Topic 5: Provincial Remittances | - Provincial payroll requirements
|
| Topic 6: Payroll Accounting | - Payroll accounting practices
|
| Topic 7: Workers’ Compensation | - Workers compensation administration
|
| Topic 8: Federal Remittances | - Government remittance obligations
|
| Topic 9: Commission Payments | - Commission payroll processing
|
| Topic 10: Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
| Topic 11: Employment Income – Regular Earnings | - Regular payroll calculations
|
| Topic 12: Non-Regular Payments | - Special payroll payments
|
| Topic 13: Record of Employment | - ROE processing
|
With the development of computer hi-tech, the computer application is widely used in recent years. The demand of the higher position about computer is increasing. PF1 exam vce files help people who are interested in National Payroll Institute company. If you have a useful certification, you will have outstanding advantage over other applicants while interviewing. Our PF1 Exam Vce files help you go through examination and get certifications.
NEW QUESTION # 29
What is piecework?
Answer: D
Explanation:
Piecework (also called piece-rate pay) is a pay method where an employee's earnings are determined by output-they are paid a set amount per unit produced or completed, rather than by hours worked or a fixed salary. This aligns directly with option C. A time-based hourly/daily wage (option A) is a different earnings method, and a fixed pay-per-period arrangement (option B) describes salary. Therefore, "all of the above" is incorrect because these are three distinct compensation structures.
In payroll calculations, piecework earnings are typically calculated as: piece rate × number of units produced in the pay period. Employers still have to ensure compliance with employment standards, such as minimum wage and overtime rules, even where piecework is used. A Canadian payroll educational reference defines piecework as payment for each unit produced "regardless of the amount of time taken."
NEW QUESTION # 30
Elodie is paid her commissions together with her bi-weekly salary of $1,000.00. This pay period her commissions are $4,300.00. Calculate her Quebec Pension Plan (QPP) contribution for this pay period.
Answer:
Explanation:
$325.42
Explanation:
Because Elodie is subject to QPP, her pensionable earnings for the pay period include both salary and commissions (both are pensionable employment earnings, assuming no exemptions apply). First, determine total pensionable earnings for the bi-weekly pay:
$1,000.00 + $4,300.00 = $5,300.00.
For 2026, Revenu Quebec shows the QPP basic exemption is $3,500 annually and the (employee) QPP contribution rate on earnings up to the maximum pensionable earnings is 6.30%.
Payroll applies the exemption per pay period. For bi-weekly pay (26 pay periods):
$3,500 ÷ 26 = $134.62 (rounded to cents).
Pensionable earnings subject to QPP this pay:
$5,300.00 # $134.62 = $5,165.38.
QPP contribution:
$5,165.38 × 6.30% = $5,165.38 × 0.063 = $325.41894, which rounds to $325.42.
NEW QUESTION # 31
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
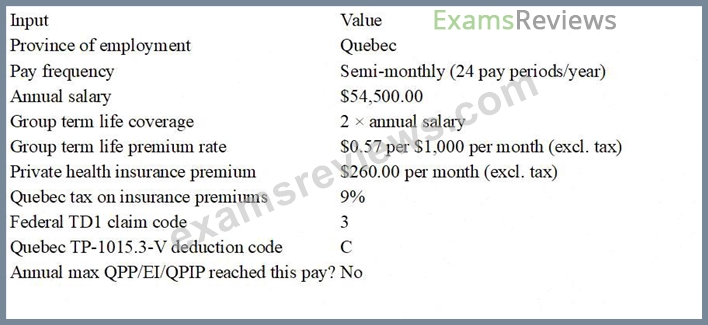
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases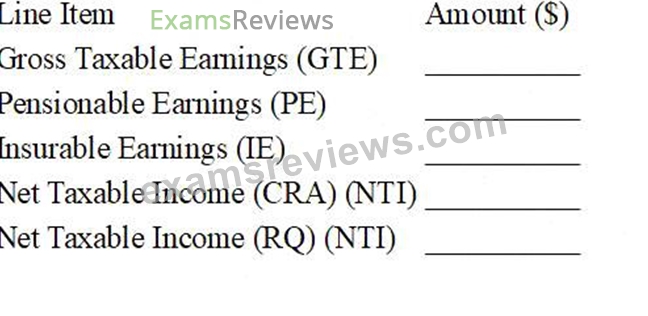
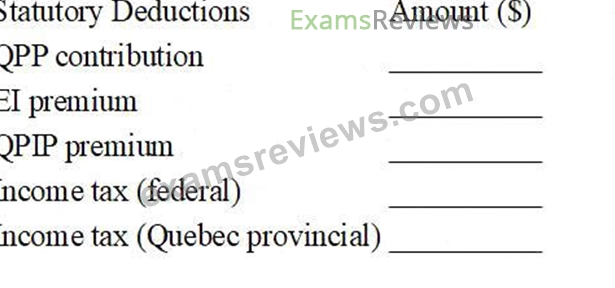
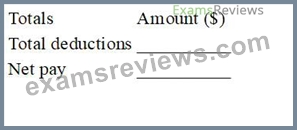
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 32
Jasmine works for a Saskatchewan employer and earns $500.00 weekly. Calculate her Employment Insurance (EI) premium.
Answer:
Explanation:
$8.15 (employee EI premium for the week)
Explanation:
For employees whose province of employment is outside Quebec (including Saskatchewan), EI premiums are calculated by multiplying the employee's insurable earnings by the employee EI premium rate for the year, up to the annual maximum insurable earnings. For 2026, the employee EI premium rate outside Quebec is $1.63 per $100 of insurable earnings (which is 1.63%).
Jasmine earns $500.00 weekly and (based on the question) we assume all earnings are insurable and she has not reached the annual maximum. Her EI premium is:
$500.00 × 1.63% = $500.00 × 0.0163 = $8.15.
This amount is deducted from the employee's pay and later remitted to the CRA as part of the employer's regular payroll remittance. The maximum insurable earnings for 2026 is $68,900, but at $500 per week she would only hit the maximum later in the year (if at all), so the weekly premium calculation above applies.
NEW QUESTION # 33
The authorization for hiring form should contain a checklist to ensure the organization obtains all required information. What is an example of an item that could be on that checklist?
Answer: D
Explanation:
A hiring authorization package/checklist typically ensures the organization collects the documents needed to onboard the employee and set them up correctly in payroll and HR systems. This often includes items like an offer letter, signed policies, banking details for direct deposit, emergency contacts, and required HR/legal acknowledgements. A confidentiality agreement is a common onboarding document because it protects the employer's confidential information and can be required regardless of payroll deductions.
The other options are not good examples of "required information" for all new hires. Employees do not give
"consent" for statutory deductions-deductions like CPP, EI, and income tax withholding are required by law and employers must withhold them when applicable. A "clearance certificate" is not a standard universal onboarding requirement for payroll in Canada. A T1213 is only completed in special situations where an employee requests CRA authorization to reduce tax withheld at source; it is not something most new hires must provide.
NEW QUESTION # 34
......
ExamsReviews also offers National Payroll Institute PF1 desktop practice exam software which is accessible without any internet connection after the verification of the required license. This software is very beneficial for all those applicants who want to prepare in a scenario which is similar to the Payroll Fundamentals 1Exam real examination.
PF1 Exam Learning: https://www.examsreviews.com/PF1-pass4sure-exam-review.html
What's more, part of that ExamsReviews PF1 dumps now are free: https://drive.google.com/open?id=1o1T7P1c1qE3x-QWcGHIkLtbZmcyt2jmK