Our dumps bundle is available at an affordable rate. This bundle includes Financial-Management PDF questions, WGU Financial-Management desktop practice test software and a web-based practice test. Below are features of these three formats of our WGU Financial-Management practice material. The WGU Financial-Management practice test of TestSimulate is beneficial to not only kill WGU Financial Management VBC1 exam anxiety but also to overcoming mistakes in your preparation.
| Section | Objectives |
|---|---|
| Working Capital Management | - Current Liabilities Management
|
| Financial Statement Analysis | - Financial Statement Basics
|
| Financial Management Concepts | - Financial Markets and Institutions
|
| Capital Budgeting | - Decision Criteria
|
| Cost of Capital and Capital Structure | - Cost of Capital
|
| Time Value of Money | - Present and Future Value
|
>> Financial-Management PDF Questions <<
All these Financial-Management exam dumps formats contain real, updated, and error-free WGU Financial Management VBC1 (Financial-Management) exam questions that prepare you for the final Financial-Management exam. To give you an idea about the top features of Financial-Management Exam Dumps, a free demo download facility is being offered to WGU Financial Management VBC1 candidates. This free Financial-Management exam questions demo download facility is available in all three Financial-Management exam dumps formats.
NEW QUESTION # 50
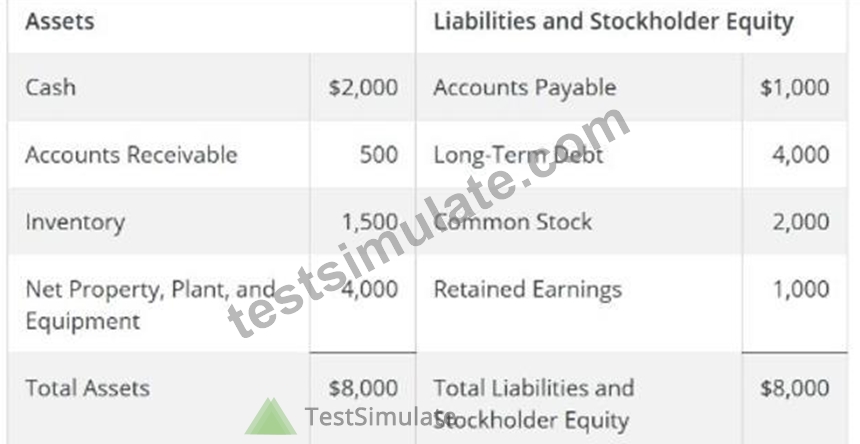
Use Whole Pine Inc.'s financial statements for 20X3 below to answer the following question.
What is Whole Pine Inc.'squick ratiofor 20X3?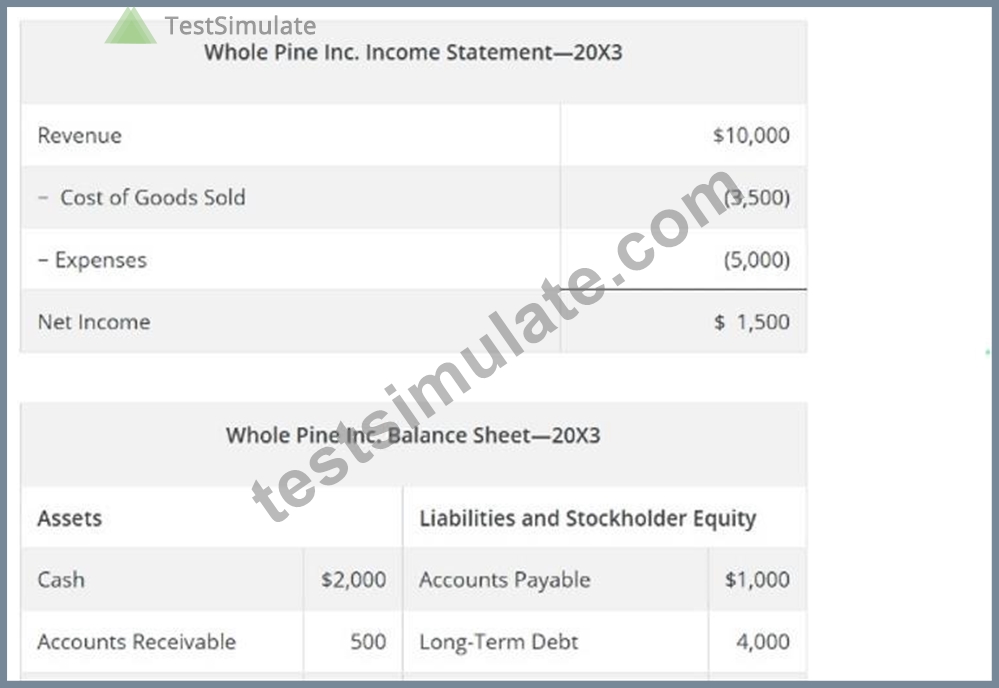
Answer: A
Explanation:
The quick ratio, also known as the acid-test ratio, measures a firm's ability to meet short-term obligations using its most liquid assets. It is calculated as:
(Cash + Accounts Receivable + Marketable Securities) ÷ Current Liabilities.
For Whole Pine Inc., quick assets include cash of $2,000 and accounts receivable of $500, totaling
$2,500. Inventory is excluded because it is less liquid and may not be easily converted into cash.
Current liabilities consist of accounts payable of $1,000. Dividing $2,500 by $1,000 yields a quick ratio of 2.50. This indicates that the firm has $2.50 in highly liquid assets for every $1.00 of short-term obligations, suggesting strong short-term liquidity. Option C correctly reflects this calculation and interpretation.
NEW QUESTION # 51
How does the capital asset pricing model (CAPM) assist in investment decisions?
Answer: A
Explanation:
The CAPM assists in investment decisions by helping investors and financial managers evaluate the relationship between risk and expected return. The model states that the expected return on a security equals the risk-free rate plus a risk premium based on the security's beta and the market risk premium. In this way, CAPM provides a structured method for deciding whether the expected return of a stock is adequate given its level of systematic risk. Choice C is correct because this risk-return trade-off is the core purpose of the model.
CAPM does not predict exact future prices, so choice B is incorrect. It also does not apply only to dividend- paying stocks, making choice A incorrect. Choice D is incorrect because no financial model can guarantee returns in an uncertain market. In financial management, CAPM is widely used to estimate the cost of common equity, evaluate investment performance, and compare required return across securities with different risk levels. Therefore, C is the best answer because CAPM is designed to support investment decisions by linking expected return to systematic market risk.
========
NEW QUESTION # 52
Kretsmart anticipates its sales will grow by10% each year for the next two years. Information from the company's current income statement is given below, andCost of Goods Sold (COGS) is assumed to be a spontaneous account.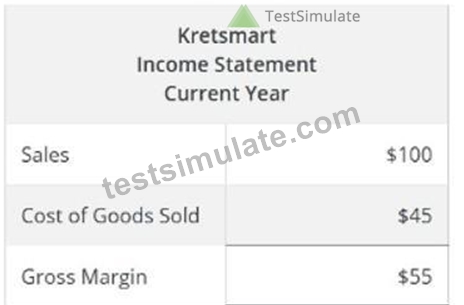
What would the company'sprojected gross margin for Year 2?
Answer: C
Explanation:
When sales grow and cost of goods sold (COGS) is assumed to be a spontaneous account, COGS increases proportionally with sales. In the current year, Kretsmart's gross margin ratio is calculated as Gross Margin ÷ Sales = $55 ÷ $100 =55%, while COGS represents45%of sales.
Sales are projected to grow by 10% per year for two years. Therefore, projected sales for Year 2 are:
$100 × 1.10 × 1.10 =$121.00.
Since COGS remains 45% of sales, projected COGS for Year 2 equals:
$121.00 × 0.45 =$54.45.
Gross margin is then calculated as:
$121.00 # $54.45 =$66.55.
Financial management forecasting techniques commonly use percentage-of-sales assumptions for spontaneous accounts such as COGS, inventory, and receivables. This method allows managers to project future income statements consistently with expected growth. Option B ($66.55) correctly reflects the projected gross margin for Year 2 under these assumptions.
NEW QUESTION # 53
Why might a firm's net income not equal its cash flows from operations for a period?
Answer: C
Explanation:
Net income and cash flow from operations are not the same because net income is prepared using accrual accounting, while cash flow from operations focuses on actual cash movement. Under accrual accounting, revenue may be recorded when earned rather than when cash is received, and expenses may be recorded when incurred rather than when cash is paid. In addition, net income includes noncash expenses such as depreciation and amortization, which reduce accounting profit without reducing current-period cash. Changes in working capital accounts, such as accounts receivable, inventory, and accounts payable, also create differences between net income and operating cash flow. For example, a company may report strong sales and net income, but if many customers have not yet paid, cash flow from operations may still be low. Financial statement analysis places strong emphasis on understanding these differences because cash flow is essential for liquidity, debt repayment, and ongoing operations. Choice A is correct because it directly captures the main reasons net income and cash flow from operations differ. The other choices incorrectly describe the purpose or nature of net income and cash flow reporting.
========
NEW QUESTION # 54
A company has a return on assets (ROA) of 10% and total assets of $500 million.
What is its net income?
Answer: C
Explanation:
Return on assets (ROA) measures how effectively a firm uses its assets to generate profits and is calculated as Net Income ÷ Total Assets. To find net income, the formula is rearranged:
Net Income = ROA × Total Assets.
With an ROA of 10% (0.10) and total assets of $500 million, net income equals $50 million. ROA is a critical profitability metric in financial statement analysis because it links income to the asset base, allowing comparisons across firms and industries regardless of size. A higher ROA indicates more efficient asset utilization. Option C correctly applies the ROA formula and reflects standard financial analysis practice.
NEW QUESTION # 55
......
TestSimulate can lead you the best and the fastest way to reach for the certification and achieve your desired higher salary by getting a more important position in the company. Because we hold the tenet that low quality Financial-Management exam materials may bring discredit on the company. Our Financial-Management learning questions are undeniable excellent products full of benefits, so our Financial-Management exam materials can spruce up our own image. Meanwhile, our Financial-Management exam materials are demonstrably high effective to help you get the essence of the knowledge which was convoluted.
Financial-Management Latest Learning Materials: https://www.testsimulate.com/Financial-Management-study-materials.html