BTW, DOWNLOAD part of PDFDumps PF1 dumps from Cloud Storage: https://drive.google.com/open?id=1KLLZ4nTIWVRRCE4UzZV3rTTYug6QghkY
Many people may have different ways and focus of study to pass PF1 exam in the different time intervals, but we will find that in real life, can take quite a long time to learn PF1 learning questions to be extremely difficult. You may be taken up with all kind of affairs, and sometimes you have to put down something and deal with the other matters for the latter is more urgent and need to be done immediately. With the help of our PF1 training guide, your dream won’t be delayed anymore.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Communication and Compliance | 10% | - Accuracy and documentation
|
| Topic 2: Record of Employment (ROE) | 20% | - ROE completion requirements
|
| Topic 3: Individual Pay Calculations | 40% | - Regular earnings
|
| Topic 4: Termination and Special Payments | 30% | - Leaves and absences
|
If you are willing to purchase valid National Payroll Institute PF1 reliable vce exam simulator, you should be eagle-eyed since there are so much information on the internet. Valid products are hard to tell, once you find them, you will fell as if you'd found a priceless treasure. Our PF1 reliable vce exam simulator will be your priceless products. Our passing rate is 100% recent two years. We can assure you that No Pass Full Refund. Our materials are valid and the best absolutely.
NEW QUESTION # 56
Rosa joined Avion Electronics in April 1983. Her employment was terminated on November 30, 2015 and she was paid a $62,500.00 retiring allowance. Rosa joined her company's pension plan in 1986 and was fully vested on termination of employment. Calculate the non-eligible portion of the retiring allowance.
Answer:
Explanation:
$32,000.00 non-eligible portion
Explanation:
CRA requires separating a retiring allowance into an eligible and non-eligible portion. The eligible portion is the maximum that can be transferred to an RRSP/RPP under the special rules (without using regular RRSP room). The formula is: $2,000 for each year (or part-year) of service before 1996, plus an additional $1,500 for each year (or part-year) before 1989 in which the employee had no employer pension/DPSP benefit vested at the time of payment (or previously paid).
Rosa worked from 1983 to 1995 (inclusive) for pre-1996 service: 13 years × $2,000 = $26,000.
For the extra pre-1989 amount: she joined the pension plan in 1986 and was fully vested when paid the retiring allowance in 2015, so 1986-1988 do not qualify for the extra $1,500. However, 1983-1985 were years before 1989 when she had no vested employer pension benefit, so 3 years × $1,500 = $4,500.
Eligible portion = $26,000 + $4,500 = $30,500.
Non-eligible portion = $62,500 # $30,500 = $32,000.
NEW QUESTION # 57
In which province or territory is the employer-paid premium for private health insurance coverage that includes dental and prescription coverage considered to be a non-cash taxable benefit?
Answer: B
Explanation:
In Quebec, employer-paid premiums (contributions) to a group insurance plan, including a private health services plan (which commonly covers items like dental and prescription drugs), are treated as a taxable benefit for the employee for Quebec purposes. Revenu Quebec explicitly states that contributions (premiums) an employer pays under a group insurance plan for coverage received by an employee constitute a taxable benefit.
Because the employer is paying the premium directly to the insurer (the employee receives coverage rather than cash), this is treated as a non-cash taxable benefit in payroll classification terms. The payroll impact is that this taxable benefit must be included in the employee's Quebec taxable income and reported on the RL-1 (and handled according to Quebec source deduction rules).
Outside Quebec, employer-paid health/dental plan premiums are generally not treated the same way for provincial taxable benefit purposes, which is why the correct answer among the options is Quebec.
NEW QUESTION # 58
National Hardware, an Ontario organization, will be terminating the employment of Emilie St. Germain on October 28, 2019, the last day of the pay period. Emilie started with National Hardware on September 19,
2007. Complete the paper Record of Employment (ROE) for Emilie based on the information provided in the following chart.
Note: Vacationable earnings already include the pay in lieu of notice.
All dates must be entered in the format DDMMYYYY.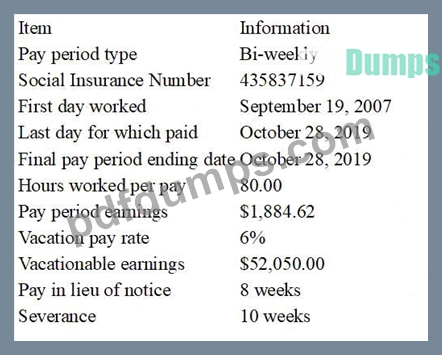
Paper ROE (Form Reference)
Complete the following paper ROE blocks for Emilie:
Block 6 - Pay period type
Block 8 - Social Insurance Number
Block 10 - First day worked
Block 11 - Last day for which paid
Block 12 - Final pay period ending date
Block 15A - Total insurable hours
Block 15B - Total insurable earnings
Block 17A - Vacation pay
Block 17C - Other monies (Pay in lieu of notice)
Block 17C - Other monies (Severance)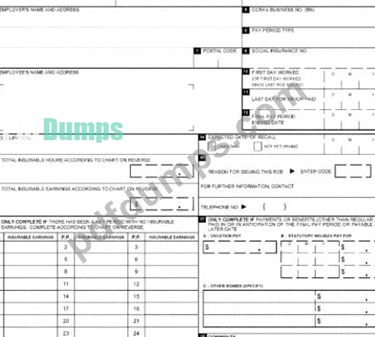
Step 1 - Complete Block 6
Enter the pay period type for Emilie.
Step 2 - Complete Block 8
Enter Emilie's Social Insurance Number.
Step 3 - Complete Block 10
Enter Emilie's first day worked in DDMMYYYY format.
Step 4 - Complete Block 11
Enter Emilie's last day for which paid in DDMMYYYY format.
Step 5 - Complete Block 12
Enter the final pay period ending date in DDMMYYYY format.
Step 6 - Complete Block 15A
Calculate and enter total insurable hours.
Given:
Hours worked per pay period = 80.00
Bi-weekly ROE pay period chart captures 27 pay periods
Step 7 - Complete Block 15B
Calculate and enter total insurable earnings.
Given:
Pay period earnings = $1,884.62
Bi-weekly ROE pay period chart captures 27 pay periods
Step 8 - Complete Block 17A
Calculate and enter vacation pay.
Given:
Vacation pay rate = 6%
Vacationable earnings = $52,050.00
(already includes pay in lieu of notice)
Step 9 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Pay in lieu of notice.
Given:
Pay in lieu of notice = 8 weeks
Use weekly earnings derived from the bi-weekly pay period earnings.
Step 10 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Severance.
Given:
Severance = 10 weeks
Use the same weekly earnings used in Step 9.
Answer:
Explanation:
See the Below Explanation for complete Solution.
Explanation:
Step 1 - Block 6
Bi-weekly
Step 2 - Block 8
435837159
Step 3 - Block 10
September 19, 2007 # 19092007
Step 4 - Block 11
October 28, 2019 # 28102019
Step 5 - Block 12
October 28, 2019 # 28102019
Step 6 - Block 15A (Total insurable hours)
80.00 × 27 = 2160
Block 15A = 2160
Step 7 - Block 15B (Total insurable earnings)
$1,884.62 × 27 = $50,884.74
Block 15B = 50,884.74
Step 8 - Block 17A (Vacation pay)
$52,050.00 × 6% = $3,123.00
Block 17A = 3,123.00
Step 9 - Block 17C (Pay in lieu of notice)
Weekly earnings = $1,884.62 ÷ 2 = $942.31
Pay in lieu = $942.31 × 8 = $7,538.48
Block 17C (Pay in lieu of notice) = 7,538.48
Step 10 - Block 17C (Severance)
Severance = $942.31 × 10 = $9,423.10
Block 17C (Severance) = 9,423.10
NEW QUESTION # 59
What is piecework?
Answer: D
Explanation:
Piecework (also called piece-rate pay) is a pay method where an employee's earnings are determined by output-they are paid a set amount per unit produced or completed, rather than by hours worked or a fixed salary. This aligns directly with option C. A time-based hourly/daily wage (option A) is a different earnings method, and a fixed pay-per-period arrangement (option B) describes salary. Therefore, "all of the above" is incorrect because these are three distinct compensation structures.
In payroll calculations, piecework earnings are typically calculated as: piece rate × number of units produced in the pay period. Employers still have to ensure compliance with employment standards, such as minimum wage and overtime rules, even where piecework is used. A Canadian payroll educational reference defines piecework as payment for each unit produced "regardless of the amount of time taken."
NEW QUESTION # 60
Alyssa is a member of her employer's Defined Contribution Pension Plan. The plan defines the contribution as 3% of the employee's pensionable earnings, with the employer matching the employee's contribution.
Alyssa's pensionable earnings are $3,400.00 per month. Calculate the total payment to be remitted to Alyssa's Defined Contribution Pension Plan each month.
Answer:
Explanation:
$204.00 per month
Explanation:
In a Defined Contribution (DC) pension plan, contributions are calculated as a set percentage of the employee' s pensionable earnings, and the total remittance is usually the sum of the employee deduction plus the employer's matching contribution, based on the plan text. Here, the plan states the employee contributes 3% of pensionable earnings, and the employer matches the employee contribution.
Step 1: Calculate the employee's pension contribution:
3% × $3,400.00 = 0.03 × 3,400.00 = $102.00.
Step 2: Calculate the employer match:
Because the employer matches the employee contribution, the employer contributes $102.00 as well.
Step 3: Total remittance to the plan:
$102.00 (employee) + $102.00 (employer) = $204.00 each month.
From a payroll processing perspective, the employee amount is withheld from gross pay as a payroll deduction according to plan rules, while the employer match is recorded as an employer expense. Payroll remits both amounts to the plan administrator following the plan's remittance schedule, and should reconcile pensionable earnings and contributions to ensure accuracy and compliance with plan terms.
NEW QUESTION # 61
......
Today is the best time to become competitive and updated in the market. You can do this easily. Just enroll in the PF1 exam and start PF1 exam preparation with Payroll Fundamentals 1Exam exam dumps. Download the Exams. Solutions National Payroll Institute PF1 Exam Dumps after paying an affordable PF1 exam questions charge and start this journey without wasting further time.
PF1 Valid Test Experience: https://www.pdfdumps.com/PF1-valid-exam.html
P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by PDFDumps: https://drive.google.com/open?id=1KLLZ4nTIWVRRCE4UzZV3rTTYug6QghkY