2026 Latest ExamDumpsVCE IIA-CIA-Part3 PDF Dumps and IIA-CIA-Part3 Exam Engine Free Share: https://drive.google.com/open?id=1P_DRFh-2TvS_-WQHZgeqsporu4ayUqtJ
The IIA-CIA-Part3 dumps of ExamDumpsVCE include valid Internal Audit Function (IIA-CIA-Part3) questions PDF and customizable IIA-CIA-Part3 practice tests. Our 24/7 customer support provides assistance to help IIA-CIA-Part3 Dumps users solve their technical hitches during their test preparation. The IIA-CIA-Part3 exam questions of ExamDumpsVCE come with up to 365 days of free updates and a free demo.
IIA IIA-CIA-Part3: Business Knowledge for Internal Auditing exam is a certification offered by the Institute of Internal Auditors (IIA). Internal Audit Function certification is designed to test the knowledge and competency of internal auditors in areas such as business acumen, financial management, and strategic planning. Passing IIA-CIA-Part3 exam is an excellent way to demonstrate one's expertise in these areas and to advance in the field of internal auditing.
Passing the IIA-CIA-Part3 Exam is an important milestone for candidates pursuing the CIA certification. It demonstrates their knowledge and proficiency in applying business concepts to internal auditing. It also helps them develop a deeper understanding of the business environment and its impact on internal auditing. Moreover, passing the exam can also lead to career advancement opportunities and higher salaries.
>> IIA-CIA-Part3 Valid Test Pass4sure <<
If you want to buy IIA IIA-CIA-Part3 exam information, ExamDumpsVCE will provide the best service and the best quality products. Our exam questions have been authorized by the manufacturers and third-party. And has a large number of IT industry professionals and technology experts, based on customer demand, according to the the outline developed a range of products to meet customer needs. IIA IIA-CIA-Part3 Exam Certification with the highest standards of professional and technical information, as the knowledge of experts and scholars to study and research purposes. All of the products we provide have a part of the free trial before you buy to ensure that you fit with this set of data.
In order to be eligible to take the IIA-CIA-Part3 exam, candidates must have completed the IIA-CIA-Part1 and IIA-CIA-Part2 exams or have obtained a waiver. They must also meet the IIA's experience requirements, which vary depending on their educational background. Overall, the IIA-CIA-Part3 Certification Exam is a challenging but rewarding certification that can help internal auditors take their careers to the next level.
NEW QUESTION # 225
A small chain of grocery stores made a reporting error and understated its ending inventory. What effect would this have on the income statement for the following year?
Answer: A
Explanation:
Comprehensive and Detailed Step-by-Step Explanation with all IIA References: =
* Understanding the Impact of an Understated Ending Inventory:
* Ending inventory is a key component of the cost of goods sold (COGS) calculation:
COGS=BeginningInventory+Purchases#EndingInventoryCOGS = Beginning Inventory + Purchases - Ending InventoryCOGS=BeginningInventory+Purchases#EndingInventory
* If the ending inventory is understated, it means the reported inventory is lower than its actual value.
* This results in an overstated COGS because a smaller amount is subtracted in the formula above.
* An overstated COGS leads to an understated net income in the current year.
* Effect on the Following Year's Income Statement:
* The beginning inventory for the next year is based on the ending inventory of the previous year.
* Since the prior year's ending inventory was understated, the new year's beginning inventory is also understated.
* A lower beginning inventory leads to a lower COGS in the new year.
* Since COGS is lower, net income in the following year will be overstated.
* IIA's Perspective on Financial Reporting Errors:
* The IIA's International Standards for the Professional Practice of Internal Auditing (IPPF) emphasize the importance of accurate financial reporting.
* IIA Standard 1220 - Due Professional Care requires internal auditors to consider the probability of errors, fraud, or misstatements in financial reporting.
* COSO's Internal Control - Integrated Framework highlights that inventory valuation errors can impact financial integrity and decision-making.
* GAAP & IFRS Accounting Standards also require proper inventory reporting to ensure accurate financial statements.
IIA References:
* IPPF Standard 1220 - Due Professional Care
* COSO Internal Control - Integrated Framework
* GAAP & IFRS Accounting Principles on Inventory Valuation
Thus, the correct and verified answer is C. Net income would be overstated.
NEW QUESTION # 226
Which of the following is most important for an internal auditor to check with regard to the database version?
Answer: B
Explanation:
The most important database version issue is whether the version is still supported by the vendor.
Unsupported database software may no longer receive security patches, bug fixes, compatibility updates, or technical support. This creates significant operational, cybersecurity, compliance, and availability risk. Using the most recent version is not always necessary because organizations may deliberately delay upgrades until stability and compatibility are confirmed. A recent upgrade does not automatically mean the version is secure or supported. Restricting access to version information may reduce reconnaissance risk, but it is secondary to vendor support status. Internal audit should review version support, patch management, upgrade planning, known vulnerabilities, and compensating controls. Therefore, Option B is correct.
NEW QUESTION # 227
The management of ABC Corporation is analyzing the financial statements of XYZ Corporation because ABC is strongly considering purchasing a block of XYZ ordinary shares that would give ABC significant influence over XYZ. Which financial statement should ABC primarily use to assess the amounts, timing, and certainty of future cash flows of XYZ Company?
Answer: A
Explanation:
A statement of cash flows provides information about the cash receipts and cash payments of an enterprise during a period. This information helps investors, creditors, and other users to assess the enterprise's ability to generate cash and cash equivalents and the needs of the enterprise to use those cash flows. Historical cash flow data indicate the amount, timing, and certainty of future cash flows. It is also a means of verifying past cash flow assessments and of determining the relationship between profits and net cash flows and the effects of changing price.
NEW QUESTION # 228
An entity had the following selected per-unit data relating to work-in-process:
Selling price US $100
Comparison cost 10
Historical cost 91
Replacement cost 108
Normal gross profit 20
Selling cost 5
In comparison with historical cost, what will be the per-unit impact on gross profit of measuring ending inventory?
Answer: C
Explanation:
Inventories are measured at the lower of cost or net realizable value NRV). NRV equals selling price minus completion and selling costs. Given that historical cost is US $91 and NRV is US $84price of $100 - $100 - $10 completion cost - $5 selling cost, the effect on per-unit gross profit is a reduction of US $6. This amount is the write down expensed.
NEW QUESTION # 229
Which of the following most appropriately describes the classification and behavior of shipping costs?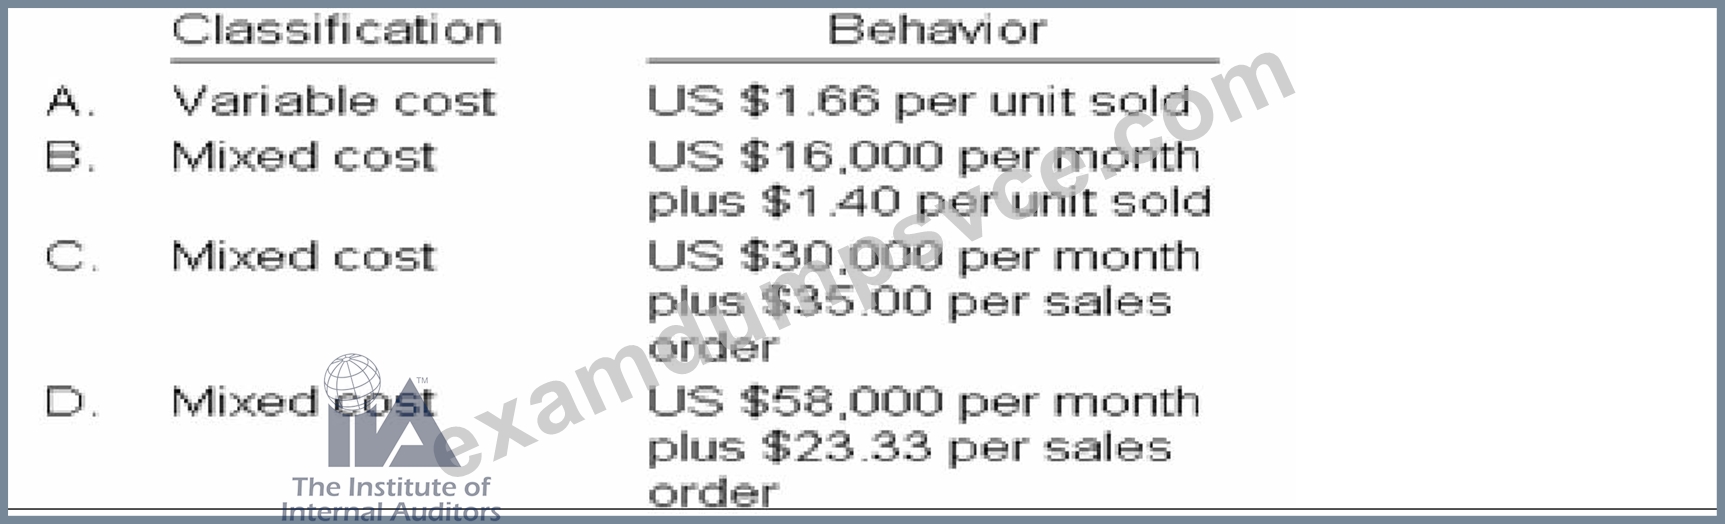
Answer: B
Explanation:
Using the high-low method, the variable and fixed costs for shipping can be calculated. The difference in cost levels divided by the difference in unit volume equals the variable cost per unit of US $1.40 [ $1 14,000 $93,000) - 70,000 - 55,000)]. The variable cost for 70,000 units is US $98,000 70,000 x $1 40). Subtracting the variable cost from total shipping cost results in the fixed cost of US $16,000 $114,000 - $98,000). A company wants to determine its marketing costs for budgeting purposes. Activity measures and costs incurred for 4 months of the current year are presented in the table below. Advertising is considered to be a discretionary cost. Salespersons are paid monthly salaries plus commissions. The sales force was increased from 20 to 21 individuals during the month of May.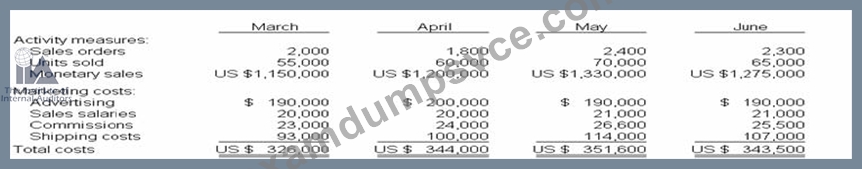
NEW QUESTION # 230
......
Valid IIA-CIA-Part3 Exam Materials: https://www.examdumpsvce.com/IIA-CIA-Part3-valid-exam-dumps.html
BTW, DOWNLOAD part of ExamDumpsVCE IIA-CIA-Part3 dumps from Cloud Storage: https://drive.google.com/open?id=1P_DRFh-2TvS_-WQHZgeqsporu4ayUqtJ