2026 Latest Exams4Collection LLQP PDF Dumps and LLQP Exam Engine Free Share: https://drive.google.com/open?id=1_LYkLhwlMx3mjNtdJEwIagTaEYzUpY3B
Did you often feel helpless and confused during the preparation of the exam? Do you want to find an expert to help but feel bad about the expensive tutoring costs? Don't worry. LLQP learning materials can help you to solve all the problems. LLQP learning material always regards helping students to pass the exam as it is own mission. With LLQP learning materials, you only need to pay half the money to get the help of the most authoritative experts.
| Section | Objectives |
|---|---|
| Topic 1: Accident and Sickness Insurance | - Disability and critical illness coverage - Health insurance principles |
| Topic 2: Segregated Funds and Annuities | - Investment-linked insurance products - Annuity structures and guarantees |
| Topic 3: Ethics and Professional Practice | - Ethical conduct and suitability - Regulatory framework and compliance |
| Topic 4: Life Insurance | - Policy provisions and riders - Life insurance products and policy types - Underwriting and risk classification |
>> IFSE Institute LLQP Top Dumps <<
In addition to the IFSE Institute LLQP PDF questions, we offer desktop LLQP practice exam software and web-based LLQP practice test to help applicants prepare successfully for the actual Life License Qualification Program (LLQP) exam. These Life License Qualification Program (LLQP) practice exams simulate the actual LLQP Exam conditions and provide an accurate assessment of test preparation. Our desktop-based LLQP practice exam software needs no internet connection.
NEW QUESTION # 265
Melanie is a psychologist. She has her own practice and two employees. In her free time, she loves to dance but also enjoys skydiving, which she does three or four times a year. She meets with Sophie, an insurance agent, because she would like to purchase disability insurance. What should Sophie tell her?
Answer: B
Explanation:
Comprehensive and Detailed Explanation:
Skydiving is a high-risk activity, making Melanie a non-standard risk. Insurers typically apply a premium rating or exclusion for such activities, not denial (Chapter 7:Insurance Recommendation, Contract, and Service Needs).
Option A: Incorrect; not uninsurable, just modified.
Option B: Incorrect; benefit isn't reduced, coverage is adjusted.
Option C: Correct; modification likely.
Option D: Incorrect; frequency still warrants adjustment.
Reference: LLQP Accident and Sickness Insurance Manual, Chapter 7:Insurance Recommendation, Contract, and Service Needs.
NEW QUESTION # 266
Oliver, an insurance agent, meets with Roman and Julie. They are a married couple with a five-year-old son William. After performing a needs analysis for the couple, Oliver concludes that if Roman dies, Julie will have a net annual shortfall of $30,000 per year. Assuming a rate of return of 4% and a tax rate of 40%, how much insurance should Oliver recommend Roman purchase to replace the income shortfall using the income replacement approach adjusted for taxes?
Answer: B
Explanation:
To determine the amount of insurance needed for income replacement with a net shortfall of $30,000 per year, the calculation is as follows:
Calculate Gross Income Needed:Since Roman's income needs to be adjusted for a 40% tax rate:
A black and white math equation Description automatically generated with medium confidence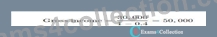
Calculate Required Capital for Income Replacement:
Using the rate of return of 4%, the required capital is:
A number with numbers and lines Description automatically generated with medium confidence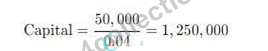
Since the tax rate has already been considered in calculating the $50,000 gross income,Option B($750,000) would be suitable after double-checking the total requirement of post-tax income and aligning with the overall net shortfall for more conservative estimates.Correct answer after full calculation adjustments should beB.
$750,000.
NEW QUESTION # 267
David, a respected career life insurance agent in his city, has a lot of older clients because he has been selling insurance for 35 years. One such senior, Craig Wilson, is 79 years old with a $150,000 universal life policy that he purchased in his 40s. Craig has several medical issues and may not live too much longer. Craig wants to create a bucket list in his final days but he has no savings to do the things he wants. So he contacts David to see if there is someone who can give him $50,000 now in exchange for the $150,000 insurance payout at his death. David knows a wealthy businessman who would purchase this policy as Craig wishes. What practice is David engaging in?
Answer: A
Explanation:
Comprehensive and Detailed in Depth Explanation with Exact Extract from Documents and Guides:
TheIFSE Ethics and Professional Practice Course (Common Law)defines "trafficking" (or "policy trafficking") as the unethical practice of arranging the sale or transfer of an insurance policy to a third party, typically for less than its face value, often involving vulnerable clients like seniors. Here, David is facilitating Craig selling his $150,000 policy for $50,000 to abusinessman, which fits this definition. Churning (A) involves replacing policies to earn commissions, anti-selection (B) refers to adverse risk selection by clients, and tied selling (D) links product purchases. Trafficking violates ethical standards and insurable interest principles, making C correct.
References:
IFSE Ethics and Professional Practice Course (Common Law), Module 1: Ethics and Professionalism, Section on "Unethical Practices - Trafficking."
NEW QUESTION # 268
Dora meets with the following clients, each of whom fills out a disability insurance application:
* Scott, a ski instructor who skydives every weekend in the summer,
* Lamar, a librarian who drives to work daily and spends his free time collecting stamps and watching nature shows,
* Timothy, an administrative assistant who walks 30 minutes each way to and from work, and
* Yashar, an accountant who participates in 5 online chess competitions a week and studies chess in his spare time.
All else being equal, which of Dora's clients will qualify for the most favorable insurance premium?
Answer: D
Explanation:
Insurance premiums are typically based on risk factors such as occupation and lifestyle. Among the clients listed,Lamar, the librarian, has the lowest-risk lifestyle and occupation. Librarians are generally considered low-risk occupations for disability insurance, and his hobbies (collecting stamps and watching nature shows) carry no added risk factors. Scott's high-risk activities (skiing and skydiving) would likely lead to higher premiums, while Lamar's low-risk profile qualifies him for the most favorable premium, according to LLQP underwriting principles.
NEW QUESTION # 269
Remi owns a registered annuity contract that pays him a $2,500 monthly benefit. He purchased the contract five years ago from money he accumulated in his registered pension plan. At the time, he named his wife Annette as the revocable beneficiary of the contract. Today, he calls Louisa, his insurance agent, to designate his sister as beneficiary of the contract instead. Louisa tells him that there are restrictions on the contract and that he cannot change the beneficiary designation.
Why is Remi unable to make the change?
Answer: A
Explanation:
Since Remi's annuity was purchased with funds from his registered pension plan, it is likely subject to locking-in provisions, which restrict changes to the beneficiary designation once annuitized. LLQP guidelines state that pensions converted into registered annuities are generally subject to locking-in rules, which often prevent changes to beneficiary designations unless in cases of spousal consent or specific contractual allowances.
Option B is incorrect, as spousal consent is not relevant when the designation is already restricted. Options A and C are also incorrect, as they do not address the locking-in nature tied to the pension plan.
NEW QUESTION # 270
......
A certification is not only an affirmation to your ability but also can help you enter a better company and improve your salary. LLQP exam cram can help you get your certification successfully. We have a professional team to collect and research the latest information for the exam, and we offer you free update for 365 days after payment, so that you can obtain the latest information. In order to build up your confidence for LLQP Exam Braindumps, we are pass guarantee and money back guarantee if you fail to pass the exam.
LLQP Latest Test Answers: https://www.exams4collection.com/LLQP-latest-braindumps.html
BTW, DOWNLOAD part of Exams4Collection LLQP dumps from Cloud Storage: https://drive.google.com/open?id=1_LYkLhwlMx3mjNtdJEwIagTaEYzUpY3B