P.S. Free & New Accounting-for-Decision-Makers dumps are available on Google Drive shared by Prep4pass: https://drive.google.com/open?id=17WNRIsIPcAIvyqNO6x4MxS8jDJqgpjMd
You can increase your competitive force in the job market if you have the certificate. Accounting-for-Decision-Makers exam torrent of us will offer an opportunity like this. If you choose us, we will help you pass the exam just one time. Accounting-for-Decision-Makers exam torrent of us is high quality and accuracy, and you can use them at ease. Besides, we offer you free demo to have a try before buying, and we have free update for 365 days after purchasing. The update version for Accounting-for-Decision-Makers Exam Dumps will be sent to your email automatically.
| Section | Objectives |
|---|---|
| Business Decision Support | - Relevant Costing
|
| Financial Accounting Fundamentals | - Accounting Principles
|
| Managerial Accounting for Decision Making | - Cost Behavior
|
>> New Accounting-for-Decision-Makers Exam Sample <<
No one wants to own insipid life. Do you want to at the negligible postion and share less wages forever? And do you want to wait to be laid off or waiting for the retirement? This life is too boring. Do not you want to make your life more interesting? It does not matter. Today, I tell you a shortcut to success. It is to pass the WGU Accounting-for-Decision-Makers exam. With this certification, you can live the life of the high-level white-collar. You can become a power IT professionals, and get the respect from others. Prep4pass will provide you with excellent WGU Accounting-for-Decision-Makers Exam Training materials, and allows you to achieve this dream effortlessly. Are you still hesitant? Do not hesitate, Add the Prep4pass's WGU Accounting-for-Decision-Makers exam training materials to your shopping cart quickly.
NEW QUESTION # 25
Which action should a managerial accountant consider taking if confronted by an ethical conflict?
Answer: A
Explanation:
The correct answer is A. Use an objective advisor confidentially . The IMA Statement of Ethical Professional Practice includes guidance for resolving ethical conflict and notes that management accountants may wish to discuss the matter with an objective advisor to obtain a better understanding of possible courses of action. This step is intended to help the accountant evaluate the issue carefully while preserving confidentiality and professionalism.
Option B is not the best answer because going directly to the chief executive officer is not always the first or most appropriate step. Ethical conflict guidance usually recommends following the organization's established chain of command unless the issue involves that level of management. Option C is incorrect because discussing the issue with "any stakeholder" could violate confidentiality. Option D is also weaker because consulting a coworker is not the same as seeking advice from an objective and appropriate advisor. The emphasis in professional ethics guidance is on confidentiality, sound judgment, and proper escalation.
Therefore, the most suitable action among the options given is to use an objective advisor confidentially , making Option A correct.
NEW QUESTION # 26
Which body regulates a certified public accounting firm's audit practices when the firm is auditing a large, publicly traded company?
Answer: C
Explanation:
The correct answer is D. The Public Company Accounting Oversight Board (PCAOB) . The PCAOB was created to oversee the audits of public companies and SEC-registered brokers and dealers in order to protect investors and support the public interest in accurate, independent audit reports. Its responsibilities include registration of audit firms, inspections, enforcement, and audit-related standard-setting. Because the question refers to a CPA firm auditing a large, publicly traded company , PCAOB oversight is the correct regulatory answer.
Option A is incorrect because FASB sets accounting standards, not audit practice regulation for public company auditors. Option B, FASAC , is an advisory council to FASB and does not regulate audit firms.
Option C, the IRS , administers tax laws and does not oversee external audit practices for public companies.
In accounting and auditing, it is essential to distinguish between those who set accounting rules and those who supervise auditors. For publicly traded companies, that audit oversight role belongs to the PCAOB , making Option D the only accurate choice.
NEW QUESTION # 27
A company allocates overhead based on the number of shoes produced.
The company estimates the following costs and shoe production for the upcoming year:
Estimated total overhead = $1,250,000
Estimated number of shoes = 4,000,000
Actual overhead = $1,350,000
Actual number of shoes = 4,100,000
What is the predetermined overhead rate?
Answer: B
Explanation:
The correct answer is A. $0.313 . A predetermined overhead rate is calculated at the beginning of the period using estimated overhead costs and the estimated amount of the allocation base. OpenStax states that the rate is found by dividing estimated manufacturing overhead by the estimated activity base.
The formula is:
Predetermined overhead rate = Estimated total overhead / Estimated allocation base Using the numbers in the question:
$1,250,000 / 4,000,000 shoes = $0.3125 per shoe
Rounded to three decimal places, that equals $0.313 per shoe .
The actual overhead and actual number of shoes produced are not used to compute the predetermined rate.
Those figures are used later when applying overhead or analyzing overapplied and underapplied overhead.
That is why choices based on actual data are incorrect.
Option B, $0.329 , comes from dividing actual overhead by actual production, but that is an actual rate, not the predetermined one asked for here. Since predetermined overhead always relies on estimates made in advance, the correct answer is $0.313 , which makes Option A correct.
NEW QUESTION # 28
Which ratio provides a measure of how well a company turns sales into profits?
Answer: A
Explanation:
The correct answer is A. Return on sales . Return on sales, also called profit margin or net profit margin , measures how effectively a company converts sales revenue into net income. It is commonly calculated as Net income ÷ Sales . OpenStax explains that this ratio shows how much of each sales dollar remains as profit after all expenses, including taxes, have been deducted. A higher ratio generally indicates stronger profitability and better cost control relative to revenue.
Option B, return on costs , is not the standard ratio named in basic financial analysis for this purpose. Option C, return on expenses , is also not the conventional measure used in the ratio formulas you listed. Option D, return on profit , is not a recognized standard profitability ratio in introductory accounting frameworks.
Since the question asks specifically about how well a company turns sales into profits , the ratio that directly measures that relationship is return on sales . This ratio is widely used in financial statement analysis to compare operating performance across periods and across firms, especially within the same industry.
NEW QUESTION # 29
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.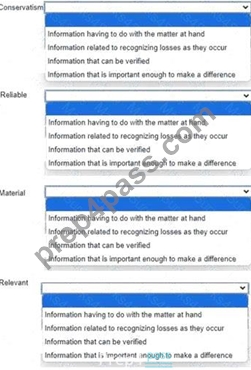
Answer:
Explanation: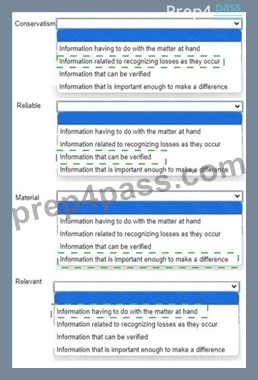
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
NEW QUESTION # 30
......
By taking a Accounting-for-Decision-Makers practice exam, you can find out what you're good at. Accounting-for-Decision-Makers exam preparation software is the best way to prepare for your Accounting-for-Decision-Makers certification exam. With the Accounting-for-Decision-Makers list of questions, you can brush up on your skills and knowledge. With Prep4pass, you'll access a lot of Accounting-for-Decision-Makers Practice Questions, detailed explanations, and personalized feedback. And because it's all online, you can study anywhere, anytime. The WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) practice exam consists of questions from a pool of questions.
Accounting-for-Decision-Makers Valid Study Materials: https://www.prep4pass.com/Accounting-for-Decision-Makers_exam-braindumps.html
BONUS!!! Download part of Prep4pass Accounting-for-Decision-Makers dumps for free: https://drive.google.com/open?id=17WNRIsIPcAIvyqNO6x4MxS8jDJqgpjMd