What's more, part of that VCEPrep PF1 dumps now are free: https://drive.google.com/open?id=1OJbgFJYt1BnFRk398Tnfw6RXUpYLqcJV
PF1 certification can demonstrate your mastery of certain areas of knowledge, which is internationally recognized and accepted by the general public as a certification. PF1certification is so high that it is not easy to obtain it. It requires you to invest time and energy. If you are not sure whether you can strictly request yourself, our PF1 test materials can help you. With high pass rate of our PF1 exam questons as more than 98%, you will find that the PF1 exam is easy to pass.
| Section | Weight | Objectives |
|---|---|---|
| Termination and Special Payments | 30% | - Leaves and absences
|
| Individual Pay Calculations | 40% | - Regular earnings
|
| Communication and Compliance | 10% | - Accuracy and documentation
|
| Record of Employment (ROE) | 20% | - ROE completion requirements
|
>> National Payroll Institute PF1 Certification Materials <<
Pass the Payroll Fundamentals 1Exam PF1 certification exam which is a challenging task. To make PF1 exam success journey simple, quick, and smart, you have to prepare well and show a firm commitment to passing this exam. The real, updated, and error-free Payroll Fundamentals 1Exam PF1 Exam Dumps are available over the VCEPrep.
NEW QUESTION # 71
The source deductions form completed by all new employees in Quebec is called:
Answer: A
Explanation:
In Quebec, employees must complete a Quebec-specific source deductions form so the employer can calculate Quebec income tax to withhold. Revenu Quebec identifies Form TP-1015.3-V (Source Deductions Return) as the form employees complete and provide to their employer/payer for this purpose. It is part of the onboarding
/payroll setup process in Quebec and is used to determine personal tax credits and any additional withholding instructions for Quebec provincial income tax.
The other options are not the standard Quebec source deductions return for new employees: T1213 is a CRA form used to request a reduction in tax deductions at source (federal), TD1-AB is a provincial TD1 for Alberta (not Quebec), and T2222 is not the Quebec source deductions return. From a payroll communication standpoint, the employer should request both the applicable federal TD1 and the Quebec TP-1015.3-V, then retain them on file to support accurate withholding calculations.
NEW QUESTION # 72
The authorization for hiring form should contain a checklist to ensure the organization obtains all required information. What is an example of an item that could be on that checklist?
Answer: B
Explanation:
A hiring authorization package/checklist typically ensures the organization collects the documents needed to onboard the employee and set them up correctly in payroll and HR systems. This often includes items like an offer letter, signed policies, banking details for direct deposit, emergency contacts, and required HR/legal acknowledgements. A confidentiality agreement is a common onboarding document because it protects the employer's confidential information and can be required regardless of payroll deductions.
The other options are not good examples of "required information" for all new hires. Employees do not give
"consent" for statutory deductions-deductions like CPP, EI, and income tax withholding are required by law and employers must withhold them when applicable. A "clearance certificate" is not a standard universal onboarding requirement for payroll in Canada. A T1213 is only completed in special situations where an employee requests CRA authorization to reduce tax withheld at source; it is not something most new hires must provide.
NEW QUESTION # 73
Dollar amounts that are paid to an employee to cover expenses that they incurred while performing their job, but are not considered in the calculation of an employee's earnings are:
Answer: D
Explanation:
An expense reimbursement is a repayment to an employee for business costs they already paid personally (for example, meals, mileage, supplies), typically supported by receipts or an expense report. CRA's guidance explains that a reimbursement is a payment made to repay amounts the employee spent while conducting the employer's business, and that a reasonable reimbursement is generally not included in the employee's income.
That's why reimbursements are generally not part of "earnings" for payroll calculations-they are not compensation for work performed; they are repayment of a business expense. This differs from an allowance, which is usually a fixed amount paid without requiring receipts; allowances are often taxable unless a specific CRA exception applies.
So the correct term for "dollar amounts paid to cover job expenses incurred, but not considered earnings" is expense reimbursements (option D). Payroll best practice is to ensure reimbursements are properly documented and reasonable to support non-taxable treatment.
NEW QUESTION # 74
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
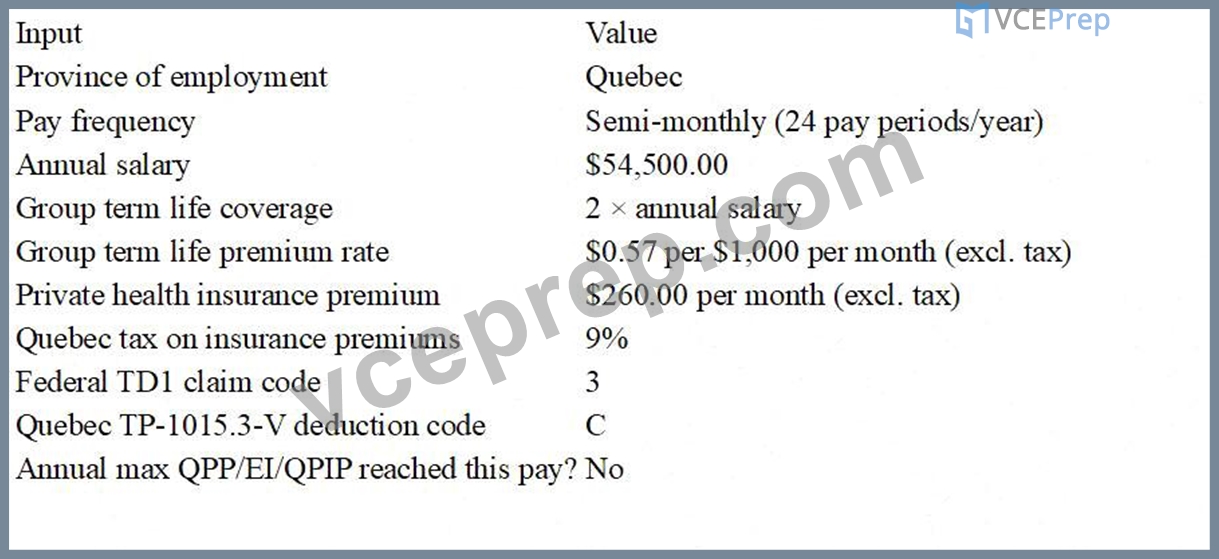
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases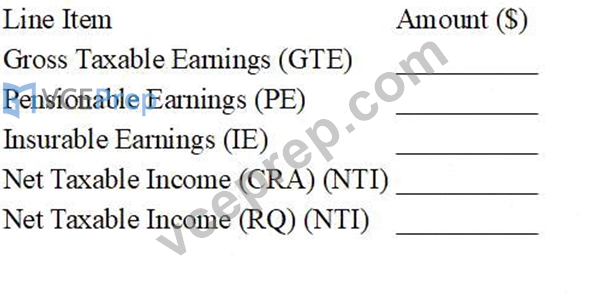
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
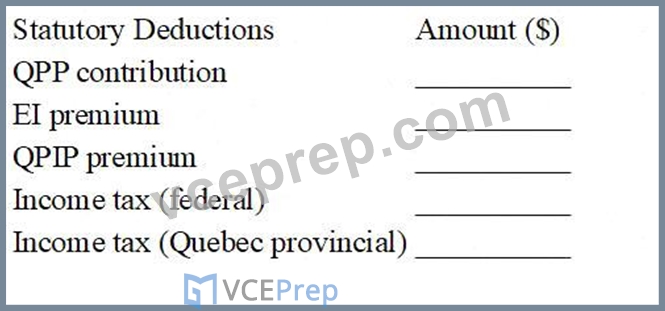
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
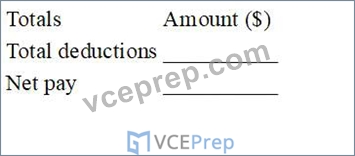
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
NEW QUESTION # 75
Ursula is 17 years old, works in Quebec and earns $750.00 weekly. Ursula pays weekly union dues of $18.00 along with a special weekly union assessment of $10.00 for construction of a new union hall for its members.
Ursula also has registered pension plan (RPP) contributions of $20.00 deducted from each pay. Calculate Ursula's net federal taxable income.
Answer:
Explanation:
$712.00
Explanation:
For payroll income tax purposes, net taxable income starts with the employee's gross taxable income and then subtracts only those deductions that are deductible for income tax and can be recognized at source. CRA payroll guidance shows this approach by subtracting items such as RPP contributions and union dues when determining net taxable income for calculating income tax deductions.
Gross taxable income (weekly): $750.00.
RPP contributions are deductible (the amounts reported from box 20 of the T4 are generally deductible).
Regular union dues are deductible; however, the CRA states that deductible annual union/professional dues do not include special assessments or charges for anything other than ordinary operating costs. A levy specifically for constructing a new union hall is a special assessment, so it is not deductible as union dues.
So the deductions that reduce federal taxable income here are: $18.00 (union dues) + $20.00 (RPP) = $38.00.
Net federal taxable income = $750.00 # $38.00 = $712.00.
NEW QUESTION # 76
......
By choosing a good training site, you can achieve remarkable results. VCEPrep has committed to provide all real National Payroll Institute PF1 practice tests. VCEPrep National Payroll Institute PF1 exam dumps authorized by the supplier, with wide coverage can save a lot of time for you. Guarantee your success in the first attempt. If you do not pass the National Payroll Institute Business Solutions PF1 Exam on your first attempt we will give you a FULL REFUND of your purchasing fee. Failing an Exam won't damage you financially as we provide 100% refund on claim.
PF1 Valid Test Discount: https://www.vceprep.com/PF1-latest-vce-prep.html
P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by VCEPrep: https://drive.google.com/open?id=1OJbgFJYt1BnFRk398Tnfw6RXUpYLqcJV