AFP-Exam-1トレーニング資料は、ユーザーが学習した内容を統合し、多くのトレーニングの瞬間に追加するのに役立つように設計されています。ユーザーは、学習コンテンツの一部を終えた後、学習効果を時間内にテストできます。 AFP-Exam-1ガイドトレントのトピックを使用して、ユーザーがこの機能の知識の弱点を見つけ、一定の練習を繰り返して、最終的に高い成功率を達成できるようにします。その結果、当社のAFP-Exam-1試験問題は、ユーザーがAFP-Exam-1試験に合格するための知識を習得できるように、実践内容の完全なセットを形成するように設計されています。
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Risk Management and Insurance | 12% | - Risk Transfer Strategies - Life Insurance - Risk Assessment - Disability and Health Insurance |
| Topic 2: Estate Planning | 13% | - Wills - Trust and Beneficiary Planning - Powers of Attorney - Estate Transfer Strategies |
| Topic 3: Professional Conduct and Regulatory Compliance | 10% | - Compliance Responsibilities - Ethics and Professional Standards - Regulatory Requirements |
| Topic 4: Client Relationship and Practice Management | 6% | - Practice Management - Communication and Advisory Process - Client Discovery |
| Topic 5: Investment Planning | 17% | - Asset Allocation - Portfolio Construction - Investment Theory - Investment Products |
| Topic 6: Retirement Planning | 17% | - Registered Retirement Savings Plans - Pension Plans - Retirement Income Strategies - Retirement Needs Analysis |
| Topic 7: Tax Planning | 14% | - Tax Deductions and Credits - Tax-Efficient Strategies - Registered Plans - Income Tax Fundamentals |
| Topic 8: Asset and Liability Management | 11% | - Debt Management - Cash Flow Management - Budgeting - Personal Balance Sheet Analysis |
AFP-Exam-1試験に問題がある場合は、無料のデモを検討してください。弊社の最新のAFP-Exam-1試験トレントは、この業界では完璧な模範であり、さまざまな程度の試験受験者向けの明確なコンテンツに満ちています。最新のAFP-Exam-1試験トレントの結果は驚くほど驚くべきもので、試験受験者の98%以上が目標を無事に達成しました。また、AFP-Exam-1テストダンプにより、あらゆる種類の教材の精度が非常に高いことが保証されました。
質問 # 111
What key question should be answered during the recommending strategies stage of the financial planning process?
正解:B
解説:
The recommending strategies stage answers the practical question: how can the client achieve the goals? At this point, the planner has already clarified needs and objectives, gathered data, analyzed the current position, and assessed feasibility. The recommendation stage converts that analysis into strategies such as debt repayment, insurance coverage, asset allocation, tax planning, retirement contributions, or estate actions.
Option B, feasibility, belongs mainly to the analysis stage. Option C, identifying needs and goals, belongs to discovery. Option D, compensation disclosure, belongs at engagement and relationship disclosure. AFP planning is sequential: define the relationship, collect information, analyze, develop recommendations, implement, and monitor. The tested wording points to strategy development, so option A is the only answer that fits the stage. Study Guide focus: financial planning process, strategy recommendation, goal implementation, client engagement, and planning workflow. This stage should produce actionable recommendations, responsible parties, and enough detail for the client to approve implementation.
質問 # 112
Which assets will flow through an estate?
正解:D
解説:
Estate administration begins with ownership form. A joint tenancy with right of survivorship normally passes directly to the survivor, while an inter vivos trust owns the property outside the deceased's personal estate and a properly funded buy-sell arrangement directs business continuity through contract. Tenancy in common is different: each owner holds a separate, divisible interest. On death, that interest does not disappear and does not vest automatically in the other co-owner. It is property of the deceased and is administered under the will or, if there is no valid will, under intestacy legislation. For AFP purposes, the tested distinction is probate exposure versus survivorship or beneficiary transfer. The asset described in option B is therefore the one that flows through the estate. Study Guide focus: estate ownership, survivorship, trusts, probate property, and estate administration. This distinction is central when determining executor authority, probate value, and whether an asset bypasses estate administration by contract or title.
質問 # 113
Henry, age 48, has been working for Bac Inc, which is a federally regulated corporation, for over eight years.
He is looking to retire at age 50 and has decided to take the commuted value of his pension: $450,000, electing to transfer the eligible remainder to his RRSP (Income Tax Act maximum pension benefit transfer value of $210,000). Henry estimates he would need $1,800 (pre-tax every month) from his registered investments to meet his retirement income goal and is looking to maximize his RRSP contribution room.
Assume no inflation, an average tax rate of 15%, an unused RRSP contribution room of $90,000, and a life expectancy to age 90. What would be the required rate of return to meet Henry's goals?
正解:C
解説:
Henry's required rate of return is approximately 6.71%. He is retiring at age 50 and expects to need $1,800 per month before tax from registered investments until age 90, a 40-year income period. Of the $450,000 commuted value, $210,000 can be transferred under the Income Tax Act maximum pension transfer rule, and he has $90,000 of unused RRSP contribution room. That gives $300,000 of registered capital available for the retirement-income objective. Solving the present-value annuity problem for $1,800 monthly withdrawals over
480 months produces a monthly return that annualizes to about 6.71%. Option D is too low to sustain the withdrawals. Options A and B require more return than the calculation supports. The planner should also discuss inflation, locked-in restrictions, taxation, investment risk, and the danger of relying on a single return assumption. Study Guide focus: commuted values, RRSP room, locked-in transfers, annuity math, and retirement income sustainability.
質問 # 114
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: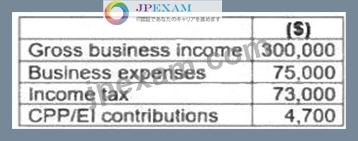
What is Terry's net business income?
正解:C
解説:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
質問 # 115
Ram Patel, age 65, is meeting with his financial planner, Maria Romano, to complete a financial plan. Ram is retiring this year, and his company provides a defined benefit pension plan. Upon retirement, he has the choice of receiving $20,000 each year for 20 years or until death (whichever is earlier), or he can take
$304,300, which is the commuted value at retirement. Ram has confirmed that he will be transferring the commuted value to a LIRA. After further discovery, Maria suggests that they utilize a 5% market rate of return and project the funds to last 25 years. What should Maria update Ram's projected annual retirement income to?
正解:A
解説:
Maria should update Ram's projected retirement income to approximately $21,591. The commuted value is
$304,300, and Ram will transfer it to a LIRA. Using a 5% annual market return over a 25-year payout period, the annuity-style payment calculation is based on amortizing the capital over the projection period. The annual payment is calculated as present value multiplied by the discount rate factor: $304,300 × 0.05 divided by 1 minus 1.05 to the negative 25. The result is approximately $21,591 per year. Option B is simply the original pension option and ignores the commuted-value projection. Option D is a rough estimate, and option A overstates the sustainable annual amount. AFP retirement analysis requires consistent assumptions for rate of return, payout period, and income timing before comparing pension alternatives. Study Guide focus:
pension commuted values, LIRA transfers, retirement income projections, present value, and annuity calculations. The comparison should also recognize that a projected LIRA withdrawal stream is not the same guarantee as a pension promise.
質問 # 116
......
実際のAFP-Exam-1試験では常に緊張しており、実際の試験に適応するのは難しいと感じていますか? 「はい」と答えた場合、AFP-Exam-1試験クイズのソフトウェアバージョンを使用してみてください。 ソフトウェアバージョンは実際のテスト環境をシミュレートできるため、AFP-Exam-1試験ガイドのソフトウェアバージョンが最適です。ソフトウェアバージョンごとにAFP-Exam-1試験の雰囲気を事前に感じることができます。
AFP-Exam-1ウェブトレーニング: https://www.jpexam.com/AFP-Exam-1_exam.html