P.S. Free & New AFP-Exam-1 dumps are available on Google Drive shared by PracticeDump: https://drive.google.com/open?id=1iI--Bc1EZiZ6hY7-G-ny8whDCXySSTjp
With the help of the CSI AFP-Exam-1 brain dumps and preparation material provided by PracticeDump, you will be able to get AFP-Exam-1 certified at the first attempt. Our experts have curated an amazing AFP-Exam-1 exam guide for passing the AFP-Exam-1 exam. You can get the desired outcome by preparing yourself from the AFP-Exam-1 Exam Dumps material provided by PracticeDump. We frequently update our AFP-Exam-1 exam preparation material to reflect the latest changes in the AFP-Exam-1 exam syllabus.
| Section | Objectives |
|---|---|
| Retirement Planning | - Retirement savings vehicles and planning principles |
| Taxation Concepts | - Personal income tax principles - Tax-efficient investment strategies |
| Investment Planning | - Asset allocation and portfolio basics - Investment products and risk-return profiles |
| Insurance and Risk Management | - Life and health insurance fundamentals - Risk mitigation strategies in financial planning |
| Financial Planning Foundations | - Financial planning process and client relationship management - Ethics and professional standards in financial advising |
>> CSI AFP-Exam-1 Pass Guaranteed <<
One more thing to give you an idea about the top features of Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam questions before purchasing, the PracticeDump are offering free CSI AFP-Exam-1 Exam Questions demo download facility. This facility is being offered in all three CSI AFP-Exam-1 exam practice question formats.
NEW QUESTION # 16
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: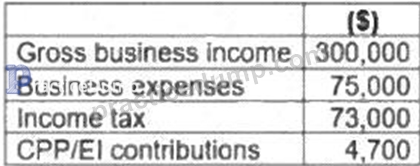
What is Terry's net business income?
Answer: A
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 17
In which life cycle stage would a financial planner identify his client to be if they have a high mortgage balance and an unstable or lower income, and are willing to take on investment risk because of their longer time horizon?
Answer: D
Explanation:
The accumulation stage is characterized by asset building while major liabilities and career uncertainty may still exist. Clients in this stage often have mortgages, young families or early career responsibilities, and a long time horizon before retirement. Because the investment horizon is long, they may be able to accept more growth exposure, provided cash flow, emergency reserves, and debt servicing are under control. The consolidation stage usually occurs later, when income is stronger, debts are falling, and retirement funding accelerates. Financial independence refers to clients who can maintain lifestyle without employment income.
Gifting generally occurs after core lifetime needs are secure and surplus wealth can be transferred. The scenario states high mortgage balance, unstable or lower income, and willingness to take investment risk due to a long horizon; that is the accumulation phase. Study Guide focus: client life-cycle stages, risk capacity, accumulation planning, mortgage debt, and time horizon. Insurance planning and emergency reserves are usually reviewed alongside investments because human-capital protection is critical in this stage.
NEW QUESTION # 18
Jonathan owns a medium size consulting firm and earns an average annual income of $150,000. He is reviewing his retirement plan with his financial planner. Jonathan asked his planner about retirement compensation arrangement and how this may benefit him. What should his financial planner tell him?
Answer: B
Explanation:
A retirement compensation arrangement can benefit an executive because it does not use RRSP contribution room and is not subject to the ordinary registered pension and RRSP contribution limits. It is an employer- sponsored supplemental retirement arrangement often used where standard registered plan limits are insufficient for high-income employees or owner-managers. Withdrawals are not tax-exempt; benefits are generally taxable when received, so option A and option C misstate the tax treatment. Option D incorrectly says it reduces RRSP room. RCAs are also subject to refundable tax mechanics and require careful administration, so the planner should not present them as simple savings accounts. Jonathan's planner should explain that the value is supplemental retirement funding above regular limits, balanced against cost, complexity, cash-flow needs, and tax timing. Study Guide focus: retirement compensation arrangements, executive benefits, RRSP contribution room, supplemental pensions, and tax deferral. The planner should also explain that RCAs are complex and usually suited only where the employer can fund the arrangement.
NEW QUESTION # 19
Mary, an accredited financial planner, recently met with clients Michael and Radha. They are high- net-worth clients who are in their mid-40s. Michael is a heavy equipment operator at a local oil field, and Radha is a homemaker. They are ready to retire in 10 years and very excited to start planning for the next chapter in their lives. Mary explained her planning process, her accreditation, and her remuneration. When Mary presented the client agreement letter, both clients were surprised. They said they did not know why they would sign a letter to get advice on their own finances. How should Mary answer their question?
Answer: A
Explanation:
Mary should explain that the client agreement letter is the engagement document for the advisory relationship.
It confirms what services will be provided, the scope of planning, the roles and responsibilities of the clients and planner, how the planner is compensated, and any limitations or business arrangements that matter to the relationship. It is not the investment strategy itself; that comes after discovery, analysis, and recommendations. It is also not merely an informal or irrelevant bank form. A well-written engagement letter protects the clients because it tells them what they can expect, what information they must provide, and how decisions will be documented. For high-net-worth clients, clarity is even more important because multiple planning areas, specialists, and implementation steps may be involved. Mary should position the letter as a professional standard, not as a barrier to advice. Study Guide focus: engagement letters, financial planning process, client expectations, disclosure, and practice management.
NEW QUESTION # 20
Henry, age 48, has been working for Bac Inc, which is a federally regulated corporation, for over eight years.
He is looking to retire at age 50 and has decided to take the commuted value of his pension: $450,000, electing to transfer the eligible remainder to his RRSP (Income Tax Act maximum pension benefit transfer value of $210,000). Henry estimates he would need $1,800 (pre-tax every month) from his registered investments to meet his retirement income goal and is looking to maximize his RRSP contribution room.
Assume no inflation, an average tax rate of 15%, an unused RRSP contribution room of $90,000, and a life expectancy to age 90. What would be the required rate of return to meet Henry's goals?
Answer: C
Explanation:
Henry's required rate of return is approximately 6.71%. He is retiring at age 50 and expects to need $1,800 per month before tax from registered investments until age 90, a 40-year income period. Of the $450,000 commuted value, $210,000 can be transferred under the Income Tax Act maximum pension transfer rule, and he has $90,000 of unused RRSP contribution room. That gives $300,000 of registered capital available for the retirement-income objective. Solving the present-value annuity problem for $1,800 monthly withdrawals over
480 months produces a monthly return that annualizes to about 6.71%. Option D is too low to sustain the withdrawals. Options A and B require more return than the calculation supports. The planner should also discuss inflation, locked-in restrictions, taxation, investment risk, and the danger of relying on a single return assumption. Study Guide focus: commuted values, RRSP room, locked-in transfers, annuity math, and retirement income sustainability.
NEW QUESTION # 21
......
PracticeDump is a very good website to provide a convenient service for the CSI certification AFP-Exam-1 exam. PracticeDump's products can help people whose IT knowledge is not comprehensive pass the difficulty CSI certification AFP-Exam-1 exam. If you add the CSI Certification AFP-Exam-1 Exam product of PracticeDump to your cart, you will save a lot of time and effort. PracticeDump's product is developed by PracticeDump's experts' study of CSI certification AFP-Exam-1 exam, and it is a high quality product.
AFP-Exam-1 Pdf Braindumps: https://www.practicedump.com/AFP-Exam-1_actualtests.html
2026 Latest PracticeDump AFP-Exam-1 PDF Dumps and AFP-Exam-1 Exam Engine Free Share: https://drive.google.com/open?id=1iI--Bc1EZiZ6hY7-G-ny8whDCXySSTjp