P.S. Free 2026 Guidewire ClaimCenter-Business-Analysts dumps are available on Google Drive shared by PassSureExam: https://drive.google.com/open?id=16c4WCdYjbs-zPN5EOFnHlxR5HLaQ3s1d
In order to make the ClaimCenter-Business-Analysts exam easier for every candidate, PassSureExam compiled such a wonderful ClaimCenter-Business-Analysts study materials that allows making you test and review history performance, and then you can find your obstacles and overcome them. In addition, once you have used this type of ClaimCenter-Business-Analysts Exam Question online for one time, next time you can practice in an offline environment. It must be highest efficiently exam tool to help you pass the ClaimCenter-Business-Analysts exam.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
>> Latest ClaimCenter-Business-Analysts Test Cram <<
Everything is difficult at beginning. When you are distressed about how to start your ClaimCenter-Business-Analysts exam preparation, maybe to purchase our ClaimCenter-Business-Analysts exam software is indispensable for your to first prepare for your ClaimCenter-Business-Analysts exam. What we provide is what you want to attend ClaimCenter-Business-Analysts Exam necessarily. You may hesitate whether to purchase our dump or not; don't worry, you can download our free demo of ClaimCenter-Business-Analysts exam software. After you have tried our free demo, you will be sure to choose our ClaimCenter-Business-Analysts exam software.
NEW QUESTION # 26
Succeed Insurance has a requirement to add a new high-risk indicator to the Claim Status screen for property claims that have a lien on the property. A new icon will be added to the configuration to provide a visual indicator making it easier for Adjusters and other ClaimCenter users to determine that a claim has a lien.
Which two common areas of the user interface (UI) can display the new lien icon? (Choose two.)
Answer: B,E
Explanation:
In the standard Guidewire ClaimCenter User Interface architecture, high-priority alerts and claim indicators are displayed in two primary locations to ensure visibility:
* The Info Bar (Option D):This is the persistent strip located at the top of the claim file (just below the Tab Bar). It remains visible regardless of which specific claim sub-screen (Medical, Financials, Notes) the user is navigating. It is designed specifically to host "High Risk Indicators" such as Litigation, Fatalities, Coverage issues, and in this scenario, a "Lien" indicator. This ensures the adjuster is aware of the critical status immediately upon opening the claim.
* The Screen Area (Option A):Specifically, theClaim Status(or Summary) screen-which resides in the main Screen Area-contains a dedicated section for "Claim Indicators." Here, the icon is displayed along with a text description and potential toggle status (On/Off). The prompt explicitly mentions the requirement to "add a new high-risk indicator to the Claim Status screen," confirming the Screen Area as the second location.
Why other options are incorrect:
* Sidebar (B):The sidebar (left panel) is used for the "Actions" menu and navigation links (steps) to move between screens. It does not typically host status icons for the claim object itself.
* Workspace (C):While "Workspace" can refer to the application frame, in UI terminology, it often refers to the specific worksheets (bottom pane) or the container, not the specific UI element for indicators.
* Tab Bar (E):The Tab Bar is for high-level navigation (Claim, Desktop, Administration, Search) and does not display claim-specific data icons.
NEW QUESTION # 27
Succeed Insurance is implementing a slightly modified version of ClaimCenter to suit its organization's needs.
The modification will include adding two new required fields to the standard user interface to capture the reporter's Preferred Language and Preferred Contact Time. This requirement is critical for Succeed to improve efficiency and the expediency of claims processing in its region.
Under which ClaimCenter theme will the User Story Card be found for documenting these requirements?
Answer: B
Explanation:
In the Guidewire implementation methodology, User Stories are categorized into Themes that align with the high-level business processes of the claim lifecycle.
* Intake (Option A):TheIntaketheme covers theFirst Notice of Loss (FNOL)process and the "New Claim Wizard." The requirement specified is to capture data regarding the "Reporter" (the person reporting the loss) and their contact preferences. In ClaimCenter, Reporter information is collected at the very beginning of the New Claim Wizard (Step 1: Search/Create Policy and Reporter). Because this data entry occurs during the initial setup of the claim, the User Story governing these UI changes belongs to theIntaketheme.
* Context:Improving "expediency of claims processing" often relies on accurate data capture at the Intake stage so that downstream assignment and communication can be handled correctly from the start.
Why other options are incorrect:
* Adjudicate (B):This theme covers the investigation, evaluation, and negotiation phases that occurafter the claim is created.
* Settle/Close (D):This theme covers the payment issuance and final closure of the file.
* Special Services (C):This typically refers to Vendor Management or specialized sub-processes, not the core FNOL reporter data.
NEW QUESTION # 28
Which set of three objects is required to create a liability exposure?
Answer: B
Explanation:
In the Guidewire ClaimCenter object model, a Liability Exposure represents a specific potential financial obligation to a third party. To successfully instantiate (create) a new exposure record, the system requires three fundamental data associations to define "Who, What, and How":
* Claimant:The specific person or entity seeking compensation (the "Who"). Every exposure must be linked to a contact designated as the claimant.
* Coverage (Type and Subtype):The specific contractual provision from the policy that applies to the loss (the "How"). The exposure must link back to a valid coverage on the verified policy to confirm the insurer is liable.
* Incident:The specific details of the event or damage (the "What"). In ClaimCenter, anIncidentis a distinct object (e.g., Vehicle Incident, Injury Incident) that captures the facts of the loss. Multiple exposures can link to the same incident (e.g., Bodily Injury and Property Damage exposures both linking to the same Vehicle Incident), but every exposure requires one underlying incident to define the scope of the damage.
Why other options are incorrect:
* Reserve Line (A, C, D):A Reserve Line is a financial accounting object createdafterthe exposure exists to set aside funds. It is a child object of the exposure, not a prerequisite for creating the exposure itself.
NEW QUESTION # 29
An Adjuster at Succeed Insurance is handling a personal auto claim for an insured who hit a tree after swerving to avoid a child who ran into the road.
The Adjuster has this Authority Limit Profile: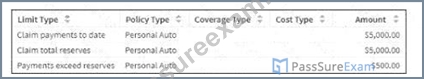
The Adjuster creates a collision exposure and sets the initial reserves so that payments can be made to the insured for repairs to the damaged vehicle. No payments have been created yet.
The current financials for the claim are as follows:
Which two financial transactions will not require approval given that each option is the only transaction change rather than a cumulative change? (Choose two.)
Answer: A,B
Explanation:
To determine if a transaction requires approval, we must compare the proposed transaction against the Adjuster's Authority Limits and the current financial state of the claim.
* Current State:Total Reserves = $3,000 ($2,500 Indemnity + $500 Expense). Total Paid = $0.
* Adjuster Limits:
* Claim Total Reserves Limit: $5,000
* Payments Exceed Reserves Limit: $500
Evaluation of Options:
* Option B (No Approval Required):Making a $2,000 payment against the "Claim Cost - Auto body" reserve.
* The available reserve is $2,500. Since $2,000 < $2,500, the payment does not exceed the reserve.
* The total payments on the claim would be $2,000, which is well below the "Claim payments to date" limit of $5,000.
* Option D (No Approval Required):Increasing the Expense reserve to $550.
* This increases the total claim reserves from $3,000 to $3,050 ($2,500 + $550).
* Since $3,050 is below the Adjuster's "Claim total reserves" limit of $5,000, no approval is triggered.
Why other options require approval:
* Option A:A payment of $1,100 against a $500 reserve means the payment exceeds the reserve by$600.
The Adjuster's limit for "Payments exceed reserves" is only$500. Since $600 > $500, approval is required.
* Option C:Increasing the Auto body reserve to $6,000 would raise the total claim reserves to$6,500 ($6,000 + $500). This exceeds the Adjuster's "Claim total reserves" limit of $5,000, triggering an approval.
NEW QUESTION # 30
A car accident in a rural area of Durango, Colorado is reported to Succeed Insurance. The driver of the damaged car reportedly hit the base of a windmill tower while driving at night. There was no other passenger in the car when the accident happened, and the driver has a valid auto policy on file.
While the driver is not physically injured, the entire passenger side of the car has been severely damaged.
Although the windmill is still functioning, the base of the tower has sustained multiple broken parts.
Which two incidents need to be created for the claim based on the reported accident? (Choose two.)
Answer: A,C
Explanation:
In Guidewire ClaimCenter, an Incident is the data object used to capture the specific facts about "what" was damaged or affected during the loss event. It serves as the foundation for creating Exposures (the financial liabilities).
* Vehicle Incident (Option C):The scenario states that the insured's car has been "severely damaged" on the passenger side. To record these facts-including the point of impact, the severity, and the vehicle description-the Adjuster must create aVehicle Incident. This incident will eventually support the collision coverage exposure.
* Property Incident (Option B):The accident involved the car hitting a "windmill tower," resulting in
"broken parts" to the base. In ClaimCenter, damage to third-party non-vehicular objects (like fences, poles, buildings, or towers) is captured using aFixed Property Incident(often referred to generically as a Property Incident). This incident records the damage description and ownership of the windmill, which is necessary to handle the Property Damage Liability claim.
Why other options are incorrect:
* Option E (Injury):The scenario explicitly states the driver is "not physically injured." Therefore, an Injury Incident is not required.
* Option A ("Another structure"):The standard object for third-party fixed property damage is the Property Incident/Fixed Property Incident, not "Another structure."
* Option D (Loss of Use):While possible later, the primary immediate damage is physical. Loss of Use is usually a secondary exposure type, not the primary incident definition for the tower itself.
NEW QUESTION # 31
......
The pass rate for ClaimCenter-Business-Analysts learning materials is 98.75%, and you can pass the exam successfully by using the ClaimCenter-Business-Analysts exam dumps of us. We also pass guarantee and money back guarantee if you fail to pass the exam, and the refund money will be returned to your payment account. The ClaimCenter-Business-Analysts Learning Materials are famous for their high-quality, and if you choose, they can not only improve your ability in the process of learning but also help you get the certificate successfully. Choose us, and you will never regret.
Valid Exam ClaimCenter-Business-Analysts Vce Free: https://www.passsureexam.com/ClaimCenter-Business-Analysts-pass4sure-exam-dumps.html
BONUS!!! Download part of PassSureExam ClaimCenter-Business-Analysts dumps for free: https://drive.google.com/open?id=16c4WCdYjbs-zPN5EOFnHlxR5HLaQ3s1d