Briefly speaking, our AFP-Exam-1 training guide gives priority to the quality and service and will bring the clients the brand new experiences and comfortable feelings. For we have engaged in this career for years and we are always trying our best to develope every detail of our AFP-Exam-1 study quiz. With our AFP-Exam-1 exam questions, you will find the exam is just a piece of cake. What are you still hesitating for? Hurry to buy our AFP-Exam-1 learning engine now!
| Section | Objectives |
|---|---|
| Topic 1: Retirement Planning | - Retirement savings vehicles and planning principles |
| Topic 2: Investment Planning | - Investment products and risk-return profiles - Asset allocation and portfolio basics |
| Topic 3: Insurance and Risk Management | - Risk mitigation strategies in financial planning - Life and health insurance fundamentals |
| Topic 4: Taxation Concepts | - Tax-efficient investment strategies - Personal income tax principles |
| Topic 5: Financial Planning Foundations | - Financial planning process and client relationship management - Ethics and professional standards in financial advising |
>> Test AFP-Exam-1 Questions <<
PassTestking also has a CSI Practice Test engine that can be used to simulate the genuine AFP-Exam-1 exam. This online practice test engine allows you to answer questions in a simulated environment, giving you a better understanding of the exam's structure and format. With the help of this tool, you may better prepare for the Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) test.
NEW QUESTION # 65
Jenny and Herman are looking for tax strategies that will help them better manage their marginal annual tax rates. Jenny is currently the primary income earner in the household. She has a large non-registered portfolio that holds only plain vanilla S & P 500 index funds. Jenny and Herman have a 14-year-old daughter, and they would also like to know what income-splitting opportunities exist. They've presented several ideas to their tax planner, Isaac, for review. Which of the following will likely result in tax attribution to Jenny?
Answer: D
Explanation:
Jenny's gift to her minor daughter is the transaction most likely to trigger attribution back to Jenny. When a high-income parent transfers income-producing property to a minor child, income such as interest and dividends generally attributes back to the parent. The rule prevents simple income splitting by gift. A spousal RRSP converted to a RRIF can avoid attribution on required minimum RRIF withdrawals, subject to detailed timing rules. A sale of securities to Herman at fair market value can avoid attribution if proper consideration is paid and the transaction is documented. A prescribed-rate loan to Herman can also avoid attribution if interest is charged at the prescribed rate and paid by the required deadline. The key AFP issue is distinguishing prohibited income splitting from properly structured transfers or loans. The minor-child gift in option A is the clearly attributive arrangement. Study Guide focus: attribution rules, minor children, spousal transfers, prescribed-rate loans, and family tax planning.
NEW QUESTION # 66
John and Jerry's financial planner have recommended they review their budget. What is the primary purpose of the budget?
Answer: C
Explanation:
A budget is primarily a cash-flow planning tool. It identifies the client's expected inflows and outflows over a defined period and shows whether spending, debt servicing, taxes, insurance premiums, and savings are sustainable. Expense reduction and savings-plan design may result from the budget review, but they are not the primary purpose of the budget itself. Total debt service is a borrowing-capacity ratio, not the purpose of a household budget. A budget also helps compare planned spending with actual results, isolate discretionary expenses, and create accountability for future behaviour. In AFP practice, the planner uses the budget as the bridge between goals and implementation: retirement savings, debt repayment, emergency funding, insurance affordability, and investment contributions all depend on cash-flow capacity. Therefore, option A is the most precise answer. Study Guide focus: budgeting, cash-flow analysis, spending management, debt capacity, and savings discipline. Without this baseline, later advice on borrowing, savings, or insurance premiums becomes speculative and weakly supported.
NEW QUESTION # 67
A client asks when his RRSP must generally be converted to a retirement income vehicle. What should the planner explain?
Answer: D
Explanation:
RRSP maturity is age-based. In general, an RRSP must be converted to a retirement income option, such as a RRIF or annuity, by the end of the calendar year in which the annuitant turns 71. Minimum RRIF withdrawals begin the following year if a RRIF is selected. Option B confuses eligibility for some retirement benefits and pension planning milestones with RRSP maturity. Option C is wrong because employment status does not eliminate the conversion requirement. Option D is not required and may be tax-inefficient; a full cash withdrawal could trigger substantial taxable income. A planner should treat conversion as a planning decision, not an administrative afterthought. The client's spouse's age, required income, tax bracket, pension splitting, investment mix, estate goals, and OAS exposure may influence whether to use a RRIF, annuity, or combination. The correct exam answer is the age-71 year-end deadline. References/topics: RRSP maturity, RRIF conversion, annuities, retirement income planning.
NEW QUESTION # 68
A planner establishes a long-term target portfolio of 65% equities and 35% fixed income based on the client's objectives and constraints, with periodic rebalancing. Which allocation approach is being used?
Answer: A
Explanation:
Strategic asset allocation begins with the client's planning profile and sets a long-term benchmark mix intended to meet return objectives within acceptable risk. The mix is periodically reviewed and rebalanced when market movements or client circumstances cause drift. Option A is incorrect because market timing attempts to shift exposure based on predictions about near-term market direction. Option B involves deliberate short-term departures from the strategic benchmark to exploit perceived opportunities. Option C is not a disciplined planning method; speculation emphasizes high-risk bets rather than objectives-based portfolio construction. A course-style explanation should connect the allocation to the client's time horizon, risk tolerance, risk capacity, liquidity requirements, tax position, and investment constraints. Rebalancing is part of governance: it prevents a successful asset class from quietly increasing portfolio risk beyond the client' s mandate. Strategic allocation is therefore both an investment decision and a suitability control. References
/topics: strategic asset allocation, portfolio policy, rebalancing, risk control.
NEW QUESTION # 69
Justis, age 62, and his wife Jen, age 58, are meeting with their financial planner, Luke. They are both planning to retire by age 65. Their goals are to minimize debt and reduce taxes. The couple's financial situation is outlined below.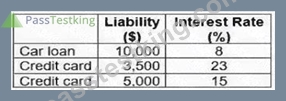
Justis' annual income is $25,000. He has a $15,000 RRSP, $30,000 single non-registered account and a
$25,000 TFSA. Jen's annual income is $60,000, and she has a $150,000 RRSP, $50,000 single non-registered account and a $20,000 TFSA.
Jen's marginal tax rate is 35%, and Justis' is 25%. Assuming all investments are making interest income of
10%, what would be the most appropriate strategy for Luke to recommend for the couple?
Answer: B
Explanation:
Luke should recommend using Jen's non-registered funds because that option clears the liabilities without triggering registered-plan withdrawal income. The debts total $18,500 and include expensive consumer borrowing: credit cards at 23% and 15%, plus a car loan at 8%. The couple's taxable investments earn 10% interest before tax, so Jen's after-tax return is approximately 6.5% at a 35% marginal rate. Paying the credit cards is equivalent to earning a risk-free after-tax return equal to the interest avoided, which is materially better than leaving the money invested. Using either spouse's RRSP would create taxable income and permanently reduce retirement capital. Using Justis's non-registered funds is less effective because his lower tax rate makes his after-tax investment return higher than Jen's, so Jen's taxable account is the better source.
Study Guide focus: debt repayment priority, after-tax returns, registered versus non-registered withdrawals, and household cash-flow planning. The recommendation also preserves retirement accounts for the couple's age-65 objective while eliminating the highest-cost liabilities first.
NEW QUESTION # 70
......
Under the hatchet of fast-paced development, we must always be cognizant of social long term goals and the direction of the development of science and technology. Adapt to the network society, otherwise, we will take the risk of being obsoleted. Our Applied Financial Planning Certification Exam 1 (AFP) qualification test help improve your technical skills and more importantly, helping you build up confidence to fight for a bright future in tough working environment. Our professional experts devote plenty of time and energy to developing the AFP-Exam-1 Study Tool. You can trust us and let us be your honest cooperator in your future development. Here are several advantages about our Applied Financial Planning Certification Exam 1 (AFP) exam for your reference. We sincere suggest you to spare some time to have a glance over the following items.
AFP-Exam-1 Latest Real Test: https://www.passtestking.com/CSI/AFP-Exam-1-practice-exam-dumps.html