P.S. Free 2026 IFSE Institute LLQP dumps are available on Google Drive shared by BraindumpStudy: https://drive.google.com/open?id=1Pqai36bvJg4She4W3cVjeuV6DwffT7mm
With these two Life License Qualification Program (LLQP) LLQP practice exams, you will get the actual IFSE Institute LLQP exam environment. Whereas the BraindumpStudy PDF file is ideal for restriction-free test preparation. You can open this PDF file and revise LLQP Real Exam Questions at any time. Choose the right format of Life License Qualification Program (LLQP) LLQP actual questions and start IFSE Institute LLQP preparation today.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
Latest IFSE Institute LLQP Dumps are here to help you to pass your IFSE Institute Certification exam with BraindumpStudy' valid, real, and updated LLQP Exam Questions with passing guarantee. The IFSE Institute LLQP certification is a valuable certificate that is designed to advance the professional career. With the Life License Qualification Program (LLQP) (LLQP) certification exam seasonal professionals and beginners get an opportunity to demonstrate their expertise. The Life License Qualification Program (LLQP) exam recognizes successful candidates in the market and provides solid proof of their expertise.
NEW QUESTION # 28
Disappointed with the performance of his current investments, Gerard wants to make changes to his portfolio.
While his investments are well diversified and professionally managed (as he requested from the outset), their value fluctuates significantly up and down. The issue is that Gerard, a professional stuntman, often puts his life on the line. Should he die, he would like the capital in his investments to be protected as much as possible-if not in whole, then at least a good portion-which is not currently the case.
What type of investment would be most suitable for Gerard?
Answer: D
Explanation:
According to the LLQP Segregated Funds and Annuities curriculum, investment suitability must take into account not only risk tolerance and diversification, but also personal circumstances and specific protection needs. Gerard's situation clearly highlights a need for capital protection upon death, given the high-risk nature of his occupation as a professional stuntman.
Although Gerard's current investments are diversified and professionally managed, the significant market fluctuations indicate exposure to market risk without any guarantees. Traditional investments such as stocks, mutual funds, and exchange-traded funds (ETFs) do not provide any contractual protection of capital. Their value depends entirely on market performance, and in the event of the investor's death, beneficiaries receive only the market value at that time, regardless of prior contributions.
Segregated funds, however, are uniquely suited to Gerard's needs. As outlined in the LLQP study guide, segregated funds are insurance contracts that combine market-based investing with built-in guarantees. One of their most important features is the death benefit guarantee, which typically protects 75% or 100% of the original deposits (less withdrawals) if the investor dies before maturity. This directly addresses Gerard's concern about ensuring that a substantial portion of his invested capital is preserved for his beneficiaries, even if markets are down at the time of death.
In addition, segregated funds offer professional management and diversification similar to mutual funds, which Gerard already values. They also provide potential estate planning benefits such as bypassing probate and faster payment to beneficiaries, which are emphasized in the LLQP curriculum as key advantages for clients with higher personal risk exposure.
Options A, B, and D are unsuitable because none of these investments offer contractual death benefit protection. While diversification can reduce volatility, it does not guarantee capital preservation upon death.
Therefore, based on LLQP Segregated Funds and Annuities principles, the most suitable investment for Gerard is segregated funds, making Option C the correct and fully verified answer.
NEW QUESTION # 29
Naomie meets with her new client, Keisha, to review her investment portfolio. Keisha is a 43-year-old sales representative who has been with Belmont Inc., a large pharmaceutical company, for 15 years. She earns a generous salary, plus bonuses. She also has a group tax-free savings account (TFSA) and a defined contribution pension plan (DCPP), all of which are invested in Belmont common shares.
What main need does Naomie have to address regarding Keisha's investments?
Answer: B
Explanation:
Keisha's investment portfolio is highly concentrated in Belmont Inc. common shares, which include her TFSA and defined contribution pension plan (DCPP). This significant exposure to a single company's stock poses a risk because the value of her investments is directly tied to the financial performance of Belmont Inc.
Diversification is a key strategy to mitigate risk by spreading investments across various asset classes, industries, or geographic regions. This can reduce the impact of poor performance in any one area on the overall portfolio. According to LLQP content, one of the primary goals in managing an investment portfolio is to ensure appropriate diversification to avoid over-reliance on a single asset or asset type.
While other needs, like liquidity and emergency fund savings, are important, Keisha's immediate concern should be diversification. Her current investments do not provide adequate protection against company- specific risks, such as the potential downturns specific to Belmont Inc. This aligns with LLQP principles, which emphasize diversification as a way to manage risk effectively and achieve a more stable financial outcome.
NEW QUESTION # 30
Zaid married Baheya five years ago in Montreal. A year later, Zaid purchased two individual term-life insurance policies, one on his life and the second on Baheya's life, each with a death benefit of $250,000. The marriage didn't last long, and the couple divorced shortly thereafter. Baheya went on to marry Omar, and the new couple had a baby together, named Darwish.
Last week, Baheya died in a car accident. While settling her estate, Omar discovered that no beneficiary was designated on Baheya's life insurance policy.
To whom will Baheya's death benefit be paid?
Answer: B
Explanation:
In the absence of a designated beneficiary, the proceeds of a life insurance policy are generally paid to the estate (succession) of the deceased, in this case, Baheya. Quebec law stipulates that without a specific beneficiary, the policy death benefit becomes part of the deceased's estate and is distributed according to her will or intestate succession laws. Since Baheya did not name a beneficiary, the death benefit will be managed within her estate rather than automatically passing to Zaid, Omar, or their child.
NEW QUESTION # 31
Samir applied for a life insurance policy 18 months ago. At the time of the application, he was employed as an accountant. Samir quit his accounting job 6 months ago to become a professional scuba diver.
Which of the following statements about Samir's life insurance policy is CORRECT?
Answer: A
Explanation:
In life insurance policies, once the policy is issued, the insured does not need to notify the insurer of any changes in occupation. The premiums and coverage are based on the occupation and risk profile at the time of application, and life insurance contracts do not generally require updates on occupational changes unless explicitly stated.
Therefore, regardless of Samir's current job as a scuba diver, his life insurance policy remains in force without the need for notification to the insurer. This is different from disability insurance, which may consider occupation changes to reassess risk and benefits.
NEW QUESTION # 32
Jasper is the sole breadwinner in his family. His wife Stephanie has chosen to dedicate all of her time to raising their 3 young children. Luckily, Jasper earns a monthly after-tax income of $25,000 working as a family doctor in the local clinic. Jasper meets with his insurance agent Odda to purchase a life insurance policy that will ensure his family will be able to continue toenjoy their current lifestyle in the event of his death. If his average tax rate is 40% and the investment return is 4%, how much life insurance should Jasper purchase based on the income replacement approach?
Answer: A
Explanation:
The income replacement approach calculates the amount of life insurance needed to replace Jasper'safter-tax income for his dependents over a given period, accounting for an investment return. To maintain the family's current lifestyle, we need to determine the capital required to generate a monthly after-tax income of $25,000.
Calculate the Annual Income Needed:Monthly income required: $25,000Annual income required: $25,000 ×
12 = $300,000
Adjust for Tax:Since Jasper's income needs to be replaced at a pre-tax level with a tax rate of 40%, his gross income requirement is calculated as follows:
A close-up of a math Description automatically generated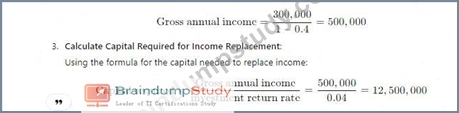
Thus, Jasper needs a life insurance policy worth$12,500,000to replace his income, allowing his family to maintain their lifestyle with a 4% investment return. This calculation aligns with LLQP principles, ensuring that the income replacement fully addresses both current lifestyle needs and tax implications.
NEW QUESTION # 33
......
We should keep the better attitude in the face of difficulties. Although IFSE Institute LLQP Exam is difficult, you should also keep the heart good. BraindumpStudy IFSE Institute LLQP test questions and test answers can help you to put through this test. The passing rate is 100%. If you fail, FULL REFUND is allowed. After you purchase our product, we offer free update service for one year. Easy and convenient way to buy: Just two steps to complete your purchase. We will send the product to your mailbox, you only need to download e-mail attachments to get your products.
LLQP Reliable Practice Materials: https://www.braindumpstudy.com/LLQP_braindumps.html
2026 Latest BraindumpStudy LLQP PDF Dumps and LLQP Exam Engine Free Share: https://drive.google.com/open?id=1Pqai36bvJg4She4W3cVjeuV6DwffT7mm