BONUS!!! Download part of Free4Dump PF1 dumps for free: https://drive.google.com/open?id=10EzCnySL9kcLgz4QSaD73TR1yGJCdsiM
Additionally, all operating systems also support this format. The third format is the desktop PF1 Practice Exam software. It is ideal for users who prefer offline Payroll Fundamentals 1Exam (PF1) exam practice. This format is supported by Windows computers and laptops. You can easily install this software in your system to use it anytime to prepare for the examination.
| Section | Objectives |
|---|---|
| Commission Payments | - Commission payroll processing
|
| Federal Remittances | - Government remittance obligations
|
| Termination of Employment | - Termination processing
|
| Provincial Remittances | - Provincial payroll requirements
|
| Year-End Processing | - Federal and provincial year-end reporting
|
| Payroll Accounting | - Payroll accounting practices
|
| New Employee Information | - Employee setup and documentation
|
| Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
| Employment Income – Regular Earnings | - Regular payroll calculations
|
| Non-Regular Payments | - Special payroll payments
|
| Non-Statutory Deductions | - Voluntary deductions
|
| Workers’ Compensation | - Workers compensation administration
|
| Record of Employment | - ROE processing
|
In today's technological world, more and more students are taking the Payroll Fundamentals 1Exam (PF1) exam online. While this can be a convenient way to take a Payroll Fundamentals 1Exam (PF1) exam dumps, it can also be stressful. Luckily, Free4Dump's best National Payroll Institute PF1 exam questions can help you prepare for your National Payroll Institute PF1 Certification Exam and reduce your stress. If you are preparing for the Payroll Fundamentals 1Exam (PF1) exam dumps our PF1 Questions help you to get high scores in your Payroll Fundamentals 1Exam (PF1) exam.
NEW QUESTION # 11
Michael is an employee in Alberta who is paid bi-weekly and earns $1,600.00 per pay period. He has a taxable meal allowance of $30.00 per pay period. His federal and provincial TD1s on file show a claim code
2. Michael already reached the annual maximum first and second Canada Pension Plan (CPP) contributions before this pay. Calculate his total federal and provincial income taxes.
Answer:
Explanation:
(total federal + Alberta tax): $173.48
Explanation:
Taxable gross for the period = $1,600.00 + $30.00 = $1,630.00 (a taxable allowance is included in income for tax withholding).
Using CRA T4032-AB (Biweekly, 26 pay periods) with claim code 2:
Federal tax at pay $1,630 falls in the $1,619-$1,635 range # CC2 = $107.35.
Alberta provincial tax at pay $1,630 falls in the $1,628-$1,644 range # CC2 = $46.55.
Subtotal tax from the tables = $107.35 + $46.55 = $153.90.
CRA notes these tax tables build in the tax credits for CPP/EI, so when CPP is not deducted (because annual max already reached), you must increase tax withholding accordingly.
CPP that would have been deducted this pay (using CRA rates/YBE):
Pensionable = $1,630 # ($3,500/26 = $134.62) = $1,495.38; CPP (4.95% + 1.00% = 5.95%) = $88.98.
Add back missing credits: Federal 14% × 88.98 = $12.46; Alberta 8% × 88.98 = $7.12 # total $19.58.
Final total tax = $153.90 + $19.58 = $173.48.
NEW QUESTION # 12
A death benefit is a:
Answer: D
Explanation:
The CRA defines a death benefit as the gross amount of any payment made on or after the death of an employee to recognize the employee's service in an office or employment. It can be paid to a surviving spouse
/common-law partner, heir, or the estate.
This is different from amounts the employee already earned before death (for example, regular wages up to the date of death, or vacation pay that was accrued/earned). CRA guidance treats wages and employment income earned up to and including the date of death as amounts to be reported on a T4 slip, not as a death benefit.
It's also different from a life insurance payout from an insurer (which is not an employer-paid "death benefit" for payroll reporting purposes). The payroll impact is that a qualifying death benefit is generally reported as a special payment (often on a T4A), following CRA rules for deductions and reporting of death benefits.
NEW QUESTION # 13
Bonus and incentive pays are subject to which statutory deductions?
Answer: C
Explanation:
Bonuses and incentives are treated as taxable remuneration, so they are generally subject to the same core statutory deductions as regular earnings: CPP/QPP, EI, and income tax (and in Quebec, QPIP also applies when the remuneration is subject to EI). The CRA specifically notes that you must deduct EI premiums from bonuses/retroactive pay (up to the annual maximum), and the CRA's guidance for bonuses/irregular amounts uses tools (PDOC/formulas) that calculate CPP contributions, EI premiums, and income tax on these payments.
In Quebec payroll, remuneration that is subject to EI premiums is generally also subject to QPIP premiums, so bonuses/incentives that are EI-insurable are typically QPIP-insurable as well.
In the Northwest Territories and Nunavut, there is also a statutory territorial payroll tax that employers must withhold/remit where applicable, and the NWT guidance explicitly lists bonuses as part of employment income subject to payroll tax.
NEW QUESTION # 14
How many pay periods will be used to calculate insurable earnings inBlock 15Bon the Record of Employment if the employee is paidweekly?
Answer: D
Explanation:
For apaper ROE, Service Canada's ROE guidance uses a set number ofmost recent consecutive pay periods to support the reporting of insurable earnings. InBlock 15C(insurable earnings by pay period), the paper ROE provides27 fields, which allows reporting up to27 weekly pay periods(or fewer if the employee worked fewer periods).
Block15Bis thetotal insurable earningsfor the applicable number of consecutive pay periods, and for a weekly payroll this aligns with the same maximum count used on the paper ROE earnings grid-27periods.
Practically, this means payroll totals the employee's insurable earnings for thelast 27 consecutive weekly pay periodsleading up to the interruption of earnings (or the full period of employment if shorter). Using the correct number of pay periods ensures Service Canada has the right earnings history to adjudicate EI benefits accurately and reduces ROE processing issues.
NEW QUESTION # 15
National Hardware, an Ontario organization, will be terminating the employment of Emilie St. Germain on October 28, 2019, the last day of the pay period. Emilie started with National Hardware on September 19,
2007. Complete the paper Record of Employment (ROE) for Emilie based on the information provided in the following chart.
Note: Vacationable earnings already include the pay in lieu of notice.
All dates must be entered in the format DDMMYYYY.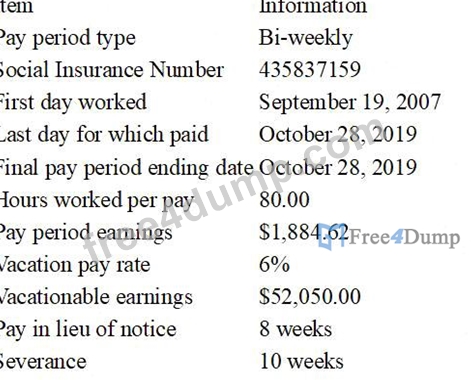
Paper ROE (Form Reference)
Complete the following paper ROE blocks for Emilie:
Block 6 - Pay period type
Block 8 - Social Insurance Number
Block 10 - First day worked
Block 11 - Last day for which paid
Block 12 - Final pay period ending date
Block 15A - Total insurable hours
Block 15B - Total insurable earnings
Block 17A - Vacation pay
Block 17C - Other monies (Pay in lieu of notice)
Block 17C - Other monies (Severance)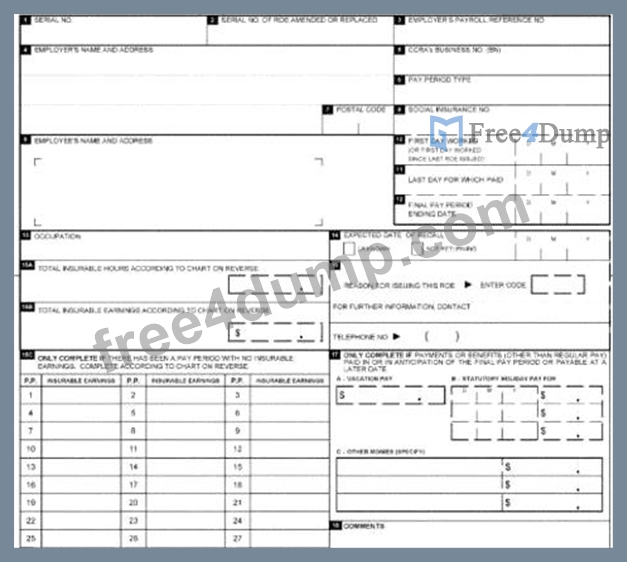
Step 1 - Complete Block 6
Enter the pay period type for Emilie.
Step 2 - Complete Block 8
Enter Emilie's Social Insurance Number.
Step 3 - Complete Block 10
Enter Emilie's first day worked in DDMMYYYY format.
Step 4 - Complete Block 11
Enter Emilie's last day for which paid in DDMMYYYY format.
Step 5 - Complete Block 12
Enter the final pay period ending date in DDMMYYYY format.
Step 6 - Complete Block 15A
Calculate and enter total insurable hours.
Given:
Hours worked per pay period = 80.00
Bi-weekly ROE pay period chart captures 27 pay periods
Step 7 - Complete Block 15B
Calculate and enter total insurable earnings.
Given:
Pay period earnings = $1,884.62
Bi-weekly ROE pay period chart captures 27 pay periods
Step 8 - Complete Block 17A
Calculate and enter vacation pay.
Given:
Vacation pay rate = 6%
Vacationable earnings = $52,050.00
(already includes pay in lieu of notice)
Step 9 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Pay in lieu of notice.
Given:
Pay in lieu of notice = 8 weeks
Use weekly earnings derived from the bi-weekly pay period earnings.
Step 10 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Severance.
Given:
Severance = 10 weeks
Use the same weekly earnings used in Step 9.
Answer:
Explanation:
See the Below Explanation for complete Solution.
Explanation:
Step 1 - Block 6
Bi-weekly
Step 2 - Block 8
435837159
Step 3 - Block 10
September 19, 2007 # 19092007
Step 4 - Block 11
October 28, 2019 # 28102019
Step 5 - Block 12
October 28, 2019 # 28102019
Step 6 - Block 15A (Total insurable hours)
80.00 × 27 = 2160
Block 15A = 2160
Step 7 - Block 15B (Total insurable earnings)
$1,884.62 × 27 = $50,884.74
Block 15B = 50,884.74
Step 8 - Block 17A (Vacation pay)
$52,050.00 × 6% = $3,123.00
Block 17A = 3,123.00
Step 9 - Block 17C (Pay in lieu of notice)
Weekly earnings = $1,884.62 ÷ 2 = $942.31
Pay in lieu = $942.31 × 8 = $7,538.48
Block 17C (Pay in lieu of notice) = 7,538.48
Step 10 - Block 17C (Severance)
Severance = $942.31 × 10 = $9,423.10
Block 17C (Severance) = 9,423.10
NEW QUESTION # 16
......
In order to pass the exam and fight for a brighter future, these people who want to change themselves need to put their ingenuity and can do spirit to work. More importantly, it is necessary for these people to choose the convenient and helpful PF1 test questions as their study tool in the next time. Because their time is not enough to prepare for the exam, and a lot of people have difficulty in preparing for the exam, so many people who want to pass the PF1 exam and get the related certification in a short time have to pay more attention to the study materials. In addition, best practice indicates that people who have passed the PF1 Exam would not pass the exam without the help of the PF1 reference guide. So the study materials will be very important for all people. If you also want to pass the exam and get the related certification in a short, the good study materials are the best choice for you. Now we are going to make an introduction about the PF1 exam prep from our company for you.
New PF1 Braindumps Sheet: https://www.free4dump.com/PF1-braindumps-torrent.html
2026 Latest Free4Dump PF1 PDF Dumps and PF1 Exam Engine Free Share: https://drive.google.com/open?id=10EzCnySL9kcLgz4QSaD73TR1yGJCdsiM