2026 Latest Actual4Dumps Accounting-for-Decision-Makers PDF Dumps and Accounting-for-Decision-Makers Exam Engine Free Share: https://drive.google.com/open?id=1t6fnEL6_fas_roVpumzbGteKPpPEXV4j
We believe that every customer pays most attention to quality when he is shopping. Only high-quality goods can meet the needs of every customer better. And our Accounting-for-Decision-Makers study materials have such high quality, because its hit rate of test questions is extremely high. Perhaps you will find in the examination that a lot of questions you have seen many times in our Accounting-for-Decision-Makers Study Materials. In addition, the passing rate is the best test for quality of study materials. And we can be very proud to tell you that the passing rate of our Accounting-for-Decision-Makers study materials is almost 100 %.
| Section | Objectives |
|---|---|
| Topic 1: Managerial Accounting for Decision Making | - Cost-Volume-Profit Analysis
|
| Topic 2: Business Decision Support | - Performance Measurement
|
| Topic 3: Financial Accounting Fundamentals | - Financial Statements
|
>> Accounting-for-Decision-Makers Valid Torrent <<
Our WGU learning materials contain latest test questions, valid answers and professional explanations, which ensure you hold Accounting-for-Decision-Makers actual test with great confidence. And we will provide you with the most comprehensive service when you prepare Accounting-for-Decision-Makers Practice Exam with our valid dumps collection.
NEW QUESTION # 57
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.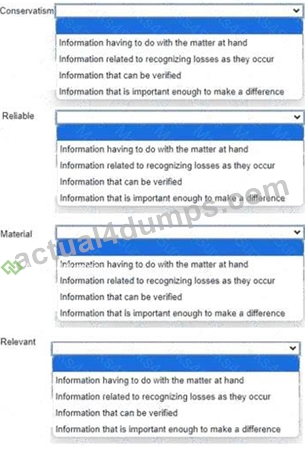
Answer:
Explanation: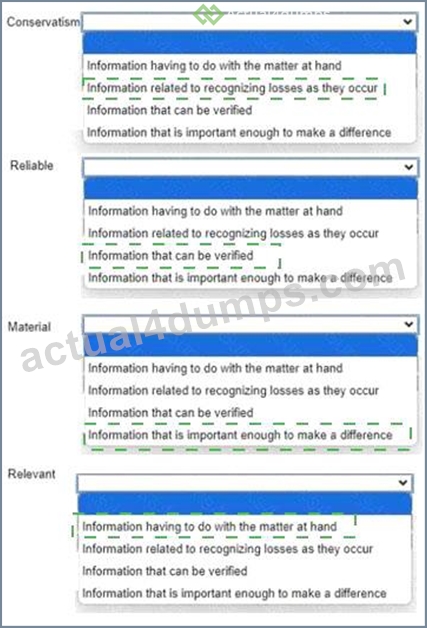
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
NEW QUESTION # 58
The following list provides partial financial information for a company.
Current assets = $36,543
Total assets = $58,719
Current liabilities = $24,824
Total liabilities = $48,561
Stockholders' equity = $10,158
Sales = $46,997
Net income = $3,761
Market value of equity = $41,316
What is the current ratio for this company?
Answer: B
Explanation:
The correct answer is C. 1.47 . The current ratio measures a company's ability to pay its short-term obligations using its short-term assets. The formula is:
Current ratio = Current assets / Current liabilities
Using the given figures:
Current ratio = 36,543 / 24,824 = 1.4721 , which rounds to 1.47
This means the company has $1.47 of current assets for every $1.00 of current liabilities . In financial analysis, this is generally viewed as a sign that the company has a reasonable short-term liquidity position, although the ideal ratio depends on the industry and the quality of the current assets. For example, cash and receivables are usually more liquid than inventory.
Option A is close, but it is not the correct rounded result. Option B is incorrect because it would indicate current liabilities exceed current assets. Option D is far too high based on the numbers given. Since the question asks specifically for the current ratio , the correct calculation and answer are clearly 1.47 , making Option C the right choice.
NEW QUESTION # 59
What is true regarding the use of International Financial Reporting Standards (IFRS)?
Answer: D
Explanation:
The correct answer is C. IFRS are commonly required to be used in Asia . IFRS is widely used around the world, and the IFRS Foundation states that companies in more than 140 jurisdictions are required to use IFRS Accounting Standards when reporting their financial health. That broad global adoption includes many Asian jurisdictions, so saying IFRS are commonly required in Asia is accurate.
Option A is incorrect because U.S. domestic issuers are generally required under SEC rules to file financial statements prepared in accordance with U.S. GAAP , not simply choose IFRS instead. Option B is false because IFRS are not seldom used by non-U.S. companies; in fact, they are extensively used internationally.
Option D is incorrect because the SEC does not require IFRS for all issuers; rather, SEC rules generally require U.S. GAAP for domestic registrants, while certain foreign private issuers may use IFRS as issued by the IASB. Therefore, among the listed choices, Option C is the only statement that is broadly correct and consistent with current international reporting practice.
NEW QUESTION # 60
What is an advantage of the indirect method of the cash flow statement?
Answer: A
Explanation:
The correct answer is B. Easy to reconcile between net income and cash flows . Under the indirect method
, the operating section of the statement of cash flows begins with net income and then adjusts for noncash items, gains and losses, and changes in working capital to arrive at net cash provided by operating activities
. This makes it especially useful for showing the relationship between accrual-based profit and actual operating cash flow. FASB guidance explains that the indirect method presents this reconciliation within the cash flow reporting process, and OpenStax likewise describes the indirect method as beginning with net income and reconciling it to cash flows.
Option A is incorrect because the direct method is often easier for beginners to read since it lists cash receipts and cash payments more directly. Option C is incorrect because the indirect method does not specifically prevent errors or reveal "indirect costs." Option D is incorrect because the purpose of the method is not to compare direct and indirect costs. Its main practical advantage is the clear reconciliation from net income to operating cash flow , so Option B is correct.
NEW QUESTION # 61
What can be determined when a firm performs an external audit of a company's financial statements?
Answer: A
Explanation:
The correct answer is B. Whether a company's financial statements fairly reflect its financial position .
The purpose of an external audit is for the independent auditor to express an opinion on whether the financial statements present fairly, in all material respects , the company's financial position, results of operations, and cash flows in conformity with the applicable financial reporting framework. PCAOB auditing standards state this explicitly in the required auditor's report language.
Option A is incorrect because anyone reading the income statement can see whether the company reported a profit or loss; that alone is not the purpose of the audit. Option C is incorrect because tax liability is not what the audit opinion is primarily determining. Option D is also incorrect because an audit does not certify that the statements were prepared by a particular kind of employee such as a trained bookkeeper. Instead, the audit evaluates whether the statements are fairly presented and free of material misstatement. Therefore, the best answer is that an external audit helps determine whether the company's financial statements fairly reflect its financial position .
NEW QUESTION # 62
......
Based on the credibility in this industry, our Accounting-for-Decision-Makers study braindumps have occupied a relatively larger market share and stable sources of customers. Such a startling figure --99% pass rate is not common in this field, but we have made it with our endless efforts. The system of Accounting-for-Decision-Makers test guide will keep track of your learning progress in the whole course. Therefore, you can have 100% confidence in our Accounting-for-Decision-Makers Exam Guide. According to our overall evaluation and research, seldom do we have cases that customers fail the Accounting-for-Decision-Makers exam after using our study materials. But to relieve your doubts about failure in the test, we guarantee you a full refund from our company by virtue of the related proof of your report card. Of course you can freely change another Accounting-for-Decision-Makers exam guide to prepare for the next exam.
Accounting-for-Decision-Makers Valid Dumps Pdf: https://www.actual4dumps.com/Accounting-for-Decision-Makers-study-material.html
2026 Latest Actual4Dumps Accounting-for-Decision-Makers PDF Dumps and Accounting-for-Decision-Makers Exam Engine Free Share: https://drive.google.com/open?id=1t6fnEL6_fas_roVpumzbGteKPpPEXV4j