The clients only need 20-30 hours to learn the AFP-Exam-1 exam questions and prepare for the test. Many people may complain that we have to prepare for the test but on the other side they have to spend most of their time on their most important things such as their jobs, learning and families. But if you buy our AFP-Exam-1 Study Guide you can both do your most important thing well and pass the AFP-Exam-1 test easily because the preparation for the test costs you little time and energy.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Client Relationship and Practice Management | 6% | - Practice Management - Client Discovery - Communication and Advisory Process |
| Topic 2: Investment Planning | 17% | - Asset Allocation - Investment Theory - Investment Products - Portfolio Construction |
| Topic 3: Asset and Liability Management | 11% | - Debt Management - Budgeting - Personal Balance Sheet Analysis - Cash Flow Management |
| Topic 4: Retirement Planning | 17% | - Registered Retirement Savings Plans - Retirement Needs Analysis - Retirement Income Strategies - Pension Plans |
| Topic 5: Professional Conduct and Regulatory Compliance | 10% | - Regulatory Requirements - Compliance Responsibilities - Ethics and Professional Standards |
| Topic 6: Risk Management and Insurance | 12% | - Life Insurance - Risk Assessment - Disability and Health Insurance - Risk Transfer Strategies |
| Topic 7: Tax Planning | 14% | - Tax-Efficient Strategies - Tax Deductions and Credits - Registered Plans - Income Tax Fundamentals |
| Topic 8: Estate Planning | 13% | - Trust and Beneficiary Planning - Estate Transfer Strategies - Wills - Powers of Attorney |
Our AFP-Exam-1 exam quiz is so popular not only for the high quality, but also for the high efficiency services provided which owns to the efforts of all our staffs. First of all, if you are not sure about the AFP-Exam-1 exam, the online service will find the most accurate and all-sided information for you, so that you can know what is going on about all about the exam and make your decision to buy AFP-Exam-1 Study Guide or not.
NEW QUESTION # 107
John and Jerry's financial planner have recommended they review their budget. What is the primary purpose of the budget?
Answer: A
Explanation:
A budget is primarily a cash-flow planning tool. It identifies the client's expected inflows and outflows over a defined period and shows whether spending, debt servicing, taxes, insurance premiums, and savings are sustainable. Expense reduction and savings-plan design may result from the budget review, but they are not the primary purpose of the budget itself. Total debt service is a borrowing-capacity ratio, not the purpose of a household budget. A budget also helps compare planned spending with actual results, isolate discretionary expenses, and create accountability for future behaviour. In AFP practice, the planner uses the budget as the bridge between goals and implementation: retirement savings, debt repayment, emergency funding, insurance affordability, and investment contributions all depend on cash-flow capacity. Therefore, option A is the most precise answer. Study Guide focus: budgeting, cash-flow analysis, spending management, debt capacity, and savings discipline. Without this baseline, later advice on borrowing, savings, or insurance premiums becomes speculative and weakly supported.
NEW QUESTION # 108
A retiree receives income-tested benefits and needs occasional withdrawals for vacations and home repairs.
Which account is generally most efficient for withdrawals that do not increase taxable income?
Answer: B
Explanation:
TFSA withdrawals are generally tax-free and do not increase net income for tax purposes. That feature makes the TFSA valuable in retirement when the client receives income-tested benefits or wants spending flexibility without triggering additional taxable income. RRSP and RRIF withdrawals are taxable and can affect benefit calculations, credits, or clawbacks depending on the client's income level. A non-registered interest-bearing GIC produces taxable interest each year, even if the client does not withdraw the interest for spending. Option C is therefore the best match to the stated objective. The planner should still coordinate the TFSA with minimum RRIF withdrawals, pension income, emergency reserves, and estate designations. The planning principle is withdrawal sequencing: the best account for a specific withdrawal depends on tax treatment, benefit impact, liquidity, and long-term sustainability. For irregular discretionary spending, TFSA withdrawals often provide the cleanest after-tax cash flow. References/topics: TFSA withdrawals, retirement cash flow, income-tested benefits, withdrawal sequencing.
NEW QUESTION # 109
Tom has two children from a previous marriage. He has been paying $1,000 per month for spousal support and $1,500 per month for child support to his ex-wife. Recently, his ex-wife was awarded increased child support payments from Tom to cover unanticipated university expenses for one of the children. What should Tom's financial planner advise him about how this increased monthly payment may impact his finances?
Answer: D
Explanation:
The increased child support payment reduces Tom's net cash flow by the full amount. Under the standard tax treatment, child support is not deductible to the payer and is not taxable to the recipient. That differs from qualifying periodic spousal support, which may be deductible to the payer and taxable to the recipient when the legal requirements are met. Because the increased amount relates to child support for university expenses, Tom receives no tax deduction and no offsetting tax credit merely because he pays more. The tuition tax credit belongs to the eligible student unless transferred under applicable rules; it is not automatically applied to Tom because he pays support. The planner should update Tom's cash-flow plan, debt ratios, retirement savings ability, and emergency reserve using the full increased payment. Study Guide focus: child support, spousal support, tax deductibility, cash-flow planning, and separation agreements. This distinction is essential when modelling separation settlements because gross payments and after-tax cost can differ sharply.
NEW QUESTION # 110
Janet's non-registered account holds the funds listed in the following table: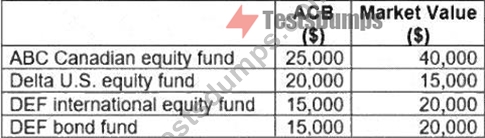
Assuming a marginal tax rate of 45%, what amount of tax payable will Janet incur if she redeems the account to fund the purchase of a new business?
Answer: C
Explanation:
Janet's taxable result comes from the net realized capital gain, not from the total market value redeemed. The ABC Canadian equity fund has a $15,000 gain, the Delta U.S. equity fund has a $5,000 loss, the DEF international equity fund has a $5,000 gain, and the DEF bond fund has a $5,000 gain. Net capital gains are therefore $20,000 after offsetting the Delta loss. Only one-half of the net capital gain is taxable under the standard capital gains inclusion treatment used in AFP-level calculations, producing a $10,000 taxable capital gain. At a 45% marginal tax rate, the tax payable is $4,500. Option A taxes the full net gain; option C and option D reflect incorrect inclusion or arithmetic assumptions. The purpose of the question is to test disposition analysis in a non-registered account and the sequence of gain/loss netting before applying the marginal rate. Study Guide focus: adjusted cost base, fair market value, capital gains inclusion, and non- registered tax planning.
NEW QUESTION # 111
Jenny and Herman are looking for tax strategies that will help them better manage their marginal annual tax rates. Jenny is currently the primary income earner in the household. She has a large non-registered portfolio that holds only plain vanilla S & P 500 index funds. Jenny and Herman have a 14-year-old daughter, and they would also like to know what income-splitting opportunities exist. They've presented several ideas to their tax planner, Isaac, for review. Which of the following will likely result in tax attribution to Jenny?
Answer: D
Explanation:
Jenny's gift to her minor daughter is the transaction most likely to trigger attribution back to Jenny. When a high-income parent transfers income-producing property to a minor child, income such as interest and dividends generally attributes back to the parent. The rule prevents simple income splitting by gift. A spousal RRSP converted to a RRIF can avoid attribution on required minimum RRIF withdrawals, subject to detailed timing rules. A sale of securities to Herman at fair market value can avoid attribution if proper consideration is paid and the transaction is documented. A prescribed-rate loan to Herman can also avoid attribution if interest is charged at the prescribed rate and paid by the required deadline. The key AFP issue is distinguishing prohibited income splitting from properly structured transfers or loans. The minor-child gift in option A is the clearly attributive arrangement. Study Guide focus: attribution rules, minor children, spousal transfers, prescribed-rate loans, and family tax planning.
NEW QUESTION # 112
......
We pursue the best in the field of AFP-Exam-1 exam dumps. AFP-Exam-1 dumps and answers from our TestsDumps site are all created by the IT talents with more than 10-year experience in IT certification. TestsDumps will guarantee that you will get AFP-Exam-1 Certification certificate easier than others.
Latest AFP-Exam-1 Exam Format: https://www.testsdumps.com/AFP-Exam-1_real-exam-dumps.html