As candidates, the quality must be your first consideration when buying ClaimCenter-Business-Analysts learning materials. We have a professional team to collect the first-hand information for the exam. Our company have reliable channel for collecting ClaimCenter-Business-Analysts learning materials. We can ensure you that ClaimCenter-Business-Analysts exam materials you receiveare the latest version. We have strict requirements for the ClaimCenter-Business-Analysts Questions and answers, and the correctness of the answers can be guaranteed. In order to serve our customers better, we offer free update for you, so that you can get the latest version timely.
| Certification Vendor: | Guidewire |
|---|---|
| Exam Name: | ClaimCenter Business Analyst - Mammoth Proctored Exam |
| Exam Number: | ClaimCenter-Business-Analysts |
| Related Certifications: | Guidewire Certified Professional |
| Passing Score: | 70% |
| Exam Price: | USD 250 |
| Exam Format: | Single Choice, Multiple Choice |
| Exam Duration: | 120 minutes |
| Real Exam Qty: | 50 |
| Certificate Validity Period: | 3 years |
| Available Languages: | English |
| Sample Questions: | Guidewire ClaimCenter-Business-Analysts Sample Questions |
| Exam Way: | Proctored |
| Pre Condition: | Candidates are recommended to complete Guidewire ClaimCenter training courses and have hands-on experience with ClaimCenter configuration and business analysis. |
| Official Syllabus URL: | https://education.guidewire.com |
>> Valid ClaimCenter-Business-Analysts Exam Syllabus <<
ClaimCenter-Business-Analysts materials trends are not always easy to forecast, but they have predictable pattern for them by ten-year experience who often accurately predict points of knowledge occurring in next ClaimCenter-Business-Analysts preparation materials. Our professional experts can give you the latest and the most accurate ClaimCenter-Business-Analysts Training Material for that they have beening in this filed for so many years and know every aspect of the change of ClaimCenter-Business-Analysts practice questions. You can trust in our ClaimCenter-Business-Analysts learning braindump for sure.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
NEW QUESTION # 16
Losses incurred because of an accident with other vehicles can be very large. Because of the risk of large losses, all claims must include both a police report and the details of any passengers in the vehicle, whether they sustained injuries or not. The claim must show whether there were passengers in the vehicle at the time of the accident. Succeed wants the ability to include a very detailed description of the loss event information on intake of the claim.
When the claim is created, Succeed wants to flag the claim with a reminder for the Adjuster to contact the insured.
There should be reminders for the Adjuster to complete the following items for every new claim created:
. Review any photographs of the accident
. Contact and Interview each passenger
. Collect statements from each witness
. Record the vehicle's mileage
Which business requirement is based on assumptions?
Answer: B
Explanation:
In the context of business requirements analysis, an assumption is a statement that is accepted as true or certain to happen without proof.
* Why A is the correct answer:The requirement to generate a reminder to "review any photographs" for everynew claim assumes that photographs will be available for every accident. In reality, photos are not always taken or provided at the First Notice of Loss (FNOL). Creating a mandatory task for an optional piece of evidence is based on the assumption of data availability.
* Why D is incorrect:"All claims must include a police report..." is aBusiness Ruleor constraint. It is a mandatory condition imposed by the business ("must include") rather than an assumption about what is currently present.
* Why B is incorrect:Contacting the insured is a standard, universal step in the claims process that applies to every claim, so it is not considered an assumption.
NEW QUESTION # 17
A car accident in a rural area of Durango, Colorado is reported to Succeed Insurance. The driver of the damaged car reportedly hit the base of a windmill tower while driving at night. There was no other passenger in the car when the accident happened, and the driver has a valid auto policy on file.
While the driver is not physically injured, the entire passenger side of the car has been severely damaged.
Although the windmill is still functioning, the base of the tower has sustained multiple broken parts.
Which two incidents need to be created for the claim based on the reported accident? (Choose two.)
Answer: A,D
Explanation:
In Guidewire ClaimCenter, an Incident is the data object used to capture the specific facts about "what" was damaged or affected during the loss event. It serves as the foundation for creating Exposures (the financial liabilities).
* Vehicle Incident (Option C):The scenario states that the insured's car has been "severely damaged" on the passenger side. To record these facts-including the point of impact, the severity, and the vehicle description-the Adjuster must create aVehicle Incident. This incident will eventually support the collision coverage exposure.
* Property Incident (Option B):The accident involved the car hitting a "windmill tower," resulting in
"broken parts" to the base. In ClaimCenter, damage to third-party non-vehicular objects (like fences, poles, buildings, or towers) is captured using aFixed Property Incident(often referred to generically as a Property Incident). This incident records the damage description and ownership of the windmill, which is necessary to handle the Property Damage Liability claim.
Why other options are incorrect:
* Option E (Injury):The scenario explicitly states the driver is "not physically injured." Therefore, an Injury Incident is not required.
* Option A ("Another structure"):The standard object for third-party fixed property damage is the Property Incident/Fixed Property Incident, not "Another structure."
* Option D (Loss of Use):While possible later, the primary immediate damage is physical. Loss of Use is usually a secondary exposure type, not the primary incident definition for the tower itself.
NEW QUESTION # 18
What is a reason to assign a unique identification number to each User Story Card in ClaimCenter implementation projects?
Answer: B
Explanation:
In Guidewire implementation methodology (such as SurePath), traceability and organization are maintained through strict naming conventions.
* Naming Convention (Option C):A unique identification number is assigned to every User Story Card to create a consistent naming structure:Product - Theme - Subtheme - ID. (For example: CC - FNOL - Vehicle - 001).
* Purpose:This convention allows Business Analysts, Developers, and QA testers to easily reference, search, and trace requirements across different tools (e.g., from the Story Card in Excel/Jira to the code in Studio and the test cases in the testing suite).
* Why not A, B, or D?Time estimation (A) uses "Story Points," not the ID. Burndown charts (B) track velocity/points, not criteria IDs. Backlogs (D) are organized byBusiness Value/Priority, not just numerically by ID.
NEW QUESTION # 19
A Business Analyst (BA) has identified a new typecode essential for Succeed Insurance implementation.
During adjudication, Adjusters need to be able to update the loss cause value to reflect the new typecode.
Which tabs in a Guidewire Story Card should be used to document the business requirement?
Answer: C
Explanation:
To fully document a requirement that involves both a User Interface change (updating a value on a screen) and a Data Model change (adding a new typecode), the standard Guidewire Story Card tabs required are:
* Document Control:Captures the metadata (Author, Version, Owner) to track the requirement's history.
* UI Mockup:visually illustrateswhereon the screen the "Loss Cause" field is located and how the dropdown should appear to the Adjuster.
* UI Fields:Defines the specific behavior of the field (e.g., Is it mandatory? Is it editable during adjudication? What is the label?).
* Typelist:This is critical for this specific scenario. It lists the actual Code, Name, and Description of the new typecodebeing added to the "Loss Cause" typelist.
* Business Acceptance:Defines the testable criteria (Acceptance Criteria) to verify that the adjuster can successfully select the new value and save the claim.
Why Option B is correct:It is the only option that includesboththe visual requirements (Mockup/Fields) and the data requirement (Typelist) alongside the standard control and testing tabs (Document Control/Business Acceptance).
NEW QUESTION # 20
Whenever the Total Loss Calculator determines that a vehicle is a total loss, Succeed Insurance wants to create a custom history event with the exposure name and total loss score.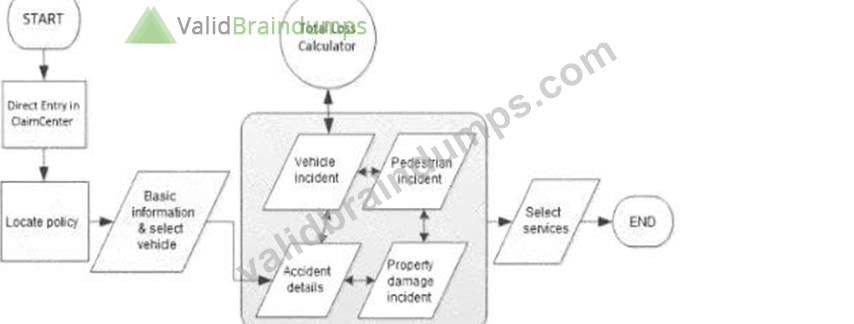
Which step in the claim setup process flow must be completed before the history event can be created?
Answer: B
Explanation:
250 to 350 words From Exact Extract of Guidewire ClaimCenter Business Analyst documentation:
In Guidewire ClaimCenter workflow analysis and configuration, defining the correct sequence of operations is critically dependent on Data Availability and Data Dependency.
The specific requirement here dictates that the custom history event must capture theTotal Loss Score. In the context of the ClaimCenter object model and process flow, the Total Loss Score is anoutputvalue generated specifically by theTotal Loss Calculatorengine. Before this calculator runs, the score attribute is effectively null or non-existent.
Therefore, to satisfy the business requirement, the step that writes the history event must be placedafterthe step that generates the data it needs to record.
* Process Logic:If the Business Analyst were to place the history event creation stepbeforethe Total Loss Calculator (Option B) orbeforethe Vehicle Incident (Option D), the system would attempt to write a record containing a score that has not yet been calculated. This would result in either a system error or a history event with a blank/zero value, failing to meet the business requirement.
* Dependency Chain:The workflow dependency is: Vehicle Data Entry -> Total Loss Calculation -> Score Generation -> History Event Creation.
* Implementation Note:In a typical Guidewire implementation, this logic is often handled via "Event Fired" rules or specific "Exit Points" in the workflow. The system waits for the confirmation that the Total Loss calculation service has successfully returned a result. Once that transaction is committed and the score is persisted on the Vehicle or Exposure entity, the subsequent rule to generate the History Event can trigger successfully.
Consequently,Option Cis the only viable placement in the process flow. It ensures that the prerequisite action (calculation) is complete and the required data payload (the score) is available for the subsequent action (logging the history event).
NEW QUESTION # 21
......
Valid ClaimCenter-Business-Analysts Exam Question: https://www.validbraindumps.com/ClaimCenter-Business-Analysts-exam-prep.html