With ExamDiscuss's CSI AFP-Exam-1 Exam Training materials you can pass the CSI AFP-Exam-1 exam easily. The training tools which designed by our website can help you pass the exam the first time. You only need to download the ExamDiscuss CSI AFP-Exam-1 exam training materials, namely questions and answers, the exam will become very easy. ExamDiscuss guarantee that you will be able to pass the exam. If you are still hesitant, download our sample of material, then you can know the effect. Do not hesitate, add the exam material to your shopping cart quickly. If you miss it you will regret for a lifetime.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Enabling Competencies | 16% | - Professional Conduct and Regulatory Compliance - Client Relationship and Practice Management |
| Topic 2: Technical Competencies | 84% | - Tax Planning - Asset and Liability Management - Retirement Planning - Estate Planning - Risk Management and Insurance - Investment Planning |
>> CSI AFP-Exam-1 Exam Score <<
We have been developing our AFP-Exam-1 practice engine for many years. We have no doubt about our quality of the AFP-Exam-1 exam braindumps. Our experience is definitely what you need. And especially our professional experts have been devoting in this field for over ten years. I believe no one can know the AFP-Exam-1 training guide than them. To combine many factors, AFP-Exam-1 real exam must be your best choice.
NEW QUESTION # 52
A married couple has a $480,000 mortgage with 15 years remaining. They want the mortgage retired if either spouse dies during that period. What insurance structure best fits this objective?
Answer: B
Explanation:
The risk event is the first death, because the surviving spouse would immediately face the mortgage obligation with reduced household capacity. A joint first-to-die term policy pays when the first insured spouse dies, and a 15-year term aligns the coverage period with the remaining mortgage horizon. Option A pays only after both spouses have died, which is too late to protect the survivor. Option C has the same timing problem and adds permanent-insurance cost for a temporary mortgage need. Option D is unrelated; annuities provide income, not death-benefit protection for a mortgage. The planner should also consider whether separate term policies would offer more flexibility, whether the coverage amount should be level or decreasing, and whether the policy should be personally owned rather than lender-owned creditor insurance. The central course principle is matching insurance type, term, amount, and ownership to the specific risk being transferred.
References/topics: first-to-die insurance, term life, mortgage liability, survivor protection.
NEW QUESTION # 53
Suzy, age 45, is meeting with a financial planner as she has recently inherited $1.25 million from her late aunt. Suzy has poor spending habits and would like to review options that would safeguard and help her receive stable cash flows. She does not have a lot of experience investing and would like to avoid making day- to-day investment decisions. Which type of investment account is most appropriate for Suzy?
Answer: B
Explanation:
Suzy's facts point to income certainty and behavioural protection. She has inherited significant capital, admits poor spending habits, wants stable cash flow, lacks investment experience, and does not want day-to-day investment decisions. A straight life annuity converts a lump sum into predictable income for life, reducing the risk that she spends the inheritance too quickly or makes unsuitable investment decisions. A separately managed, multi-mandate managed, or discretionary fee-based account may delegate investment decisions, but those structures still expose her to market fluctuation and do not automatically impose a stable lifetime income discipline. The trade-off is that a straight life annuity may provide limited estate value and little liquidity after purchase, so the planner should consider whether only part of the inheritance should be annuitized. Among the options, however, the annuity best matches the stated need. Study Guide focus:
annuities, behavioural risk, retirement income products, capital preservation, and cash-flow certainty. The planner should reserve liquid capital separately if Suzy needs emergency funds or future discretionary purchases.
NEW QUESTION # 54
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: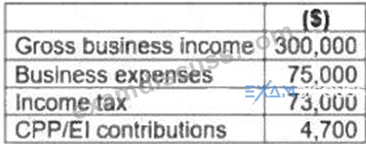
What is Terry's net business income?
Answer: C
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 55
Ram Patel, age 65, is meeting with his financial planner, Maria Romano, to complete a financial plan. Ram is retiring this year, and his company provides a defined benefit pension plan. Upon retirement, he has the choice of receiving $20,000 each year for 20 years or until death (whichever is earlier), or he can take
$304,300, which is the commuted value at retirement. Ram has confirmed that he will be transferring the commuted value to a LIRA. After further discovery, Maria suggests that they utilize a 5% market rate of return and project the funds to last 25 years. What should Maria update Ram's projected annual retirement income to?
Answer: C
Explanation:
Maria should update Ram's projected retirement income to approximately $21,591. The commuted value is
$304,300, and Ram will transfer it to a LIRA. Using a 5% annual market return over a 25-year payout period, the annuity-style payment calculation is based on amortizing the capital over the projection period. The annual payment is calculated as present value multiplied by the discount rate factor: $304,300 × 0.05 divided by 1 minus 1.05 to the negative 25. The result is approximately $21,591 per year. Option B is simply the original pension option and ignores the commuted-value projection. Option D is a rough estimate, and option A overstates the sustainable annual amount. AFP retirement analysis requires consistent assumptions for rate of return, payout period, and income timing before comparing pension alternatives. Study Guide focus:
pension commuted values, LIRA transfers, retirement income projections, present value, and annuity calculations. The comparison should also recognize that a projected LIRA withdrawal stream is not the same guarantee as a pension promise.
NEW QUESTION # 56
Ivan relocates for a new job and wants to know whether his move may qualify for the work-related moving expense deduction. What minimum distance test is generally relevant?
Answer: C
Explanation:
The standard Canadian moving-expense test requires the new residence to be at least 40 kilometres closer to the new work or business location than the old residence was. Option D states the relevant threshold. Options A, B, and C understate the distance requirement. In a planning context, the distance test is only the starting point. The planner should also consider whether the move relates to eligible employment or business income, whether expenses are reasonable and properly documented, whether reimbursement was received from an employer, and whether expenses are deductible only against income from the new work location. The deduction can matter when clients change jobs, relocate for self-employment, or move for post-secondary attendance in specific circumstances. The key exam distinction is that the rule is not based on the total distance moved; it compares how much closer the new home is to the new workplace. References/topics:
moving expenses, employment relocation, tax deductions, distance test.
NEW QUESTION # 57
......
The pass rate is 98.65%, and we can ensure you pass the exam if you choose AFP-Exam-1 training materials from us. In addition, we have professional experts to compile and verify AFP-Exam-1 questions and answers, therefore you can just use them at ease. We also pass guarantee and money back guarantee if you fail to pass the exam. Free update for AFP-Exam-1 Training Materials is available, namely, in the following year, you don’t need to spend a cent, but you can get the latest information of the exam. And the latest version for AFP-Exam-1 exam briandumps will send to your email automatically.
AFP-Exam-1 Valid Vce: https://www.examdiscuss.com/CSI/exam/AFP-Exam-1/