P.S. Free & New PF1 dumps are available on Google Drive shared by PracticeVCE: https://drive.google.com/open?id=120nLndmnTQsE_05Il6lCBczZkDHgd9Zh
Individuals who pass the Payroll Fundamentals 1Exam certification exam demonstrate to their employers and clients that they have the knowledge and skills necessary to succeed in the industry. PracticeVCE is aware that preparing with outdated PF1 Study Material results in a loss of time and money.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Record of Employment (ROE) | 20% | - Submission and deadlines
|
| Topic 2: Termination and Special Payments | 30% | - Leaves and absences
|
| Topic 3: Communication and Compliance | 10% | - Accuracy and documentation
|
| Topic 4: Individual Pay Calculations | 40% | - Regular earnings
|
No doubt the National Payroll Institute PF1 certification is a valuable credential that helps you to put your career on the right track and assist you to achieve your professional career goals. To achieve this goal you need to pass the Payroll Fundamentals 1Exam (PF1) exam. To pass the Payroll Fundamentals 1Exam (PF1) exam you need to start this journey with valid, updated, and real National Payroll Institute PF1 PDF QUESTIONS. The PracticeVCE PF1 exam practice test questions are essential study material for quick National Payroll Institute PF1 exam preparation.
NEW QUESTION # 11
The source deductions form completed by all new employees in Quebec is called:
Answer: A
Explanation:
In Quebec, employees must complete a Quebec-specific source deductions form so the employer can calculate Quebec income tax to withhold. Revenu Quebec identifies Form TP-1015.3-V (Source Deductions Return) as the form employees complete and provide to their employer/payer for this purpose. It is part of the onboarding
/payroll setup process in Quebec and is used to determine personal tax credits and any additional withholding instructions for Quebec provincial income tax.
The other options are not the standard Quebec source deductions return for new employees: T1213 is a CRA form used to request a reduction in tax deductions at source (federal), TD1-AB is a provincial TD1 for Alberta (not Quebec), and T2222 is not the Quebec source deductions return. From a payroll communication standpoint, the employer should request both the applicable federal TD1 and the Quebec TP-1015.3-V, then retain them on file to support accurate withholding calculations.
NEW QUESTION # 12
Phan was employed fromMarch 1, 1992throughJanuary 10, 2007. He was not a member of the organization' s pension plan. Calculate the number of years eligible for the$1,500.00portion of a retiring allowance.
Answer: B
Explanation:
The special$1,500transfer eligibility connected to retiring allowances is based specifically onyears (or part- years) of service before 1989where the employee hadno vested employer pension/DPSP benefitsfor those years. CRA explains that, in addition to the $2,000-per-year pre-1996 rule, you can also transfer an additional
$1,500 for each year or part-year before 1989that meets the vesting condition.
Phan's employment began in1992, which isafter 1989. Because he haszeroservice before 1989, there areno years that can qualify for the $1,500 portion-regardless of whether he belonged to a pension plan.
Therefore, the number of eligible years for the$1,500component is0(option A). Payroll must base this calculation on actual service dates, including any related-employer service if applicable, but here the start date alone makes the $1,500 portion ineligible.
NEW QUESTION # 13
Select the correct order of priority for withholding payroll deductions from an employee's earnings.
Answer: D
Explanation:
Payroll deductions are typically applied in a priority order to ensure the employer meets mandatory legal obligations first and avoids creating liability. Standard Canadian payroll training materials commonly present five categories withheld in this order: (1) statutory deductions, (2) legal deductions, (3) union deductions, (4) company-compulsory deductions, and (5) voluntary deductions.
Statutory deductions (CPP/QPP, EI, income tax, and where applicable NWT/Nunavut payroll tax) have top priority because employers are legally required to deduct and remit them.
Legal deductions (such as CRA requirements to pay/garnishments) are next because they are enforced by law and can create employer liability if not followed.
Union deductions follow where required by a collective agreement.
Company-compulsory deductions (for example, required benefit premiums) come after those.
Voluntary deductions (charity, savings plans, etc.) are last and only taken if funds remain.
Therefore, option D is the correct order.
NEW QUESTION # 14
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)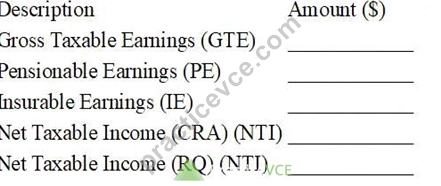
STATUTORY DEDUCTIONS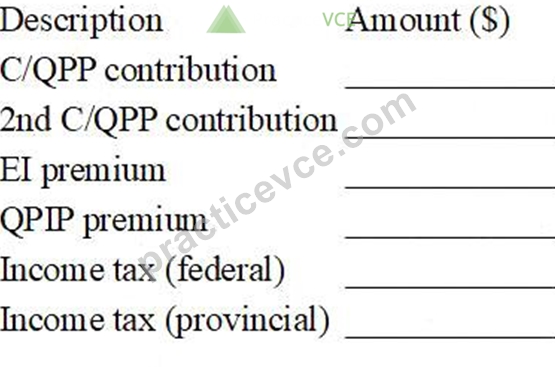
OTHER DEDUCTIONS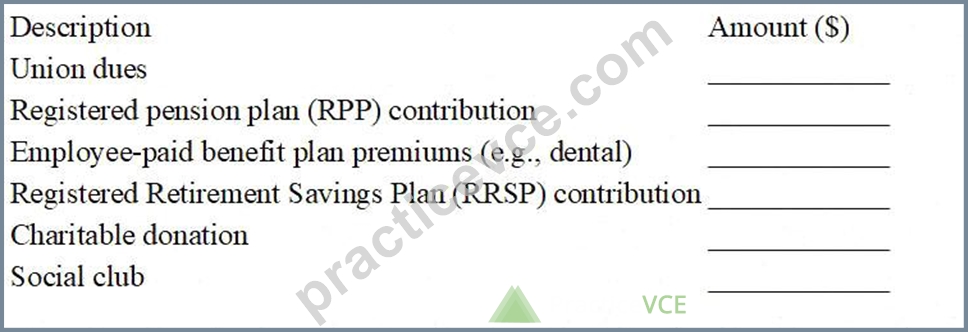
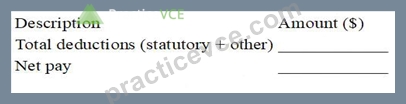
Given Data (Reference)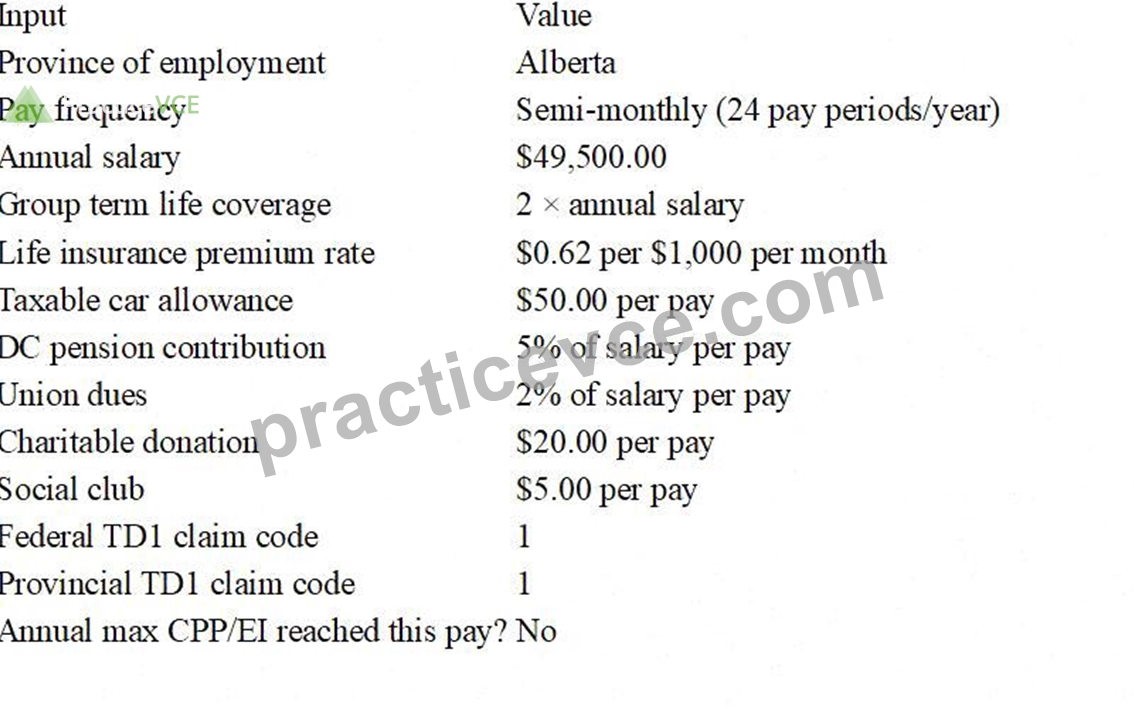
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 15
Which pension plan requires the services of an actuary to study and forecast future needs of the plan to ensure the plan remains sufficiently funded to provide employees with their retirement benefits?
Answer: A
Explanation:
A defined benefit (DB) pension plan promises a future pension benefit based on a formula (for example, service and earnings). Because the benefit is defined, the plan must ensure it is adequately funded to meet future liabilities. That requires actuarial valuations-professional studies that forecast future obligations and determine required contributions. Regulators describe DB plan funding as being based on actuarial calculations and require administrators to file actuarial valuation reports to establish funding and contribution requirements.
A defined contribution (DC) plan does not promise a specific future pension amount; contributions are defined, and the retirement outcome depends on investment performance-so it does not require the same ongoing actuarial funding valuations for promised liabilities. An RRSP is an individual savings plan, not an employer DB plan requiring actuarial funding reports.
Therefore, the correct answer is Defined benefit pension plan (option A).
NEW QUESTION # 16
......
Both practice exams (web-based & desktop) give a National Payroll Institute PF1 real exam feeling and identify your mistakes so you can overcome your weaknesses before the PF1 final test. The desktop National Payroll Institute PF1 Practice Test software works on Windows after software installation. You can take the web-based Payroll Fundamentals 1Exam PF1 practice exam via any operating system.
Exam PF1 Tutorials: https://www.practicevce.com/National-Payroll-Institute/PF1-practice-exam-dumps.html
DOWNLOAD the newest PracticeVCE PF1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=120nLndmnTQsE_05Il6lCBczZkDHgd9Zh