참고: PassTIP에서 Google Drive로 공유하는 무료, 최신 LLQP 시험 문제집이 있습니다: https://drive.google.com/open?id=1a4MHFaa9rSDCQrpz_-3G1dtNyO__V9gi
지금 사회에 능력자들은 아주 많습니다.it인재들도 더욱더 많아지고 있습니다.많은 it인사들은 모두 관연 it인증시험에 참가하여 자격증취득을 합니다.자기만의 자리를 확실히 지키고 더 높은 자리에 오르자면 필요한 스펙이니까요.LLQP시험은IFSE Institute인증의 중요한 시험이고 또 많은 it인사들은IFSE Institute자격증을 취득하려고 노력하고 있습니다.
| 주제 | 소개 |
|---|---|
| 주제 1 |
|
| 주제 2 |
|
| 주제 3 |
|
| 주제 4 |
|
PassTIP는 IT인증시험 자격증 공부자료를 제공해드리는 전문적인 사이트입니다. PassTIP제품은 100%통과율을 자랑하고 있습니다. IFSE Institute인증 LLQP시험이 어려워 자격증 취득을 망설이는 분들이 많습니다. PassTIP가 있으면 이런 걱정은 하지 않으셔도 됩니다. PassTIP의IFSE Institute인증 LLQP덤프로 시험을 한방에 통과하여 승진이나 연봉인상에 도움되는 자격증을 취득합시다.
질문 # 245
Constantin is a 47-year-old marketing manager earning an annual salary of $175,000, who, together with his husband, recently purchased a house. A few years ago, Constantin was terminated from his previous position, and it took him two years to find similar employment in his field. The prolonged lack of income caused him to accumulate substantial debt. Today, after several years of sensible budgeting, the only debt remaining is his mortgage. He purchased disability and life insurance on the mortgage at the bank.
Given this information, what is Constantin's greatest financial risk?
정답:D
설명:
Constantin's primary financial risk remains theloss of income, as his substantial mortgage and recent history of debt accumulation due to a prolonged period of unemployment suggest a potential vulnerability if he were to lose his income again. Despite his current stable income, any future job loss would significantly impact his ability to meet his financial obligations, including mortgage payments, which could lead to another round of financial strain. The LLQP materials highlight that maintaining a stable income is crucial, particularly for individuals with high financial responsibilities, such as a mortgage. Although other risks like unexpected expenses, debt, and a lower standard of living are relevant, the direct consequence of losing his income would exacerbate these risks, making income loss the most critical concern.
질문 # 246
Harper owns a disability insurance policy that will pay her a monthly benefit if she becomes unable to work.
At the time she applied for the policy, Harper was a new graduate with an annual income of $60,000, and she qualified for a monthly benefit of $3,000. Instead of taking the maximum benefit, she focused on paying off her student loans and keeping her insurance premiums low. She elected to purchase a monthly benefit of
$2,500 and add the future purchase option (FPO) rider for up to $500 a month of additional coverage. Now she is further along in her career, Harper earns $100,000 a year, and she meets with her insurance agent Trish to increase her coverage. Harper would like her new monthly benefit to be $5,000.
Which of the following statements about Harper's coverage is TRUE?
정답:D
설명:
Harper has aFuture Purchase Option (FPO)rider on her disability insurance policy, which allows her to increase her coverage by a predetermined amount (in this case, $500) without undergoing additional medical underwriting, provided she exercises this option at specific intervals. Given her increased income, Harper wishes to increase her monthly benefit to $5,000. By exercising the FPO, she can automatically add $500 to her current benefit, raising it from $2,500 to $3,000 without medical underwriting. To reach her desired benefit of $5,000, she would need an additional $2,000. For this portion, she would need to go through medical underwriting as it exceeds the FPO amount. Thus, option D is correct, as it accurately reflects the process and options available to Harper under the LLQP guidelines for utilizing the FPO rider along with additional underwriting for further increases.
질문 # 247
Lily is an experienced realtor. She has been in the business for over 40 years and has made good money throughout her career. She now feels ready to retire and will do so in five months. Most of her assets are in real estate properties. Even within her RRSP and TFSA accounts, she only owns segregated real estate funds.
As Lily is not entitled to any pension, she will heavily rely on her RRSP and TFSA accounts as sources of income. These accounts are now worth $850,000 and $130,000 respectively. Once retired, Lily might also make larger withdrawals from time to time to travel abroad.
Which one of the following risks will Lily be most exposed to after she retires?
정답:C
설명:
According to the LLQP Segregated Funds and Annuities and Investment & Savings curriculum, identifying a retiree's primary risk requires analyzing asset concentration, income needs, and access to cash. Lily's situation clearly points to liquidity risk as her most significant exposure after retirement.
Liquidity risk is defined in the LLQP study materials as the risk that an investor may not be able to access cash quickly or without a significant loss in value when funds are needed. Lily's wealth is heavily concentrated in real estate, both directly through properties and indirectly through segregated real estate funds held in her RRSP and TFSA. Real estate is inherently an illiquid asset class. Selling property or redeeming real estate-focused funds can take time and may occur at unfavourable prices, especially during market downturns.
This risk is amplified by the fact that Lily has no pension income. Unlike retirees with guaranteed income streams, Lily must rely almost entirely on withdrawals from her registered and non-registered investment assets to meet her living expenses. The LLQP curriculum emphasizes that retirees who depend on their portfolios for income must prioritize liquidity to ensure regular cash flow and financial flexibility.
Additionally, Lily plans to make larger, irregular withdrawals to travel abroad. This further increases her exposure to liquidity risk, as sudden cash needs may force her to redeem investments when market conditions are poor or when real estate values are temporarily depressed.
The other answer choices are less applicable. Credit risk primarily affects bondholders and lenders, which is not central to Lily's portfolio. Inflation risk is relevant to all retirees, but Lily's assets include real assets like real estate, which tend to provide some inflation protection. Interest rate risk mainly affects fixed-income investments, which are not a major component of her holdings.
Therefore, based on LLQP-approved risk definitions and retiree planning principles, Lily is most exposed to liquidity risk, making Option C the correct and fully verified answer.
질문 # 248
Oliver, an insurance agent, meets with Roman and Julie. They are a married couple with a five-year-old son William. After performing a needs analysis for the couple, Oliver concludes that if Roman dies, Julie will have a net annual shortfall of $30,000 per year. Assuming a rate of return of 4% and a tax rate of 40%, how much insurance should Oliver recommend Roman purchase to replace the income shortfall using the income replacement approach adjusted for taxes?
정답:B
설명:
To determine the amount of insurance needed for income replacement with a net shortfall of $30,000 per year, the calculation is as follows:
* Calculate Gross Income Needed:Since Roman's income needs to be adjusted for a 40% tax rate:
A black and white math equation Description automatically generated with medium confidence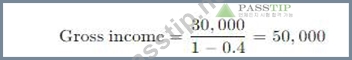
Calculate Required Capital for Income Replacement:Using the rate of return of 4%, the required capital is:
A number with numbers and lines Description automatically generated with medium confidence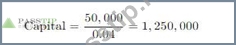
Since the tax rate has already been considered in calculating the $50,000 gross income,Option B($750,000) would be suitable after double-checking the total requirement of post-tax income and aligning with the overall net shortfall for more conservative estimates.Correct answer after full calculation adjustments should beB.
$750,000.
질문 # 249
Nelson is turning 46 and wants to explore additional tax planning opportunity. He is an avid investor and has invested into a lot of mutual funds and stocks. His RRSP is currently maxed out. He is meeting with Andrew, his financial advisor with life insurance license, to discuss on his financial future and some life insurance policy options. As a risk taker, Nelson would like tohave a plan that would allow him to supplement his retirement income when he reaches 70. However, his employment income is very high and his marginal tax rate will remain at the top bracket even after his retirement.
What recommendation should Andrew make in order to fit Nelson's need?
정답:D
설명:
Comprehensive and Detailed Explanation From Exact Extract:
For high-income individuals like Nelson, acollateral loan strategyusing aUniversal Life (UL)policy allows for tax-free access to accumulated values without triggering income. This is preferable to direct withdrawals, which are taxable. LLQP outlines this as a common retirement strategy for affluent clients.
Reference: Insurance Study Guides Chinese.pdf, Universal Life - Leverage and Retirement Planning
질문 # 250
......
우리PassTIP가 제공하는 최신, 최고의IFSE Institute LLQP시험관련 자료를 선택함으로 여러분은 이미 시험패스성공이라고 보실수 있습니다.
LLQP최신 업데이트버전 시험자료: https://www.passtip.net/LLQP-pass-exam.html
그리고 PassTIP LLQP 시험 문제집의 전체 버전을 클라우드 저장소에서 다운로드할 수 있습니다: https://drive.google.com/open?id=1a4MHFaa9rSDCQrpz_-3G1dtNyO__V9gi