No matter which country you are currently in, you can be helped by our Financial-Management real exam. Up to now, our Financial-Management training quiz has helped countless candidates to obtain desired certificate. If you want to be one of them, please take a two-minute look at our Financial-Management Real Exam. And you can just visit our website to know its advantages. You can free download the demos to have a look at our quality and the accuracy of the content easily.
| Section | Weight | Objectives |
|---|---|---|
| Valuation of Securities | 15% | - Bond valuation, yield to maturity, risk characteristics - Stock valuation: dividend growth model, CAPM - Cost of capital components |
| Financial Markets and Corporate Objectives | 15% | - Types of financial markets and instruments - Goal of the firm: shareholder wealth maximization - Role of financial institutions |
| Financial Statement Analysis | 20% | - Ratio analysis: liquidity, profitability, solvency, efficiency - Income statement, balance sheet, cash flow statement - Common-size and trend analysis |
| Risk and Return | 12% | - Portfolio risk and diversification - Systematic vs unsystematic risk - Beta and Capital Asset Pricing Model |
| Capital Structure and Financing | 10% | - Dividend policy and payout decisions - Leverage and cost of capital |
| Time Value of Money | 18% | - Effective vs nominal interest rates - Present value, future value, annuities, perpetuities - Discounted cash flow valuation |
| Capital Budgeting | 10% | - Cash flow estimation and project evaluation - NPV, IRR, payback period, profitability index |
>> Financial-Management New Practice Questions <<
As we know, everyone has opportunities to achieve their own value and life dream. And our Financial-Management can help them achieve all of these more easily and leisurely. Our Financial-Management exam materials are pleased to serve you as such an exam tool. With over a decade’s endeavor, our Financial-Management Practice Guide successfully become the most reliable products in the industry. There is a great deal of advantages of our Financial-Management exam questions you can spare some time to get to know.
NEW QUESTION # 25
Which type of security has voting rights associated with it?
Answer: A
Explanation:
Voting rights are a defining characteristic of common stock and represent ownership and control in a corporation. Holders of common stock typically have the right to vote on key corporate matters such as electing the board of directors, approving major mergers or acquisitions, and authorizing significant changes to corporate governance. These rights align with the role of shareholders as residual claimants, meaning they receive what is left after all other obligations-such as debt and preferred dividends-are met. Preferred stockholders usually do not have voting rights under normal conditions, as preferred stock is structured to resemble a hybrid between debt and equity, emphasizing fixed dividend payments rather than control. Bondholders and holders of convertible notes are creditors, not owners, and therefore have no voting power in corporate decisions. From a financial management perspective, voting rights are a key factor in ownership structure, agency relationships, and corporate governance.
Option D correctly identifies common stock as the security that carries voting rights.
NEW QUESTION # 26
What is a holding cost in inventory management?
Answer: A
Explanation:
Holding cost, also called carrying cost, refers to the costs a firm incurs by keeping inventory on hand over time. These costs include storage, insurance, obsolescence, deterioration, spoilage, and the risk of price declines or damage. In addition, financial management often includes the opportunity cost of capital tied up in inventory as part of carrying cost. The key idea is that inventory is not free to hold; it uses space, requires protection, and can lose value while sitting unsold. Choice D is correct because it captures an important category of holding cost: the expense related to damage or unfavorable price changes. Choice A is incorrect because a discount to customers is a selling decision, not a holding cost. Choice B describes a production investment rather than an inventory carrying cost. Choice C relates more to receivables collection than to inventory holding. Effective inventory management aims to balance holding costs against ordering costs and stockout risk. Therefore, D is the correct answer because holding costs arise from maintaining inventory and facing the risk that stored goods may deteriorate, become obsolete, or lose value over time.
========
NEW QUESTION # 27
In the statement of cash flows, how should an increase in accounts receivable be treated when calculating cash collected from customers?
Answer: A
Explanation:
When calculating cash collected from customers, an increase in accounts receivable must be subtracted from revenue. This is because revenue includes both cash sales and credit sales, but cash collected reflects only the amount actually received during the period. If accounts receivable increased, it means some portion of reported sales has not yet been collected in cash. Therefore, that increase must be deducted to convert accrual- based revenue into a cash basis amount. The general relationship is: Cash Collected from Customers = Sales Revenue # Increase in Accounts Receivable, assuming no other unusual adjustments. This treatment is important in preparing or interpreting the operating section of the statement of cash flows, especially under the direct method. Financial management relies on this distinction because firms may appear profitable on the income statement while still facing liquidity pressure if collections are slow. The other answer choices are incorrect because accounts receivable relates to sales revenue, not cost of goods sold. Therefore, A is the correct answer because subtracting the increase in receivables properly adjusts reported revenue to the actual cash collected from customers during the accounting period.
========
NEW QUESTION # 28
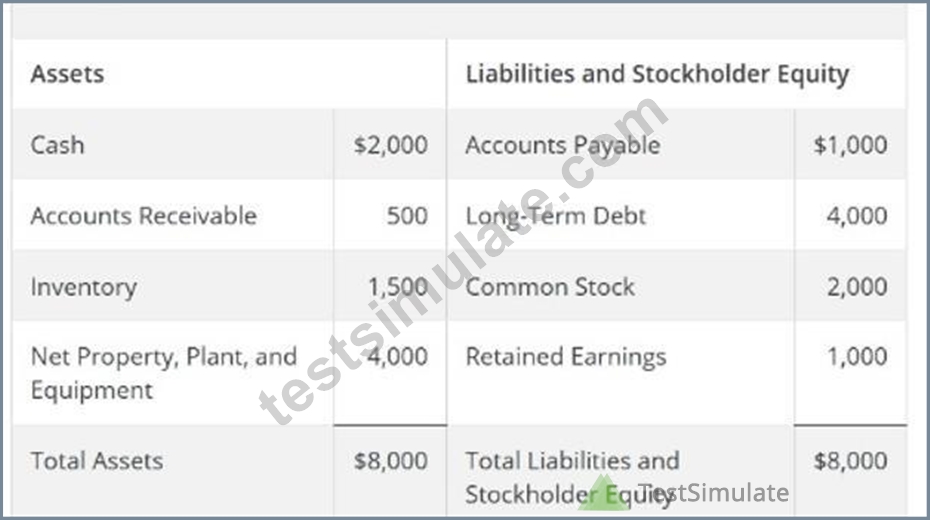
Use Whole Pine Inc.'s financial statements for 20X3 below to answer the following question.
What is Whole Pine Inc.'stotal asset turnoverfor 20X3?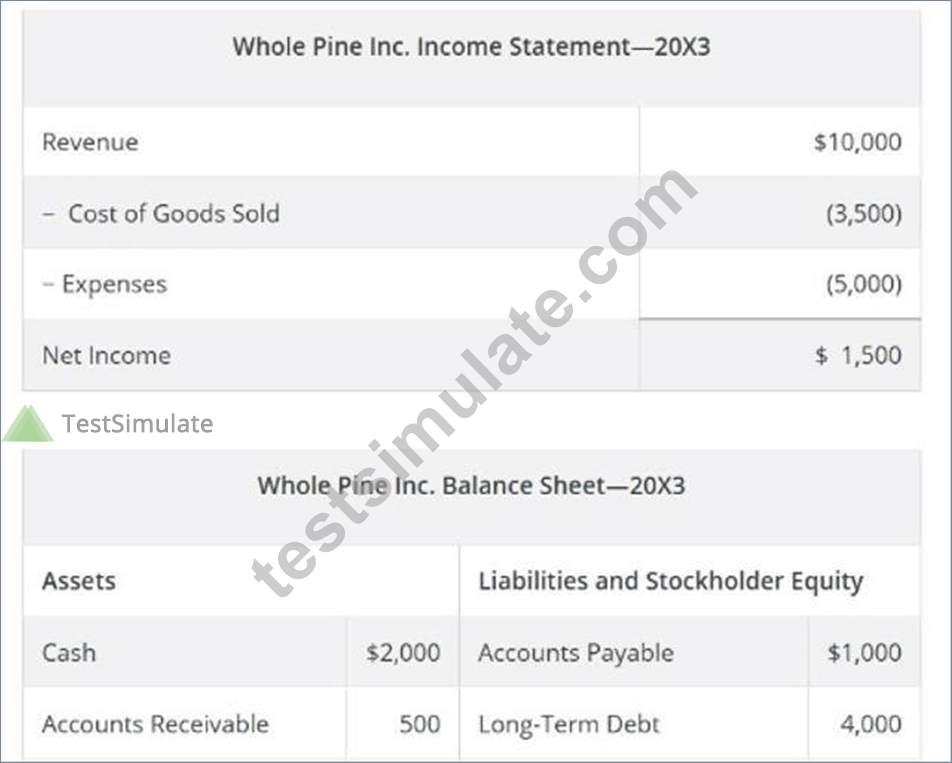
Answer: B
Explanation:
Total asset turnover measures how efficiently a firm uses its assets to generate revenue. It is calculated as Sales ÷ Total Assets. For Whole Pine Inc., sales for 20X3 are $10,000 and total assets are $8,000.
Dividing $10,000 by $8,000 yields a total asset turnover of 1.25. This means the company generates
$1.25 in sales for every $1.00 invested in assets. From a financial management perspective, this ratio is a key indicator of operating efficiency and is commonly compared across firms within the same industry or across time. A higher turnover suggests more efficient use of assets, while a lower turnover may indicate underutilized capacity or inefficient asset deployment. Asset turnover is also a component of the DuPont analysis, linking operational efficiency to return on equity. Option B correctly reflects both the calculation and interpretation consistent with standard financial analysis practice.
NEW QUESTION # 29
How does the use of historical returns to estimate the cost of common equity differ from the Gordon growth model?
Answer: B
Explanation:
The historical-return approach differs from the Gordon growth model because it is based primarily on past stock performance rather than on expected future dividends and growth. Under the historical-return method, analysts estimate the cost of common equity by examining the returns investors earned on the firm's stock over prior periods. The Gordon growth model, by contrast, is a forward-looking dividend-based approach that estimates the cost of equity as the expected dividend yield plus the constant growth rate of dividends. Choice D is correct because it captures the defining feature of the historical-return method. Choice B and choice C describe the Gordon growth model rather than the historical-return approach. Choice A is more closely associated with CAPM, which uses market risk and beta. Financial management often uses multiple methods to estimate the cost of equity because each approach has limitations. Historical returns can be useful as a reference point, but they may not reflect current risk or investor expectations. The Gordon growth model can be useful for stable dividend-paying firms, but it is less suitable for firms without predictable dividends.
Therefore, D correctly explains the main difference between these two valuation methods.
========
NEW QUESTION # 30
......
It is well known that the best way to improve your competitive advantages in this modern world is to increase your soft power, such as graduation from a first-tier university, fruitful experience in a well-known international company, or even possession of some globally recognized Financial-Management certifications, which can totally help you highlight your resume and get a promotion in your workplace to a large extend. If you are interested our Financial-Management Guide Torrent, please contact us immediately, we would show our greatest enthusiasm to help you obtain the certification.
Exam Financial-Management Prep: https://www.testsimulate.com/Financial-Management-study-materials.html