What's more, part of that Prep4SureReview AFP-Exam-1 dumps now are free: https://drive.google.com/open?id=1CAX0ache_-VIP9qgnQcnMgsNc84s1ZOB
As we all know it is not easy to obtain the AFP-Exam-1 certification, and especially for those who cannot make full use of their sporadic time. But you are lucky, we can provide you with well-rounded services on AFP-Exam-1 practice braindumps to help you improve ability. You would be very pleased and thankful if you can spare your time to have a look about features of our AFP-Exam-1 Study Materials. With the pass rate high as 98% to 100%, you can totally rely on our AFP-Exam-1 exam questions.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Technical Competencies | 84% | - Risk Management and Insurance - Asset and Liability Management - Estate Planning - Retirement Planning - Tax Planning - Investment Planning |
| Topic 2: Enabling Competencies | 16% | - Professional Conduct and Regulatory Compliance - Client Relationship and Practice Management |
>> Exam AFP-Exam-1 Study Guide <<
Prep4SureReview is also offering 90 days free AFP-Exam-1 updates. You can update your AFP-Exam-1 study material for one year from the date of purchase. The AFP-Exam-1 updated package will include all the past questions from the past papers. You can pass the AFP-Exam-1 exam easily with the help of the PDF dumps included in the package. It will have all the questions that you should cover for the AFP-Exam-1 AFP-Exam-1 exam. If you are facing any issues with the products you have, then you can always contact our 24/7 support to get assistance.
NEW QUESTION # 107
A household has gross monthly income of $9,500. Their monthly mortgage payment is $2,100, property taxes are $425, heating costs are $175, car payments are $600, and minimum credit card payments are $250. What is their total debt service ratio?
Answer: D
Explanation:
Total debt service ratio includes housing debt costs plus other recurring debt obligations. The monthly obligations are: mortgage $2,100, property taxes $425, heating $175, car payments $600, and credit card minimums $250. Total monthly debt service is $3,550. Dividing $3,550 by gross monthly income of $9,500 gives 0.3737, or approximately 37.4%. Option A is close to a housing-only calculation that omits non- mortgage debt. Option B still understates the total obligation. Option D is too high based on the numbers provided. Debt service ratios help assess borrowing capacity, but they are not the entire planning answer. A planner should also test stability of employment, emergency reserves, renewal risk, variable-rate exposure, childcare costs, and discretionary spending. In this question, however, the calculation itself is decisive: all stated recurring debt obligations must be included for the total debt service ratio. References/topics: TDS ratio, mortgage affordability, liability analysis, cash flow planning.
NEW QUESTION # 108
In order to increase the assets in Rebecca's retirement savings, her financial planner is considering making a number of recommendations. Prior to obtaining her current employment, she withdrew funds from her RRSP under the Lifelong Learning Plan to upgrade her skills. She has four annual installments remaining on her Lifelong Learning Plan withdrawal and a small amount of savings in a TFSA. Rebecca now works as a sales associate in a small clothing store that has a group RRSP program for all employees which matches employee contributions. Which recommendation provides the best long-term impact to grow her retirement savings?
Answer: A
Explanation:
The company group RRSP match is the strongest long-term retirement recommendation because it provides immediate additional savings from the employer. A matching contribution is effectively a guaranteed enhancement to Rebecca's retirement funding that she cannot replicate by simply transferring her TFSA or changing her asset mix. Repaying the Lifelong Learning Plan installments is required, but it does not create new employer-funded retirement capital. Maximizing equity exposure may improve expected return, but it must remain within risk tolerance and does not replace the value of free matching contributions. Transferring TFSA savings to an RRSP may produce a deduction, yet it sacrifices TFSA flexibility and does not address the employer match. The AFP planning priority is to capture available employer contributions first, then coordinate LLP repayments, TFSA use, and ongoing RRSP savings. Study Guide focus: group RRSPs, employer matching, LLP repayment, retirement accumulation, and savings prioritization. Missing the match would leave employer money unclaimed, which is rarely defensible when the employee can afford the contribution.
NEW QUESTION # 109
Janet's non-registered account holds the funds listed in the following table: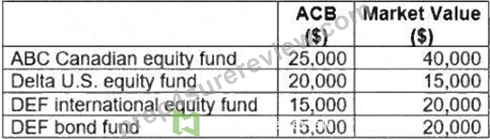
Assuming a marginal tax rate of 45%, what amount of tax payable will Janet incur if she redeems the account to fund the purchase of a new business?
Answer: C
Explanation:
Janet's taxable result comes from the net realized capital gain, not from the total market value redeemed. The ABC Canadian equity fund has a $15,000 gain, the Delta U.S. equity fund has a $5,000 loss, the DEF international equity fund has a $5,000 gain, and the DEF bond fund has a $5,000 gain. Net capital gains are therefore $20,000 after offsetting the Delta loss. Only one-half of the net capital gain is taxable under the standard capital gains inclusion treatment used in AFP-level calculations, producing a $10,000 taxable capital gain. At a 45% marginal tax rate, the tax payable is $4,500. Option A taxes the full net gain; option C and option D reflect incorrect inclusion or arithmetic assumptions. The purpose of the question is to test disposition analysis in a non-registered account and the sequence of gain/loss netting before applying the marginal rate. Study Guide focus: adjusted cost base, fair market value, capital gains inclusion, and non- registered tax planning.
NEW QUESTION # 110
A client asks when his RRSP must generally be converted to a retirement income vehicle. What should the planner explain?
Answer: B
Explanation:
RRSP maturity is age-based. In general, an RRSP must be converted to a retirement income option, such as a RRIF or annuity, by the end of the calendar year in which the annuitant turns 71. Minimum RRIF withdrawals begin the following year if a RRIF is selected. Option B confuses eligibility for some retirement benefits and pension planning milestones with RRSP maturity. Option C is wrong because employment status does not eliminate the conversion requirement. Option D is not required and may be tax-inefficient; a full cash withdrawal could trigger substantial taxable income. A planner should treat conversion as a planning decision, not an administrative afterthought. The client's spouse's age, required income, tax bracket, pension splitting, investment mix, estate goals, and OAS exposure may influence whether to use a RRIF, annuity, or combination. The correct exam answer is the age-71 year-end deadline. References/topics: RRSP maturity, RRIF conversion, annuities, retirement income planning.
NEW QUESTION # 111
Huxley is meeting with his financial planner to review his retirement goals. He has saved $250,000 in an RRSP, currently contributes $10,000 per year, and his portfolio is expected to continue to earn an average of
5% per year. Huxley is hoping to retire in 18 years with $1 million saved in his RRSP. What strategy should Huxley's financial planner recommend to ensure he is on track?
Answer: C
Explanation:
Huxley is not on track under the existing assumptions. His $250,000 RRSP growing at 5% for 18 years, plus
$10,000 annual contributions at the same return, accumulates to approximately $883,000, not $1,000,000. The shortfall is about $117,000 at the target date. Increasing monthly contributions by $350 produces additional future value that is sufficient to close the gap without relying on a much higher risk profile or delaying retirement. Raising the goal to $1,250,000 makes the gap worse. Extending retirement to 25 years may solve the math but changes the client's stated retirement objective. Targeting 12% return is aggressive and may be unsuitable; a planner should not fix a savings gap by assuming unrealistic risk. The most controlled recommendation is higher contributions. Study Guide focus: RRSP accumulation, future value, savings shortfall, contribution planning, and retirement goal feasibility. This keeps the recommendation inside controllable client behaviour rather than relying on market returns outside the planner's control.
NEW QUESTION # 112
......
According to our investigation, the test syllabus of the AFP-Exam-1 exam is changing every year. Some new knowledge will be added into the annual real exam. Some old knowledge will be deleted. So you must have a clear understanding of the test syllabus of the AFP-Exam-1 study materials. Now, you can directly refer to our study materials. Our experts have carefully researched each part of the test syllabus of the AFP-Exam-1 Study Materials. Then they compile new questions and answers of the study materials according to the new knowledge parts.
Latest AFP-Exam-1 Demo: https://www.prep4surereview.com/AFP-Exam-1-latest-braindumps.html
P.S. Free & New AFP-Exam-1 dumps are available on Google Drive shared by Prep4SureReview: https://drive.google.com/open?id=1CAX0ache_-VIP9qgnQcnMgsNc84s1ZOB