BONUS!!! Download part of Prep4King AFP-Exam-1 dumps for free: https://drive.google.com/open?id=1xBKAPavo33E2uIi4przXWVwxy-Twib55
Through years of persistent efforts and centering on the innovation and the clients-based concept, our company has grown into the flagship among the industry. Our company struggles hard to improve the quality of our AFP-Exam-1 exam prep and invests a lot of efforts and money into the research and innovation of our AFP-Exam-1 Study Guide. Our brand fame in the industry is famous for our excellent AFP-Exam-1 study guide. High quality, considerate service, constant innovation and the concept of customer first on our AFP-Exam-1 exam questions are the four pillars of our company.
| Section | Objectives |
|---|---|
| Insurance and Risk Management | - Risk mitigation strategies in financial planning - Life and health insurance fundamentals |
| Retirement Planning | - Retirement savings vehicles and planning principles |
| Financial Planning Foundations | - Ethics and professional standards in financial advising - Financial planning process and client relationship management |
| Investment Planning | - Investment products and risk-return profiles - Asset allocation and portfolio basics |
| Taxation Concepts | - Tax-efficient investment strategies - Personal income tax principles |
Obtaining a certificate may be not an easy thing for some candidates, choose us, we will help you get the certificate easily. AFP-Exam-1 learning materials are edited by experienced experts, therefore the quality and accuracy can be guaranteed. In addition, AFP-Exam-1 exam braindumps contact most of knowledge points for the exam, and you can mater the major knowledge points well by practicing. In order to improve your confidence to AFP-Exam-1 Exam Materials, we are pass guarantee and money back guarantee. If you fail to pass the exam by using AFP-Exam-1 exam materials, we will give you full refund.
NEW QUESTION # 64
Janet's non-registered account holds the funds listed in the following table: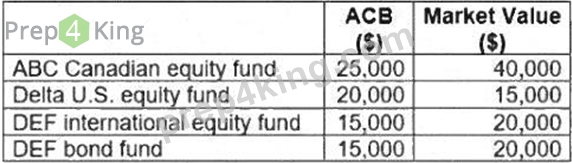
Assuming a marginal tax rate of 45%, what amount of tax payable will Janet incur if she redeems the account to fund the purchase of a new business?
Answer: C
Explanation:
Janet's taxable result comes from the net realized capital gain, not from the total market value redeemed. The ABC Canadian equity fund has a $15,000 gain, the Delta U.S. equity fund has a $5,000 loss, the DEF international equity fund has a $5,000 gain, and the DEF bond fund has a $5,000 gain. Net capital gains are therefore $20,000 after offsetting the Delta loss. Only one-half of the net capital gain is taxable under the standard capital gains inclusion treatment used in AFP-level calculations, producing a $10,000 taxable capital gain. At a 45% marginal tax rate, the tax payable is $4,500. Option A taxes the full net gain; option C and option D reflect incorrect inclusion or arithmetic assumptions. The purpose of the question is to test disposition analysis in a non-registered account and the sequence of gain/loss netting before applying the marginal rate. Study Guide focus: adjusted cost base, fair market value, capital gains inclusion, and non- registered tax planning.
NEW QUESTION # 65
Jaycee has created an investment portfolio for his client, Adam, which is designed to achieve his long-term objectives and is consistent with his risk tolerance and constraints. It also has to be reassessed periodically to ensure that the long-term benchmark mix continues to reflect Adam's circumstances. Which asset allocation strategy is Jaycee utilizing?
Answer: A
Explanation:
Jaycee is using strategic asset allocation. The portfolio is built around Adam's long-term objectives, risk tolerance, constraints, and benchmark mix, then reassessed periodically to confirm that the policy allocation still fits his circumstances. Strategic allocation is not an attempt to move aggressively between sectors or asset classes based on near-term forecasts. Tactical allocation would involve short-term deviations from the policy mix to exploit perceived market opportunities. Active management refers to security selection or manager decisions intended to outperform a benchmark. Integrated is not the standard allocation term being tested. The AFP course treatment emphasizes that the long-term asset mix is the primary driver of portfolio risk and return; periodic review and rebalancing keep the portfolio aligned with the plan. Jaycee's process is disciplined, policy-based, and client-specific, which is strategic allocation. Study Guide focus: strategic asset allocation, rebalancing, investment policy, risk tolerance, and long-term benchmark mix. The review does not replace the policy mix; it tests whether the policy mix still remains appropriate.
NEW QUESTION # 66
A financial planner recently started her new role at the bank and decided to create a checklist when meeting with prospects. She wanted to include one item on the checklist that would allow her to understand her clients' tolerance for risk. What information should she add, that will help her achieve this objective?
Answer: C
Explanation:
Risk tolerance is measured through qualitative discovery, not through tax records or product documents. A properly designed questionnaire captures how the client thinks and behaves when markets decline, how much volatility is acceptable, whether losses create anxiety, and how the client prioritizes safety versus growth. Tax returns may reveal income and deductions, but they do not establish willingness to accept investment risk. A life insurance policy is relevant to risk management, not market-risk tolerance. A previous financial plan may provide useful background, but it may be outdated and still requires current confirmation. The questionnaire is only one part of the process; the planner should also assess risk capacity using objective facts such as time horizon, liquidity, income stability, debt level, and goal flexibility. For the checklist item requested, however, qualitative questionnaire is the correct answer. Study Guide focus: risk profiling, qualitative discovery, behavioural finance, KYC, and suitability. That behavioural evidence is then reconciled with objective capacity before an investment recommendation is made.
NEW QUESTION # 67
Bill is reviewing his credit bureau after being declined for a loan. He believes a loan that does not belong to him is appearing on the report. Which section should he review most closely?
Answer: B
Explanation:
A liability that appears to belong to Bill would normally be found in the account history or trade-line section of the credit bureau. That section lists credit facilities such as loans, credit cards, lines of credit, balances, payment status, limits, and delinquency history. Option A is relevant when reviewing who accessed the report, but an inquiry is not itself a liability. Option B may show judgments, bankruptcies, or other public- record items, but a regular loan account is more likely to appear in account history. Option D should still be checked because identity errors can cause mixed files, but it is not where the disputed liability would usually be described. The planner should advise Bill to obtain the full report, identify the creditor, dispute inaccurate information with the bureau and lender, and retain supporting documentation. Credit accuracy matters because lenders assess repayment history, outstanding debt, utilization, and derogatory information when approving credit. References/topics: credit bureau review, account history, borrowing capacity, liability management.
NEW QUESTION # 68
Harley is a novice investor who has just set up his first FHSA. He has a high-risk tolerance to market volatility and his primary investment objective is growth. He would like to invest $10,000 and will use the funds as part of the first-time home buyers plan within the next year. What investment should Harley purchase within this FHSA?
Answer: D
Explanation:
Harley's stated risk tolerance is not the controlling fact. The decisive constraint is time horizon: he intends to use the FHSA money within the next year for a first home purchase. When a required withdrawal is near, capital preservation and liquidity outrank long-term growth. A high-interest savings account is therefore the appropriate holding because it keeps the funds accessible and avoids exposing the down payment to equity market volatility. A locked-in one-year GIC may preserve capital, but it can create liquidity problems if the home purchase occurs before maturity. Equity-focused and income-focused mutual funds can fluctuate in value and may be unsuitable for funds earmarked for a near-term transaction. In AFP investment planning, risk capacity can be low even when risk tolerance is high; the client cannot afford a market loss shortly before the purchase. Study Guide focus: FHSA funding, investment time horizon, liquidity, risk capacity, and short- term goal funding.
NEW QUESTION # 69
......
In informative level, we should be more efficient. In order to take the initiative, we need to have a strong ability to support the job search. And how to get the test AFP-Exam-1 certification in a short time, which determines enough qualification certificates to test our learning ability and application level. We hope to be able to spend less time and energy to take into account the test AFP-Exam-1 Certification, but the qualification examination of the learning process is very wasted energy, so how to achieve the balance? The AFP-Exam-1 exam prep can be done to help you pass the AFP-Exam-1 exam.
AFP-Exam-1 Exam Simulator Free: https://www.prep4king.com/AFP-Exam-1-exam-prep-material.html
DOWNLOAD the newest Prep4King AFP-Exam-1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1xBKAPavo33E2uIi4przXWVwxy-Twib55