DOWNLOAD the newest PDFDumps AFP-Exam-1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1DMa_kza4lfWhLkcPrWp_GAIwUalbAETC
Are you still upset about how to pass CSI certification AFP-Exam-1 exam? Are you still waiting for the latest information about CSI certification AFP-Exam-1 exam? PDFDumps has come up with the latest training material about CSI certification AFP-Exam-1 exam. Do you want to pass CSI certification AFP-Exam-1 exam easily? Please add PDFDumps's CSI certification AFP-Exam-1 exam practice questions and answers to your cart now! PDFDumps has provided part of CSI Certification AFP-Exam-1 Exam practice questions and answers for you on www.PDFDumps.com and you can free download as a try. I believe you will be very satisfied with our products. With our products you can easily pass the exam. We promise that if you have used PDFDumps's latest CSI certification AFP-Exam-1 exam practice questions and answers exam but fail to pass the exam, PDFDumps will give you a full refund.
| Section | Weight | Objectives |
|---|---|---|
| Asset and Liability Management | 11% | - Budgeting - Cash Flow Management - Personal Balance Sheet Analysis - Debt Management |
| Risk Management and Insurance | 12% | - Disability and Health Insurance - Life Insurance - Risk Assessment - Risk Transfer Strategies |
| Professional Conduct and Regulatory Compliance | 10% | - Regulatory Requirements - Ethics and Professional Standards - Compliance Responsibilities |
| Estate Planning | 13% | - Trust and Beneficiary Planning - Wills - Powers of Attorney - Estate Transfer Strategies |
| Retirement Planning | 17% | - Retirement Needs Analysis - Retirement Income Strategies - Pension Plans - Registered Retirement Savings Plans |
| Tax Planning | 14% | - Tax Deductions and Credits - Tax-Efficient Strategies - Income Tax Fundamentals - Registered Plans |
| Investment Planning | 17% | - Asset Allocation - Investment Theory - Investment Products - Portfolio Construction |
| Client Relationship and Practice Management | 6% | - Practice Management - Communication and Advisory Process - Client Discovery |
>> Valid Dumps AFP-Exam-1 Ebook <<
For exam applicants PDFDumps offers real CSI AFP-Exam-1 exam questions. There are three formats of the Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) practice material. These formats are PDF, desktop practice exam software, and web-based Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) practice exam. With these questions, you can crack the CSI AFP-Exam-1 certification exam and save your time and money.
NEW QUESTION # 11
Justis, age 62, and his wife Jen, age 58, are meeting with their financial planner, Luke. They are both planning to retire by age 65. Their goals are to minimize debt and reduce taxes. The couple's financial situation is outlined below.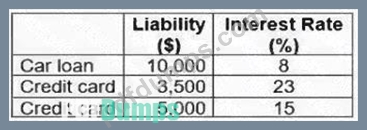
Justis' annual income is $25,000. He has a $15,000 RRSP, $30,000 single non-registered account and a
$25,000 TFSA. Jen's annual income is $60,000, and she has a $150,000 RRSP, $50,000 single non-registered account and a $20,000 TFSA.
Jen's marginal tax rate is 35%, and Justis' is 25%. Assuming all investments are making interest income of
10%, what would be the most appropriate strategy for Luke to recommend for the couple?
Answer: C
Explanation:
Luke should recommend using Jen's non-registered funds because that option clears the liabilities without triggering registered-plan withdrawal income. The debts total $18,500 and include expensive consumer borrowing: credit cards at 23% and 15%, plus a car loan at 8%. The couple's taxable investments earn 10% interest before tax, so Jen's after-tax return is approximately 6.5% at a 35% marginal rate. Paying the credit cards is equivalent to earning a risk-free after-tax return equal to the interest avoided, which is materially better than leaving the money invested. Using either spouse's RRSP would create taxable income and permanently reduce retirement capital. Using Justis's non-registered funds is less effective because his lower tax rate makes his after-tax investment return higher than Jen's, so Jen's taxable account is the better source.
Study Guide focus: debt repayment priority, after-tax returns, registered versus non-registered withdrawals, and household cash-flow planning. The recommendation also preserves retirement accounts for the couple's age-65 objective while eliminating the highest-cost liabilities first.
NEW QUESTION # 12
The Andersons, a young couple, meet with their financial planner to review estate-planning opportunities.
They recently had a third child and are looking for the most cost-effective strategy to put in place during their working years to increase their estate value and reduce the tax burden at death for the benefit of their children.
What should the financial planner recommend?
Answer: C
Explanation:
A term survivorship life insurance policy is the most cost-effective fit for the Andersons' objective. They are a young working couple with children and want to increase estate value and reduce the tax burden at death for the benefit of the children. Survivorship coverage pays on the second death, which is when final estate transfer costs and taxes commonly become due for the next generation. Term coverage keeps the premium lower during the working years compared with permanent insurance. Naming the estate as beneficiary of registered plans can increase probate exposure and does not reduce tax. Permanent individual policies may be useful for lifetime estate liquidity, but they are usually more expensive than required for a cost-sensitive young family. A joint savings account does not create immediate estate liquidity if both parents die early.
Study Guide focus: survivorship insurance, estate liquidity, family protection, term insurance, and cost- effective risk management. The policy should be coordinated with wills, guardianship arrangements, registered plan beneficiaries, and expected final tax exposure.
NEW QUESTION # 13
Chris is a self-employed contractor discussing his retirement plans with his financial planner, Joseph. Chris is considering incorporating his business and drawing funds from his corporation to fund his retirement income, yet he wants to ensure it does not impact his business's financial position. What advice should Joseph give to Chris?
Answer: D
Explanation:
Joseph should refer Chris to an accountant because the immediate issue is the tax and financial impact of incorporation and retirement cash extraction. Incorporating can change how income is earned, retained, invested, and withdrawn through salary, dividends, shareholder loans, or corporate distributions. It can affect CPP participation, RRSP room, passive investment income, corporate cash flow, creditor separation, and after- tax retirement funding. A lawyer is important for legal formation, shareholder agreements, and corporate records, but the facts emphasize the business's financial position and retirement-income funding. An online incorporation service is insufficient for planning. Joseph should not provide detailed corporate tax advice outside his competence or recommend changes without specialist input. The AFP standard is to identify the planning issue, explain the need for coordinated advice, and refer to the appropriate professional. Study Guide focus: incorporation, tax integration, professional referrals, retirement cash flow, and scope of competence.
The referral should occur before Chris restructures compensation, retains corporate surplus, or relies on corporate assets for retirement income.
NEW QUESTION # 14
Which assets will flow through an estate?
Answer: D
Explanation:
Estate administration begins with ownership form. A joint tenancy with right of survivorship normally passes directly to the survivor, while an inter vivos trust owns the property outside the deceased's personal estate and a properly funded buy-sell arrangement directs business continuity through contract. Tenancy in common is different: each owner holds a separate, divisible interest. On death, that interest does not disappear and does not vest automatically in the other co-owner. It is property of the deceased and is administered under the will or, if there is no valid will, under intestacy legislation. For AFP purposes, the tested distinction is probate exposure versus survivorship or beneficiary transfer. The asset described in option B is therefore the one that flows through the estate. Study Guide focus: estate ownership, survivorship, trusts, probate property, and estate administration. This distinction is central when determining executor authority, probate value, and whether an asset bypasses estate administration by contract or title.
NEW QUESTION # 15
Mina has $20,000 in a savings account earning 3% before tax. She also has a $9,000 credit card balance at
22%, a $7,000 unsecured line of credit at 10%, and a $14,000 car loan at 4%. Her marginal tax rate is 35%.
Which liability should she target first?
Answer: B
Explanation:
The credit card is the highest-cost non-deductible liability and should be the first repayment target, subject to retaining an adequate emergency reserve. Mina's savings account produces only 3% before tax, or 1.95% after tax at a 35% marginal rate. That return is overwhelmed by a 22% credit card rate. Paying the card produces a risk-free improvement equal to avoided interest; no conservative investment can justify carrying that balance. Option A is lower priority because the car loan rate is modest. Option C is important but still secondary to the credit card. Option D ignores the after-tax spread between savings income and debt cost. The planning principle is not simply "pay debt"; it is to compare after-tax investment returns with after-tax borrowing costs, prioritizing expensive consumer debt while preserving liquidity. The planner should then structure a repayment plan and address the spending pattern that created the balance. References/topics: debt prioritization, cash flow, after-tax return, asset and liability management.
NEW QUESTION # 16
......
The CSI AFP-Exam-1 exam offers a great opportunity for beginner and experienced to validate their expertise in a short time period. To do this they just need to pass the Applied Financial Planning Certification Exam 1 (AFP) AFP-Exam-1 Certification Exam which is not an easy task. And PDFDumps offfers latest AFP-Exam-1 exam practice, exam pattern and practice exam online.
Latest AFP-Exam-1 Test Testking: https://www.pdfdumps.com/AFP-Exam-1-valid-exam.html
BONUS!!! Download part of PDFDumps AFP-Exam-1 dumps for free: https://drive.google.com/open?id=1DMa_kza4lfWhLkcPrWp_GAIwUalbAETC