P.S. Free 2026 Guidewire ClaimCenter-Business-Analysts dumps are available on Google Drive shared by ExamCost: https://drive.google.com/open?id=12Qi18BAsX17hbk3as6Hg6oDq31pWr0Se
On the one thing, our company has employed a lot of leading experts in the field to compile the ClaimCenter-Business-Analysts exam torrents, so you can definitely feel rest assured about the high quality of our ClaimCenter-Business-Analysts question torrents. On the other thing, the pass rate among our customers who prepared the exam under the guidance of our ClaimCenter-Business-Analysts study materials has reached as high as 98% to 100%. What's more, you will have more opportunities to get promotion as well as a pay raise in the near future after using our ClaimCenter-Business-Analysts question torrents since you are sure to get the certification. So you can totally depend on our ClaimCenter-Business-Analysts exam torrents when you are preparing for the exam. If you want to be the next beneficiary, just hurry up to purchase.
| Certification Vendor: | Guidewire |
|---|---|
| Exam Name: | ClaimCenter Business Analyst - Mammoth Proctored Exam |
| Exam Number: | ClaimCenter-Business-Analysts |
| Exam Price: | USD 250 |
| Exam Format: | Multiple Choice, Single Choice |
| Passing Score: | 70% |
| Exam Duration: | 120 minutes |
| Available Languages: | English |
| Certificate Validity Period: | 3 years |
| Real Exam Qty: | 50 |
| Related Certifications: | Guidewire Certified Professional |
| Sample Questions: | Guidewire ClaimCenter-Business-Analysts Sample Questions |
| Exam Way: | Proctored |
| Pre Condition: | Candidates are recommended to complete Guidewire ClaimCenter training courses and have hands-on experience with ClaimCenter configuration and business analysis. |
| Official Syllabus URL: | https://education.guidewire.com |
>> Online ClaimCenter-Business-Analysts Version <<
Even if you have received a lot of services, you will still be surprised by the service of our ClaimCenter-Business-Analysts simulating exam. Our company takes great care in every aspect from the selection of staff, training, and system setup. No matter what problems of the ClaimCenter-Business-Analysts Practice Questions you encounter, our staff can solve them for you right away and give you the most professional guide. And our service can help you 24/7 on the the ClaimCenter-Business-Analysts exam materials.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
NEW QUESTION # 32
To optimize business process workflow, an insurer has spent a great deal of effort on estimating the amount of effort required to complete various types of work... They are also aware that certain situations may require specialized expertise and want to incorporate this in their decision making.
All claims and exposures are entered using only the ClaimCenter new claim wizard. Once entered, the work should be automatically distributed fairly to those properly suited, as determined by the company's knowledge of each worker's skill set.
Which two assignment mechanisms, alone or together, will achieve their goal? (Choose two.)
Answer: C,D
Explanation:
To meet the dual requirements of "specialized expertise" and "fair distribution based on effort," the Business Analyst should utilize User Attributes and Weighted Workload assignment rules.
* User Attributes (Option B):This feature handles the "specialized expertise" requirement.
Administrators can tag users with specific attributes (e.g., "Bilingual," "Heavy Equipment Expert,"
"Litigation Specialist"). Assignment rules can then be configured to filter the pool of potential assignees toonlythose who possess the matching attribute for the specific claim type.
* Weighted Workload (Option D):This feature handles the "fair distribution" and "amount of effort" requirement. Unlike Round-robin (which treats all claims as equal), Weighted Workload assigns a
"weight" (effort points) to the claim and tracks the "load factor" (current capacity) of the user. The system assigns the new work to the user with the lowest relative workload, ensuring that adjusters handling difficult, high-effort claims are not overwhelmed with the same volume as those handling simple claims.
Why other options are incorrect:
* Round-robin (A):Distributes work purely cyclically (1-2-3-1-2-3) without regard for the user's current workload or the complexity of the claim.
* FNOL Queues (C):This is a "pull" mechanism where work sits in a bucket until someone grabs it, rather than the "automatic distribution" (push) requested.
* Supervisor Assignment (E):This is manual, not automatic.
NEW QUESTION # 33
Succeed Insurance requires that all vehicles involved in collisions be evaluated to determine if the vehicle is a total loss. A vehicle claim is deemed a total loss using a calculation based on points earned for selecting specific vehicle information.
What are two examples of acceptance criteria for this business requirement? (Choose two.)
Answer: A,C
Explanation:
Acceptance Criteria (AC) are specific conditions that the software must satisfy to be accepted by the user. In the context of a User Story, AC must be written as testable outcomes or verification steps (pass/fail conditions), not as implementation tasks for the developer.
* Option D (Testable Outcome):"Validate the assignment to the Salvage Group when calculated points are 25 or greater."This is a perfect example of AC. It describes a specific scenario (Points >= 25) and the expected system behavior (Assign to Salvage Group). A tester can run this scenario and objectively determine if the system passes or fails.
* Option A (Testable Outcome):"Ensure that the business rule generates the Review for Salvage Activity."Similarly, this describes the expectedresultof the logic. It does not tell the developerhowto write the code, but it tells the QA team what to look for (the creation of a specific Activity) to confirm the requirement is met.
Why other options are incorrect:
* Option B ("Add a question..."):This is anImplementation Task. It describes work the developer must do ("Add a question"), but it is not a criterion for verifying the end-to-end business value.
* Option C ("Create a business rule..."):This is also anImplementation Task. A user cannot "test" that a rule was created; they test theeffectof that rule (which is described in A and D). Acceptance criteria focus on the "What" (behavior), while tasks focus on the "How" (configuration).
Here are the 100% verified answers for Question 16 and Question 17, formatted as requested.
NEW QUESTION # 34
Succeed Insurance requires that a new 'Driver under 18?' field be added to the vehicle incident screen for personal auto claims to indicate whether or not the driver of the vehicle was a minor when the loss occurred.
The field will be set by calculating the driver's age using the date of loss and the driver's date of birth.
There are two validation requirements:
* The field must be set if the 'Date of Birth' field for the driver is not null.
* No payments can be made for collision exposures if the 'Date of Birth' field for the driver of the vehicle is null.
A Business Analyst (BA) documents the validation requirements in the validation tab of the User Story Card
'Adjudicate - Update Maintain Vehicle Incident for Personal Auto Claims' as shown in the exhibit.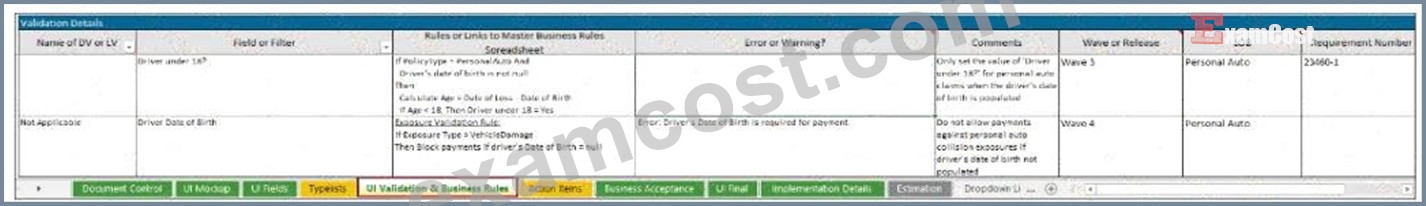
What information in the two validation examples is either missing or incorrectly documented? (Choose two.)
Answer: A,E
Explanation:
The User Story Card exhibit contains several documentation errors when compared to standard Guidewire requirements gathering best practices and the specific scenario provided.
* Missing Requirement Number and Logic Gap (Option C):
* Traceability:In the second row of the exhibit (the payment validation rule), the "Requirement Number" column is completely blank. Traceability back to the original requirements document is mandatory for all entries.
* Logic Precision:The requirement explicitly states that the rule applies to"personal auto claims"
. However, the logic documented in the "Rules" column (If Exposure Type = VehicleDamage Then Block...) doesnotcheck the Policy Type. It relies solely on the Exposure Type, which could exist on Commercial Auto policies as well. To accurately reflect the business requirement, the condition If PolicyType = Personal Auto must be added (similar to how it was done in the first row).
* Missing DV/LV Context for Validation (Option D):
* UI Anchoring:The second requirement is a validation rule that triggers an error ("Driver's Date of Birth is required..."). For the system to highlight the specific field on the screen (the "Driver Date of Birth" widget) when the error occurs, the rule must be associated with the specificDetail View (DV)orList View (LV)where that field resides (e.g., VehicleIncidentDV). The exhibit lists
"Not Applicable" in the "Name of DV or LV" column. This is incorrect because providing the DV name ensures the error message is displayed contextually next to the field rather than as a generic page-level error, improving the user experience.
Why other options are incorrect:
* Option A:The LOB column is used for filtering, reporting, and release management. Even if the rule logic checks the policy type, the LOB column is required metadata and should not be removed.
* Option B:While the first requirement (the calculation) lacks a DV name (which it should have), it is a Business Rule(assignment), not a validation. Therefore, it doesnotgenerate an error or warning message for the user, so the second part of Option B is incorrect.
* Option E:The "Rules" column is exactly where the calculation logic (Date of Loss - Date of Birth) belongs. The developer needs this information to implement the automation.
NEW QUESTION # 35
Succeed Insurance has a requirement to add a new high-risk indicator to the Claim Status screen for property claims that have a lien on the property. A new icon will be added to the configuration to provide a visual indicator making it easier for Adjusters and other ClaimCenter users to determine that a claim has a lien.
Which two common areas of the user interface (UI) can display the new lien icon? (Choose two.)
Answer: A,D
Explanation:
In the standard Guidewire ClaimCenter User Interface architecture, high-priority alerts and claim indicators are displayed in two primary locations to ensure visibility:
* The Info Bar (Option D):This is the persistent strip located at the top of the claim file (just below the Tab Bar). It remains visible regardless of which specific claim sub-screen (Medical, Financials, Notes) the user is navigating. It is designed specifically to host "High Risk Indicators" such as Litigation, Fatalities, Coverage issues, and in this scenario, a "Lien" indicator. This ensures the adjuster is aware of the critical status immediately upon opening the claim.
* The Screen Area (Option A):Specifically, theClaim Status(or Summary) screen-which resides in the main Screen Area-contains a dedicated section for "Claim Indicators." Here, the icon is displayed along with a text description and potential toggle status (On/Off). The prompt explicitly mentions the requirement to "add a new high-risk indicator to the Claim Status screen," confirming the Screen Area as the second location.
Why other options are incorrect:
* Sidebar (B):The sidebar (left panel) is used for the "Actions" menu and navigation links (steps) to move between screens. It does not typically host status icons for the claim object itself.
* Workspace (C):While "Workspace" can refer to the application frame, in UI terminology, it often refers to the specific worksheets (bottom pane) or the container, not the specific UI element for indicators.
* Tab Bar (E):The Tab Bar is for high-level navigation (Claim, Desktop, Administration, Search) and does not display claim-specific data icons.
NEW QUESTION # 36
An Adjuster at Succeed Insurance is handling a personal auto claim for an insured who hit a tree after swerving to avoid a child who ran into the road.
The Adjuster has this Authority Limit Profile: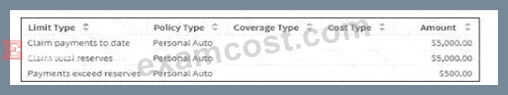
The Adjuster creates a collision exposure and sets the initial reserves so that payments can be made to the insured for repairs to the damaged vehicle. No payments have been created yet.
The current financials for the claim are as follows:
Which two financial transactions will not require approval given that each option is the only transaction change rather than a cumulative change? (Choose two.)
Answer: B,D
Explanation:
To determine if a transaction requires approval, we must compare the proposed transaction against the Adjuster's Authority Limits and the current financial state of the claim.
* Current State:Total Reserves = $3,000 ($2,500 Indemnity + $500 Expense). Total Paid = $0.
* Adjuster Limits:
* Claim Total Reserves Limit: $5,000
* Payments Exceed Reserves Limit: $500
Evaluation of Options:
* Option B (No Approval Required):Making a $2,000 payment against the "Claim Cost - Auto body" reserve.
* The available reserve is $2,500. Since $2,000 < $2,500, the payment does not exceed the reserve.
* The total payments on the claim would be $2,000, which is well below the "Claim payments to date" limit of $5,000.
* Option D (No Approval Required):Increasing the Expense reserve to $550.
* This increases the total claim reserves from $3,000 to $3,050 ($2,500 + $550).
* Since $3,050 is below the Adjuster's "Claim total reserves" limit of $5,000, no approval is triggered.
Why other options require approval:
* Option A:A payment of $1,100 against a $500 reserve means the payment exceeds the reserve by$600.
The Adjuster's limit for "Payments exceed reserves" is only$500. Since $600 > $500, approval is required.
* Option C:Increasing the Auto body reserve to $6,000 would raise the total claim reserves to$6,500 ($6,000 + $500). This exceeds the Adjuster's "Claim total reserves" limit of $5,000, triggering an approval.
NEW QUESTION # 37
......
ClaimCenter-Business-Analysts Real Dump: https://www.examcost.com/ClaimCenter-Business-Analysts-practice-exam.html
P.S. Free 2026 Guidewire ClaimCenter-Business-Analysts dumps are available on Google Drive shared by ExamCost: https://drive.google.com/open?id=12Qi18BAsX17hbk3as6Hg6oDq31pWr0Se