What's more, part of that DumpsMaterials ClaimCenter-Business-Analysts dumps now are free: https://drive.google.com/open?id=12qdn_TaOAvlFr3jHkcH0W5cCz1mF1ZQ2
Owning the DumpsMaterials ClaimCenter-Business-Analysts exam certification training materials is equal to have a bright future, and equal to own the key to success. After you purchase DumpsMaterials's ClaimCenter-Business-Analysts certification exam training materials, we will provide one year free renewal service. If there's any quality problem in ClaimCenter-Business-Analysts Exam Dumps or you fail ClaimCenter-Business-Analysts exam certification, we will give a full refund unconditionally.
| Section | Objectives |
|---|---|
| Quality Assurance & Business Analysis Fundamentals | - Quality Analyst Basics
|
| Behavior Driven Development (BDD) | - BDD in Guidewire
|
| ClaimCenter Financials & Operations | - Financial Transactions
|
| Guidewire InsuranceSuite Fundamentals | - Platform Overview
|
>> ClaimCenter-Business-Analysts Test Dumps <<
The language in our ClaimCenter-Business-Analysts test guide is easy to understand that will make any learner without any learning disabilities, whether you are a student or a in-service staff, whether you are a novice or an experienced staff who has abundant experience for many years. It should be a great wonderful idea to choose our ClaimCenter-Business-Analysts Guide Torrent for sailing through the difficult test. On the whole, nothing is unbelievable, to do something meaningful from now, success will not wait for a hesitate person, go and purchase!
NEW QUESTION # 47
A performing arts organization operates nationwide and is responsible for setting up stages for musical acts and concerts. The organization requires specific insurance coverage for its gear and equipment, including audio systems, lighting, cameras, and control boards. Succeed Insurance wants to optimize claim intake, processing, and reporting for this organization.
Which modifications should be made to ClaimCenter's base product line of business (LOB)?
Answer: C
Explanation:
According to the Guidewire ClaimCenter Business Analyst documentation, ClaimCenter's line of business (LOB) framework is intentionally designed to support extensibility through configuration rather than structural changes to core policy or loss classification elements. When an insurer needs to support specialized insured property-such as professional audio, lighting, and staging equipment-the recommended approach is to enhance the coverage configuration.
ClaimCenter models policy coverage using a hierarchy ofCoverageTypeandCoverage Subtypetypelists.
CoverageType codes represent high-level coverage categories defined by the policy, while Coverage Subtype codes allow insurers to further refine and classify coverage details. These coverage elements are then associated withExposureTypecodes, which drive claim processing behavior such as exposure creation, reserving, payment handling, and reporting.
By adding appropriate CoverageType and Coverage Subtype codes for equipment and gear coverage and mapping them to ExposureType codes, ClaimCenter can automatically create accurate exposures during claim intake. This approach ensures adjusters can efficiently process claims while maintaining consistent workflows and financial controls. It also supports meaningful analytics and reporting without altering the base product structure.
The Guidewire documentation advises against introducing newLossTypeorPolicyTypecodes unless the insurer is defining an entirely new policy or loss classification. LossType codes describe how a loss occurred (for example, theft or accidental damage), not the nature of the insured property. PolicyType changes are similarly broad and unnecessary for extending coverage within an existing LOB.
Therefore, optionBaligns with Guidewire best practices by extending ClaimCenter's coverage and exposure configuration to meet the organization's needs while preserving the integrity of the standard LOB model.
NEW QUESTION # 48
Satisfied with the outcome of a Requirements Workshop, a Business Analyst (BA) attributed the success to preparation. The assigned task had been to document the requirements for capturing details on vehicle incidents for Personal Auto.
* Before the session, the BA reviewed ClaimCenter functionality by creating a new Personal Auto Claim involving physical damage to a vehicle.
* During review, the BA saw that ClaimCenter did not have a graphical representation of a vehicle with clickable hot spots to identify the damage areas like they have in their current application.
* Upon further research, the BA found that Guidewire does offer this functionality and even provides a Graphical Incident Capture Accelerator to ease implementation.
* During the workshop, the BA was able to clearly present all options for capturing vehicle incident details. Instead of having to develop the Vehicle Incident Capture functionality from scratch, the team was able to make a quick decision to add this functionality and end the meeting 30 minutes early.
Which two outcomes demonstrate the importance of preparing for a Requirements Workshop by becoming familiar with the features and functionality of ClaimCenter? (Choose two.)
Answer: C,D
Explanation:
This scenario highlights the value of Feature Knowledge and Gap Analysis during preparation.
* Prevention of unnecessary work (Option A):Because the BA researched and found the "Graphical Incident Capture Accelerator," the team avoided the costly mistake of deciding to "develop the...
functionality from scratch." This is a direct outcome of the BA's preparation preventing an inefficient custom build.
* Comparison of Legacy vs. New (Option B):The text details that the BA "reviewed ClaimCenter functionality" and explicitly noted the difference ("saw that ClaimCenter did not have... like they have in their current application"). This ability to articulate the gap between theAs-Is(Legacy) and theTo-Be (Base ClaimCenter) allowed the BA to present the Accelerator as the perfect bridge solution.
Why other options are incorrect:
* Option C:The team didnotaccept the "base product process" (which lacked the graphics); they accepted theAccelerator(an add-on) to match the legacy expectation of clickable hot spots.
* Option D:The decision was not made "in advance." The text states the team made the "quick decision" during the workshop. The preparation enabled theteam'sdecision, but the BA did not make it unilaterally beforehand.
NEW QUESTION # 49
Succeed Insurance had an embarrassing event last month that had potential legal ramifications. One of their Customer Service Representatives (CSR) shared details of a celebrity's personal auto claim on social media.
Fortunately for Succeed, the celebrity decided not to pursue legal actions as long as Succeed agreed to resolve the potential for future occurrences within the next 30 days.
Succeed executives immediately reacted to the situation by establishing new guidelines regarding claim security. The Business Analyst (BA) assigned to the project researched ClaimCenter base product capabilities and held several requirements gathering sessions designed to document their strategy. The new requirements indicate that only authorized users should be looking at celebrity claims.
Which two features should be used to meet the new requirements? (Choose two.)
Answer: B,D
Explanation:
To restrict access to sensitive claims (such as those involving celebrities) so that "only authorized users" can view them, a Business Analyst must utilize the Claim Security features in Guidewire.
* Specify Claim Security Types (Option A):The first step is to define the classification of the claim.
The system uses the ClaimSecurityType typelist. The BA would add a new typekey (e.g., "Celebrity" or
"High Profile") or use an existing one (e.g., "Sensitive") to flag these specific claims.
* Create/Assign Access Profiles (Option E):Access control in Guidewire is managed throughAccess Profiles(sometimes referred to within Role configurations). An Access Profile maps specificSecurity Levels(like the "Celebrity" type defined above) to permissions. To meet the requirement, the BA defines an Access Profile that grants "View" permission for the "Celebrity" security type and assigns this profileonlyto the authorized users (or roles). Users without this specific Access Profile will be unable to search for or view the claim.
Why other options are incorrect:
* Authority Profiles (B):In Guidewire terminology, "Authority" refers strictly toFinancial Authority (limits on reserves and payments), not data access visibility.
* Hide secure fields (C):This refers toField Level Security(masking specific data like a Tax ID). The requirement is to restrict access to theentire claim, not just specific fields.
* Tracking rules (D):While "Claim Access Auditing" (tracking history) is often enabled for sensitive claims, it is a detective control, not a preventive one. The requirement specifies that unauthorized users should not be looking at the claim at all, which requires the Access Profiles (preventive control).
NEW QUESTION # 50
Succeed Insurance requires that a new 'Driver under 18?' field be added to the vehicle incident screen for personal auto claims to indicate whether or not the driver of the vehicle was a minor when the loss occurred.
The field will be set by calculating the driver's age using the date of loss and the driver's date of birth.
There are two validation requirements:
* The field must be set if the 'Date of Birth' field for the driver is not null.
* No payments can be made for collision exposures if the 'Date of Birth' field for the driver of the vehicle is null.
A Business Analyst (BA) documents the validation requirements in the validation tab of the User Story Card
'Adjudicate - Update Maintain Vehicle Incident for Personal Auto Claims' as shown in the exhibit.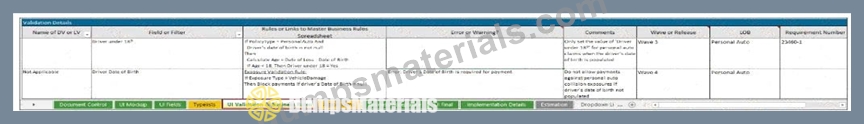
What information in the two validation examples is either missing or incorrectly documented? (Choose two.)
Answer: A,C
Explanation:
The User Story Card exhibit contains several documentation errors when compared to standard Guidewire requirements gathering best practices and the specific scenario provided.
* Missing Requirement Number and Logic Gap (Option C):
* Traceability:In the second row of the exhibit (the payment validation rule), the "Requirement Number" column is completely blank. Traceability back to the original requirements document is mandatory for all entries.
* Logic Precision:The requirement explicitly states that the rule applies to"personal auto claims"
. However, the logic documented in the "Rules" column (If Exposure Type = VehicleDamage Then Block...) doesnotcheck the Policy Type. It relies solely on the Exposure Type, which could exist on Commercial Auto policies as well. To accurately reflect the business requirement, the condition If PolicyType = Personal Auto must be added (similar to how it was done in the first row).
* Missing DV/LV Context for Validation (Option D):
* UI Anchoring:The second requirement is a validation rule that triggers an error ("Driver's Date of Birth is required..."). For the system to highlight the specific field on the screen (the "Driver Date of Birth" widget) when the error occurs, the rule must be associated with the specificDetail View (DV)orList View (LV)where that field resides (e.g., VehicleIncidentDV). The exhibit lists
"Not Applicable" in the "Name of DV or LV" column. This is incorrect because providing the DV name ensures the error message is displayed contextually next to the field rather than as a generic page-level error, improving the user experience.
Why other options are incorrect:
* Option A:The LOB column is used for filtering, reporting, and release management. Even if the rule logic checks the policy type, the LOB column is required metadata and should not be removed.
* Option B:While the first requirement (the calculation) lacks a DV name (which it should have), it is a Business Rule(assignment), not a validation. Therefore, it doesnotgenerate an error or warning message for the user, so the second part of Option B is incorrect.
* Option E:The "Rules" column is exactly where the calculation logic (Date of Loss - Date of Birth) belongs. The developer needs this information to implement the automation.
NEW QUESTION # 51
An Adjuster at Succeed Insurance is handling a personal auto claim for an insured who hit a tree after swerving to avoid a child who ran into the road.
The Adjuster has this Authority Limit Profile: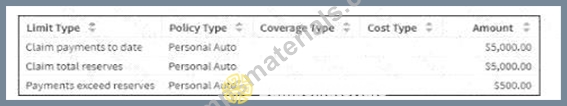
The Adjuster creates a collision exposure and sets the initial reserves so that payments can be made to the insured for repairs to the damaged vehicle. No payments have been created yet.
The current financials for the claim are as follows:
Which two financial transactions will not require approval given that each option is the only transaction change rather than a cumulative change? (Choose two.)
Answer: A,B
Explanation:
To determine if a transaction requires approval, we must compare the proposed transaction against the Adjuster's Authority Limits and the current financial state of the claim.
* Current State:Total Reserves = $3,000 ($2,500 Indemnity + $500 Expense). Total Paid = $0.
* Adjuster Limits:
* Claim Total Reserves Limit: $5,000
* Payments Exceed Reserves Limit: $500
Evaluation of Options:
* Option B (No Approval Required):Making a $2,000 payment against the "Claim Cost - Auto body" reserve.
* The available reserve is $2,500. Since $2,000 < $2,500, the payment does not exceed the reserve.
* The total payments on the claim would be $2,000, which is well below the "Claim payments to date" limit of $5,000.
* Option D (No Approval Required):Increasing the Expense reserve to $550.
* This increases the total claim reserves from $3,000 to $3,050 ($2,500 + $550).
* Since $3,050 is below the Adjuster's "Claim total reserves" limit of $5,000, no approval is triggered.
Why other options require approval:
* Option A:A payment of $1,100 against a $500 reserve means the payment exceeds the reserve by$600.
The Adjuster's limit for "Payments exceed reserves" is only$500. Since $600 > $500, approval is required.
* Option C:Increasing the Auto body reserve to $6,000 would raise the total claim reserves to$6,500 ($6,000 + $500). This exceeds the Adjuster's "Claim total reserves" limit of $5,000, triggering an approval.
NEW QUESTION # 52
......
Our ClaimCenter-Business-Analysts exam questions are so excellent for many advantages. Firstly, the quality of our ClaimCenter-Business-Analysts learning braindumps is very high. You may think that our ClaimCenter-Business-Analysts training materials can only help you to start with confidence, but in fact, they cover the real exam questions and answers. And the accuracy of them will let you surprised. Secondly, the prices for the ClaimCenter-Business-Analysts learning prep are really favorable for every candidate. Even the students can afford it.
ClaimCenter-Business-Analysts Valid Exam Bootcamp: https://www.dumpsmaterials.com/ClaimCenter-Business-Analysts-real-torrent.html
2026 Latest DumpsMaterials ClaimCenter-Business-Analysts PDF Dumps and ClaimCenter-Business-Analysts Exam Engine Free Share: https://drive.google.com/open?id=12qdn_TaOAvlFr3jHkcH0W5cCz1mF1ZQ2