BTW, DOWNLOAD part of ActualCollection PF1 dumps from Cloud Storage: https://drive.google.com/open?id=1QPNrTNjxZCvOiEOmrkS01PF99gAxzizA
As promising learners in this area, every exam candidates need to prove self-ability to working environment to get higher chance and opportunities for self-fulfillment. Our PF1 practice materials with excellent quality and attractive prices are your ideal choices which can represent all commodities in this field as exemplary roles. Even the fierce competition cannot stop demanding needs from exam candidates. To get more specific information about our PF1 practice materials, we are here to satisfy your wish with following details.
| Section | Objectives |
|---|---|
| Topic 1: New Employee Information | - Employee setup and documentation
|
| Topic 2: Year-End Processing | - Federal and provincial year-end reporting
|
| Topic 3: Federal Remittances | - Government remittance obligations
|
| Topic 4: Workers’ Compensation | - Workers compensation administration
|
| Topic 5: Payroll Accounting | - Payroll accounting practices
|
| Topic 6: Non-Regular Payments | - Special payroll payments
|
| Topic 7: Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
| Topic 8: Provincial Remittances | - Provincial payroll requirements
|
| Topic 9: Termination of Employment | - Termination processing
|
| Topic 10: Non-Statutory Deductions | - Voluntary deductions
|
| Topic 11: Record of Employment | - ROE processing
|
| Topic 12: Commission Payments | - Commission payroll processing
|
| Topic 13: Employment Income – Regular Earnings | - Regular payroll calculations
|
We would like to benefit our customers from different countries who decide to choose our PF1 study guide in the long run, so we cooperation with the leading experts in the field to renew and update our PF1 learning materials. Our leading experts aim to provide you the newest information in this field in order to help you to keep pace with the times and fill your knowledge gap. As long as you bought our PF1 Practice Engine, you are bound to pass the PF1 exam for sure.
NEW QUESTION # 34
National Hardware, an Ontario organization, will be terminating the employment of Emilie St. Germain on October 28, 2019, the last day of the pay period. Emilie started with National Hardware on September 19,
2007. Complete the paper Record of Employment (ROE) for Emilie based on the information provided in the following chart.
Note: Vacationable earnings already include the pay in lieu of notice.
All dates must be entered in the format DDMMYYYY.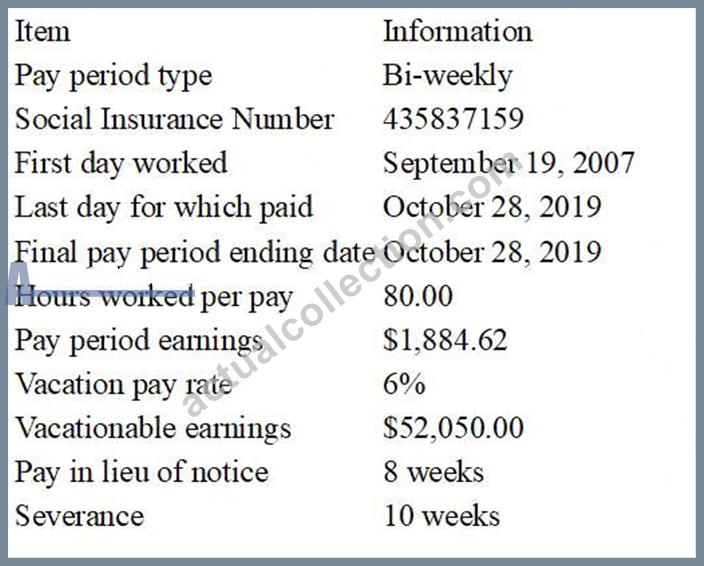
Paper ROE (Form Reference)
Complete the following paper ROE blocks for Emilie:
Block 6 - Pay period type
Block 8 - Social Insurance Number
Block 10 - First day worked
Block 11 - Last day for which paid
Block 12 - Final pay period ending date
Block 15A - Total insurable hours
Block 15B - Total insurable earnings
Block 17A - Vacation pay
Block 17C - Other monies (Pay in lieu of notice)
Block 17C - Other monies (Severance)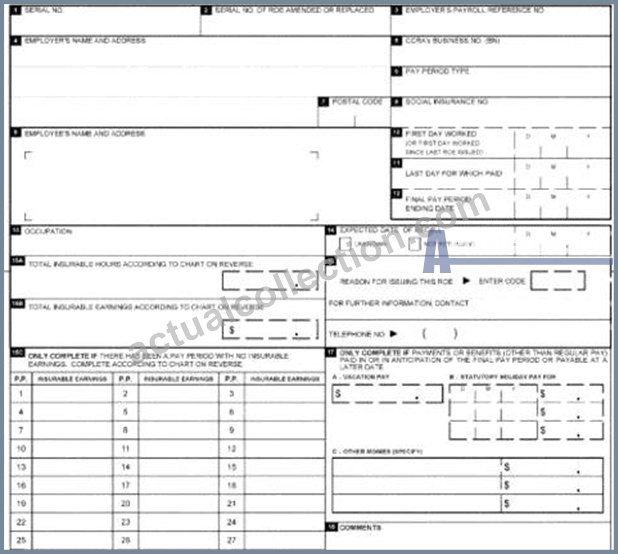
Step 1 - Complete Block 6
Enter the pay period type for Emilie.
Step 2 - Complete Block 8
Enter Emilie's Social Insurance Number.
Step 3 - Complete Block 10
Enter Emilie's first day worked in DDMMYYYY format.
Step 4 - Complete Block 11
Enter Emilie's last day for which paid in DDMMYYYY format.
Step 5 - Complete Block 12
Enter the final pay period ending date in DDMMYYYY format.
Step 6 - Complete Block 15A
Calculate and enter total insurable hours.
Given:
Hours worked per pay period = 80.00
Bi-weekly ROE pay period chart captures 27 pay periods
Step 7 - Complete Block 15B
Calculate and enter total insurable earnings.
Given:
Pay period earnings = $1,884.62
Bi-weekly ROE pay period chart captures 27 pay periods
Step 8 - Complete Block 17A
Calculate and enter vacation pay.
Given:
Vacation pay rate = 6%
Vacationable earnings = $52,050.00
(already includes pay in lieu of notice)
Step 9 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Pay in lieu of notice.
Given:
Pay in lieu of notice = 8 weeks
Use weekly earnings derived from the bi-weekly pay period earnings.
Step 10 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Severance.
Given:
Severance = 10 weeks
Use the same weekly earnings used in Step 9.
Answer:
Explanation:
See the Below Explanation for complete Solution.
Explanation:
Step 1 - Block 6
Bi-weekly
Step 2 - Block 8
435837159
Step 3 - Block 10
September 19, 2007 # 19092007
Step 4 - Block 11
October 28, 2019 # 28102019
Step 5 - Block 12
October 28, 2019 # 28102019
Step 6 - Block 15A (Total insurable hours)
80.00 × 27 = 2160
Block 15A = 2160
Step 7 - Block 15B (Total insurable earnings)
$1,884.62 × 27 = $50,884.74
Block 15B = 50,884.74
Step 8 - Block 17A (Vacation pay)
$52,050.00 × 6% = $3,123.00
Block 17A = 3,123.00
Step 9 - Block 17C (Pay in lieu of notice)
Weekly earnings = $1,884.62 ÷ 2 = $942.31
Pay in lieu = $942.31 × 8 = $7,538.48
Block 17C (Pay in lieu of notice) = 7,538.48
Step 10 - Block 17C (Severance)
Severance = $942.31 × 10 = $9,423.10
Block 17C (Severance) = 9,423.10
NEW QUESTION # 35
The authorization for hiring form should contain a checklist to ensure the organization obtains all required information. What is an example of an item that could be on that checklist?
Answer: C
Explanation:
A strong hire-authorization/onboarding checklist ensures payroll and HR collect documents needed to pay the employee accurately and enroll them in required programs. Abenefit enrollment formis a practical, common checklist item because many employers offer benefit plans that require employee elections (for example, health/dental coverage levels, beneficiary information, dependent details, etc.). Indeed's Canadian onboarding guidance explicitly notes employers often collectbenefits enrollmentpaperwork as part of essential new employee forms and onboarding checklists.
By contrast, aT1213(Request to Reduce Tax Deductions at Source) is not routinely required for all hires; it is only used when an employee applies for CRA authorization to reduce tax withheld. A "clearance certificate" is not a standard Canada-wide payroll onboarding requirement for typical employment relationships.
Therefore, "All of the above" is not correct.
Selectingbenefit enrollment formbest matches the purpose of a hiring authorization checklist: ensuring all employment setup steps are completed (pay setup, statutory forms, and benefits enrollment where offered) so payroll deductions and coverage are handled correctly from the start.
NEW QUESTION # 36
Raminder was hired in January 1997. He was fully vested in the organization's pension plan at the time he received the retiring allowance. His employment was terminated on May 1, 2006 and he was paid a
$10,000.00 retiring allowance. Calculate the eligible portion of the retiring allowance.
Answer: B
Explanation:
The "eligible portion" of a retiring allowance (the part that may be transferred directly to an RRSP/RPP on a tax-deferred basis without using regular RRSP room) is based on years of service before 1996 (and potentially an additional amount for certain pre-1989 years). CRA explains that the eligible part is: $2,000 for each year or part-year of service before 1996, plus an additional $1,500 for each year or part-year of service before 1989 only if no employer-funded pension/DPSP benefits for those years were vested (or previously paid out).
Raminder was hired in January 1997, so he has zero years (or part-years) of service before 1996, and therefore he has no base eligible amount under the $2,000-per-year rule. Because he also has no pre-1989 service, the additional $1,500-per-year rule does not apply either.
So, the eligible portion is $0, meaning none of the $10,000 retiring allowance is eligible (option D).
NEW QUESTION # 37
Which pension plan requires the services of an actuary to study and forecast future needs of the plan to ensure the plan remains sufficiently funded to provide employees with their retirement benefits?
Answer: A
NEW QUESTION # 38
A death benefit is a:
Answer: D
Explanation:
The CRA defines a death benefit as the gross amount of any payment made on or after the death of an employee to recognize the employee's service in an office or employment. It can be paid to a surviving spouse
/common-law partner, heir, or the estate.
This is different from amounts the employee already earned before death (for example, regular wages up to the date of death, or vacation pay that was accrued/earned). CRA guidance treats wages and employment income earned up to and including the date of death as amounts to be reported on a T4 slip, not as a death benefit.
It's also different from a life insurance payout from an insurer (which is not an employer-paid "death benefit" for payroll reporting purposes). The payroll impact is that a qualifying death benefit is generally reported as a special payment (often on a T4A), following CRA rules for deductions and reporting of death benefits.
NEW QUESTION # 39
......
Many people are afraid of walking out of their comfortable zones. So it is difficult for them to try new things. But you will never grow up if you reject new attempt. Now, our PF1 study materials can help you have a positive change. It is important for you to keep a positive mind. Our PF1 Study Materials can become your new attempt. It is not difficult for you. We have simplified all difficult knowledge. So you will enjoy learning our PF1 study materials. During your practice of our PF1 study materials, you will find that it is easy to make changes.
PF1 Valid Dumps Files: https://www.actualcollection.com/PF1-exam-questions.html
BONUS!!! Download part of ActualCollection PF1 dumps for free: https://drive.google.com/open?id=1QPNrTNjxZCvOiEOmrkS01PF99gAxzizA