BONUS!!! Download part of BraindumpsPass IIA-CIA-Part2 dumps for free: https://drive.google.com/open?id=1aTWwGw_tzX-_An8zidm0NwSkGJocE225
We want to finish long term objectives through customer satisfaction and we have achieved it already by our excellent IIA-CIA-Part2 exam questions. In this era of cut throat competition, we are successful than other competitors. What is more, we offer customer services 24/7. Even if you fail the exams, the customer will be reimbursed for any loss or damage after buying our IIA-CIA-Part2 Guide dump. One decision will automatically lead to another decision, we believe our IIA-CIA-Part2 guide dump will make you fall in love with our products and become regular buyers.
| Section | Weight | Objectives |
|---|---|---|
| Performing the Engagement | 40% | - Evaluation of fraud risk and fraud-related indicators during engagements - Assessing IT governance, security, and control frameworks - Root cause analysis and evaluation of evidence - Applying analytical approaches and process mapping techniques - Development of engagement findings: criteria, condition, cause, and effect - Information gathering: interviews, observation, document review, and data analysis - Assessing compliance with laws, regulations, and organizational policies - Use of technology tools to support engagement execution (e.g., CAATs, data analytics) - Drawing conclusions and formulating recommendations - Assessing the adequacy and effectiveness of risk management and controls |
| Planning the Engagement | 20% | - Detailed engagement work program development - Risk and control identification and assessment for the engagement - Engagement objectives, scope, and resource allocation - Coordination with stakeholders during engagement planning - Engagement planning procedures including data analytics and sampling - Understanding business processes, IT systems, and relevant regulations |
| Communicating Engagement Results and Monitoring Progress | 20% | - Developing recommendations vs. requesting management action plans vs. collaborative approaches - Disseminating final results to appropriate stakeholders - Monitoring and follow-up on the resolution of engagement findings - Reporting on the adequacy of management's corrective actions - Attributes of effective engagement communication: accurate, objective, clear, concise, constructive, complete, timely - Communication of engagement results: objectives, scope, conclusions, recommendations, action plans - Management response and action plan tracking |
| Managing the Internal Audit Activity | 20% | - Strategic role of internal audit within governance, risk management, and control - Coordination with external auditors and other internal assurance providers - Risk-based audit planning and alignment with organizational strategy - Managing financial, human, and IT resources within the internal audit function - Internal audit operations: planning, organizing, directing, and monitoring - Knowledge management and information sharing across the internal audit activity |
>> IIA-CIA-Part2 Latest Learning Materials <<
We ensure that if you fail to pass your exam by using IIA-CIA-Part2 exam materials of us, we will give you full refund, and the money will be returned to your payment account. Besides, we are pass guarantee, if you choose us, you can pass the exam, otherwise we will give you refund. IIA-CIA-Part2 exam materials cover most of knowledge points for the exam, and you can master the major knowledge points for the exam as well as improve your professional ability in the process of training materials. In order to let you know the latest information for the exam, we offer you free update for one year for IIA-CIA-Part2 Exam Dumps.
NEW QUESTION # 303
Below is a flowchart detailing an organization's bank reconciliation process. Which of the following conclusions can be drawn from the flowchart?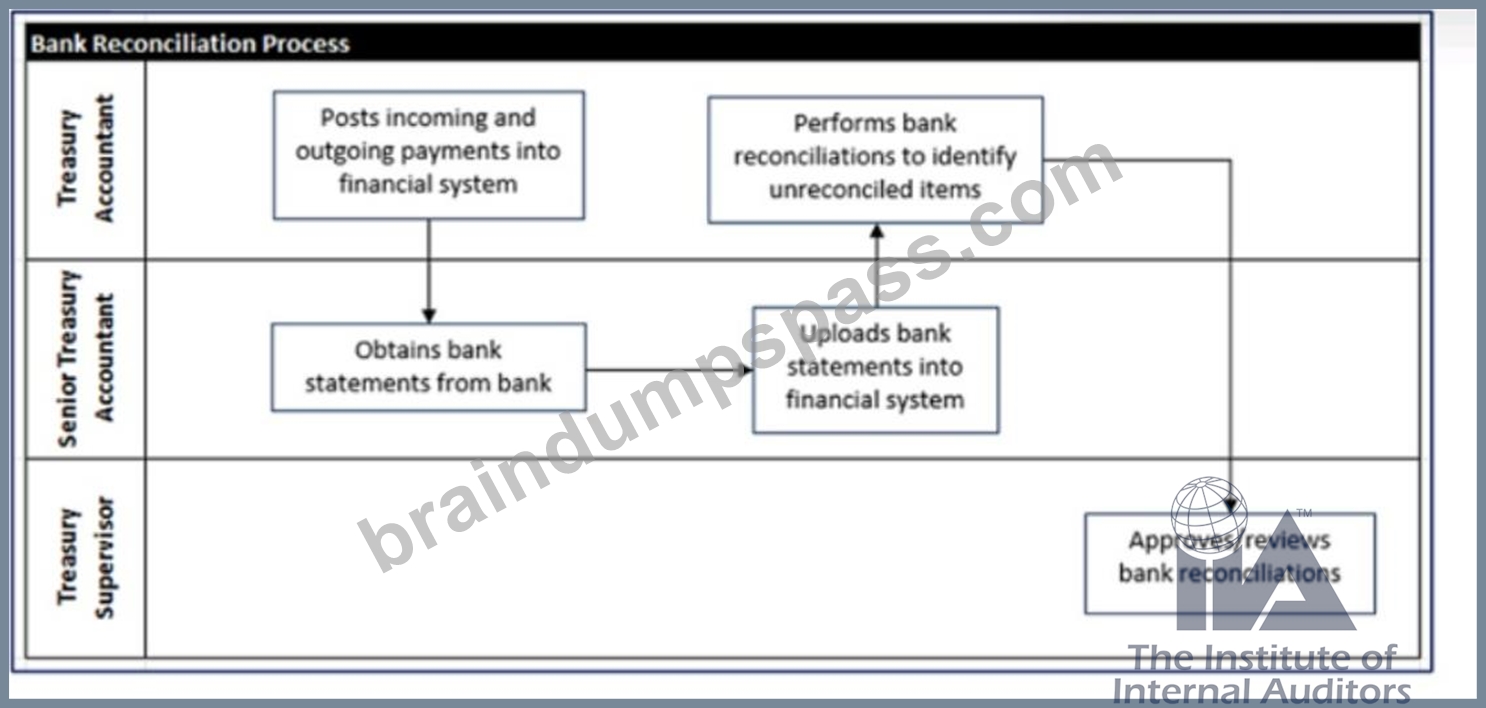
Answer: B
Explanation:
The flowchart indicates that different individuals are responsible for various stages of the bank reconciliation process. The Treasury Accountant posts payments and performs reconciliations, while the Senior Treasury Accountant obtains and uploads bank statements, and the Treasury Supervisor approves/reviews the reconciliations. This segregation of duties ensures that no single individual has control over all aspects of the financial transaction process, which helps in preventing errors and fraud.
Reference:
The Institute of Internal Auditors (IIA), International Standards for the Professional Practice of Internal Auditing (Standards)
"Auditing and Assurance Services" by Alvin
A . Arens, Randal J. Elder, and Mark S. Beasley
NEW QUESTION # 304
Which of the following describes (he primary reason why a preliminary risk assessment is conducted during engagement planning?
Answer: B
Explanation:
The primary reason for conducting a preliminary risk assessment during engagement planning is to ensure that significant risks are included in the engagement scope. This assessment helps the internal auditor focus on areas of highest risk, ensuring that the audit provides the most value by addressing the most critical issues that could impact the organization's objectives.
Reference:
IIA Standards: 2201 - Planning Considerations
IIA Practice Guide: Engagement Planning
NEW QUESTION # 305
According to IIA guidance, which of the following is least likely to be a key financial control in an organization's accounts payable process?
Answer: A
Explanation:
According to IIA guidance, monitoring customer quality complaints compared to the prior period to identify vendor issues is least likely to be a key financial control in an organization's accounts payable process. Key financial controls in accounts payable typically focus on preventing and detecting fraud and errors in the payment process, such as requiring approval for vendor changes, monitoring payment amounts, and comparing employee and vendor addresses to prevent fraud. Monitoring customer quality complaints is more relevant to quality control and vendor management rather than financial control.
IIA Standards: 2130 - Control
IIA Practice Guide: Auditing the Accounts Payable Process
NEW QUESTION # 306
A team of internal auditors is assigned to audit the employee relations process in an organization, which includes employee conduct and disciplinary hearings. Which of the following audit approaches would provide the auditors with the best evidence to determine the degree to which disciplinary decisions are complying with documented policy?
Answer: C
Explanation:
* A. Review a random sample of concluded disciplinary reports to assess how the policy was applied in each case:This is the correct answer because reviewing documented reports provides objective evidence of whether decisions complied with policies. This approach ensures that the auditor relies on concrete evidence rather than subjective opinions or observations.
* B. Interview a sample of impacted employees for their opinions on the clarity and fairness of the policy:
While employee feedback is valuable, it is subjective and does not provide sufficient evidence of compliance with the documented policy.
* C. Observe several disciplinary hearings to determine whether they are in compliance with the policy:
Observations are limited to current proceedings and do not account for how policies were applied in past cases, making this approach less comprehensive.
* D. Conduct an interview to assess the disciplinary hearing chairman's understanding of the policy and its appropriate use:Interviews provide insight into understanding and intent but do not offer evidence of actual compliance.
CIA Exam Syllabus Reference:
Domain V: Performing Internal Audit Services - Evidence Collection and Assessment Methods.
NEW QUESTION # 307
An internal auditor of a construction organization found that completed inspection results, required by the organization's policy, were missing from the computer system. Which of the following, if included in the audit report, would demonstrate that the auditor performed a root cause analysis of this observation?
Answer: B
Explanation:
The CIA Exam (Part 2 - Practice of Internal Auditing) requires auditors to identify the root causes of issues and deviations from criteria, not just report symptoms. A root cause analysis seeks the underlying reason for a problem, rather than describing its occurrence.
* Option A simply describes the condition (missing results).
* Option B identifies a trend but not the underlying cause.
* Option D shifts responsibility to employees without addressing why results were not saved.
* Option C identifies a system design flaw that prevents employees from saving results, which is a true root cause.
Therefore, including Option C in the audit report demonstrates compliance with internal audit methodology, as it highlights the underlying systemic problem instead of merely documenting symptoms or assigning blame.
NEW QUESTION # 308
......
Maybe you have desired the IIA-CIA-Part2 certification for a long time but don't have time or good methods to study. Maybe you always thought study was too boring for you. Our IIA-CIA-Part2 study materials will change your mind. With our products, you will soon feel the happiness of study. Thanks to our diligent experts, wonderful study tools are invented for you to pass the IIA-CIA-Part2 Exam. You can try the demos first and find that you just can't stop studying if you use our IIA-CIA-Part2 training guide.
IIA-CIA-Part2 Valid Real Test: https://www.braindumpspass.com/IIA/IIA-CIA-Part2-practice-exam-dumps.html
DOWNLOAD the newest BraindumpsPass IIA-CIA-Part2 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1aTWwGw_tzX-_An8zidm0NwSkGJocE225